20th Oct 2026 07:00
20 October 2026
B.P. Marsh & Partners Plc
("B.P. Marsh", "the Company" or "the Group")
Half Year Results
Converting Portfolio Value into Shareholder Returns
B.P. Marsh & Partners Plc (AIM: BPM), the specialist private equity investor in early-stage financial services businesses, announces its unaudited Group Half Year Results for the six months to 31 July 2026 (the "Period").
Highlights:
• A record £13.0m of dividends (36.29p per share) paid thus far in the year ending 31 January 2027, equivalent to 3.5% of NAV, including an £8.0m special dividend declared following the sale of Stewart Specialty Risk Underwriting Limited
• Total shareholder return of 7.0% during the Period, and 10.2% for the twelve months to 31 July 2026
• NAV of £372.2m and NAV per share of 1,048.5p* at 31 July 2026 (31 January 2026: £360.2m; 1,009.9p), after the payment of these dividends
• £30.8m of equity proceeds and loan repayments received from the portfolio, including the final £9.6m tranche of deferred consideration from Paladin, US$12.1m received from XPT Group LLC, and £2.5m from Amiga Specialty Holdings Limited
• Three new investments completed during the Period, in Ventura Risk Partners, Nine Edge Wealth and Autonomy Investment Partners, alongside a follow-on investment in Pantheon Specialty Group, increasing the Group’s shareholding to 41.0%
• £9.8m of new and follow-on equity investment and £18.1m of portfolio lending during the Period
• Minimum dividend of £7.0m intended for the year ending 31 January 2028, bringing total dividends paid and/or intended across the three financial years to 31 January 2028 to not less than £28.0m
• Consolidated profit before tax of £22.8m (six months to 31 July 2025: £32.1m)
• Group liquidity of £37.4m at 31 July 2026; the Group remains debt free
*Fully diluted NAV per share of 996.0p (31 January 2026: 959.8p). See the Chief Finance Officer Update for further detail.
Commenting on the results, Daniel Topping, Chief Executive Officer, said:
“I am pleased to report another strong period for B.P. Marsh. The first half of the financial year saw us convert value built up across the portfolio into cash, delivering meaningful returns to shareholders while continuing to invest for future growth.
During the Period, we paid £13.0m in dividends and received £30.8m of equity proceeds and loan repayments from the portfolio. At the same time, we continued to back proven management teams, completing three new investments and increasing our holding in Pantheon. This balance of realisations, shareholder returns and new investment demonstrates the strength of our capital recycling model, with value generated by more mature investments helping to fund the next generation of portfolio growth.
Our approach builds on the partnership-led model established by Brian Marsh OBE, which has delivered compound NAV growth of 10.9% a year since flotation, after distributions. With £37.4m of available cash, no debt and a robust pipeline, the Group remains well placed to continue delivering long-term value for shareholders.”
Analyst briefing and investor presentation:
An analyst presentation will be held today, 20 October 2026 at 9:00am BST. Analysts wishing to attend should contact [email protected] to register. Management will also provide a live presentation for all existing and potential shareholders via the Investor Meet Company platform on 21 October 2026 at 10:30am BST. Investors can sign up for free and add to meet B.P. Marsh & Partners Plc via: https://www.investormeetcompany.com/bp-marsh-partners-plc/register-investor.
For further information on B.P. Marsh, its strategy and current portfolio, please visit www.bpmarsh.co.uk or contact:
B.P. Marsh & Partners Plc | +44 (0)20 7233 3112 |
Daniel Topping / Leah Lashkari |
|
Nominated Adviser & Joint Corporate Broker: Singer Capital Markets Advisory LLP | +44 (0)20 7496 3000 |
Charles Leigh-Pemberton / Peter Steel / James Todd |
|
Joint Corporate Broker: Investec Bank plc | +44 (0)20 7597 5970 |
Christopher Baird / Gordon Hamilton |
|
Financial PR & Investor Relations: Teneo | +44 (0)20 7260 2700 |
James Macey-White / Ffion Dash |
|
About B.P. Marsh
B.P. Marsh & Partners Plc (AIM: BPM) is a specialist investor in early stage and small to medium-sized financial services intermediary businesses, with a particular focus on the insurance sector. Taking a long-term view of its investments, with an average holding period of around seven years, the Group supplies strategic insight and capital while empowering entrepreneurial management teams to grow their businesses. The portfolio is diversified by geography and class of business, spanning insurance brokers, underwriting agencies and financial advisers in the UK, Europe, North America and other international markets.
Chief Executive Officer's Statement
A differentiated and compelling investment opportunity
B.P. Marsh is a specialist investor in insurance and financial services, with a proven track record of long-term value generation. This performance is underpinned by a number of factors:
Being a specialist is a deliberate part of the strategy. Focusing on traditionally underserved verticals, combined with deep sector knowledge built over decades, is a critical differentiator.The market opportunity is very attractive, supported by our sector expertise. We deliberately bridge the structural funding gap overlooked by traditional private equity. We have developed a differentiated business model. B.P. Marsh provides access to specialty, early-stage insurance investment opportunities, supported by clear pathways to cash returns and value realisation.Our strategy has led to consistent returns for shareholders through NAV growth and meaningful dividends, while maintaining a disciplined approach to capital allocation. We are proud of our reputation for being supportive and patient towards the companies and management teams we invest in. We typically take minority positions of 20% to 40% and provide long-term capital and strategic support to the founders and entrepreneurs who drive the business forward.Overview
The first half of the financial year was a period in which the Group converted value built up in the portfolio into cash, returned a significant proportion of it to shareholders, and continued to reinvest alongside proven management teams.
The Group paid £13.0m of dividends during the Period and received £30.8m of equity proceeds and loan repayments from the portfolio. After these distributions, NAV was £372.2m at 31 July 2026 (31 January 2026: £360.2m), total shareholder return for the Period was 7.0%, and for the twelve months to 31 July 2026, total shareholder return was 10.2%.
Activity across the portfolio and balance sheet demonstrates the Group’s capital recycling model. During the Period, £9.8m was deployed in new and follow-on equity investments and £18.1m through portfolio loans, while £20.7m of equity proceeds, including deferred consideration, and £10.1m of loan repayments were received. This combination of investment, realisation and recurring portfolio income enabled the Group to continue supporting its investee companies while returning capital to shareholders and maintaining £37.4m of Group funds at the Period end, with no debt.
The Group's income base continued to build. Portfolio income was £6.5m (31 July 2025: £4.8m), reflecting growth in the loan book and the increasing use of income-generating structures, including the preferred returns attached to the Group's investments in Autonomy, Gambit Re and Oneglobal.
Shareholder returns
During the Period, the Company paid dividends totalling £13.0m (36.29p per share), comprising an interim dividend of £2.5m in February 2026, a special dividend of £8.0m in March 2026 following the disposal of Stewart Specialty Risk Underwriting Limited, and a final dividend of £2.5m in July 2026. The Board intends to pay a minimum of £7.0m for the year ending 31 January 2028, including a £2.0m special dividend linked to the final Paladin deferred consideration.
Including the £8.0m of dividends paid in the year ended 31 January 2026, and the minimum £7.0m intended for the year ending 31 January 2028, the Group has paid, or intends to pay, a total of £28.0m in dividends across the three financial years to 31 January 2028. The Board’s approach remains to balance sustainable cash returns to shareholders with retaining sufficient capital to support the existing portfolio and pursue attractive new opportunities.
In July 2026, the Company announced a new share buy-back programme of up to £2.0m, under which 120,000 shares were repurchased at an average price of £6.77 per share. Since the Period end, and at the time of writing, a further 176,991 shares have been repurchased at an average price of £6.68 per share.
Cash realisations
The Group received £9.6m in March 2026, being the second and final tranche of deferred consideration from the sale of Paladin, the parent company of CBC. In April 2026, the Group also received £0.7m of final deferred consideration from the sale of Stewart Specialty Risk Underwriting Limited (“SSRU”).
In March 2026, the Group completed the sale of its 39.2% shareholding in Amiga Specialty Holdings Limited ("Amiga") to Sodalis Capital Limited ("Sodalis"), also a B.P. Marsh portfolio company, receiving £0.7m in cash together with full repayment of its £1.8m loan. The transaction generated an Internal Rate of Return of 111.9%. The Group retains a 25.6% interest in the enlarged Sodalis group and a pro rata entitlement to deferred consideration linked to Amiga's performance in 2027 and 2028.
In June 2026, on completion of the Autonomy Investment Partners LLC (“Autonomy”) transaction described below, the Group received US$12.1m from XPT Group LLC ("XPT") through the redemption of preferred units and the repayment of debt.
Across the Period, these and other receipts contributed to £20.7m of equity proceeds, including deferred consideration, alongside £10.1m of loan repayments. This cash generation is central to the Group’s ability to recycle capital between mature and developing investments while continuing to fund shareholder distributions.
Portfolio activity
The Period was one of continued investment activity, with the Group deploying capital into three new investments and increasing its holding in Pantheon, while also realising cash from a number of mature portfolio positions. This reflects the Group’s approach of recycling capital generated from successful investments into new opportunities alongside experienced management teams, while maintaining a strong balance sheet and returning capital to shareholders.
New investments
Ventura Risk Partners Holdings Limited ("Ventura")
In March 2026, the Group acquired a 25.0% shareholding in Ventura, a newly formed London-based broker placing energy risks into the Lloyd's and wider London insurance markets. Founded by Alex Taylor, Ventura offers North American retail brokers an independent and specialist route to place complex energy risks in the London market, in a sector that has seen significant consolidation. Since the Group's investment, Ventura has focused on establishing its placement platform across upstream, midstream and renewable energy risks, building on its founder's established relationships with London market underwriters and North American brokers.
Date of initial investment: March 2026
Cost of Equity: £49
Equity stake: 25.0%
Loan Facility: £2,000,000
Nine Edge Wealth Limited ("Nine Edge")
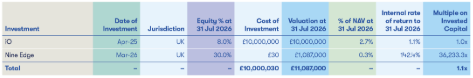
In March 2026, the Group acquired a 30.0% shareholding in Nine Edge, a newly established UK independent financial advice business led by Derek Miles. On completion, Nine Edge acquired Edinburgh-based RMS Limited, with approximately £70.0m of assets under management, providing an established recurring revenue base from which to pursue further organic and acquisitive growth.
Since the Group’s investment, Nine Edge has continued to execute on this strategy, completing the acquisition of Wealth Professional, a UK financial planning business with approximately £340.0m of assets under management and four advisers. Wealth Professional also brings an Adviser Academy focused on developing the next generation of financial advisers. Together, these acquisitions have increased Nine Edge’s acquired assets under management to approximately £410.0m and broadened its presence across the UK.
Date of initial investment: March 2026
31 July 2026 valuation: £1,087,000
Cost of Equity: £30
Equity stake: 30.0%
Loan Facility: £5,000,000
Autonomy Investment Partners LLC ("Autonomy")
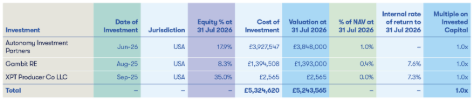
In June 2026, the Group invested US$5.2m for a 17.9% preferred capital interest in Autonomy, a new vehicle formed with the senior management team of XPT and BharCap Partners LLC to provide minority growth capital to independent US insurance distribution businesses. The investment carries an 8.0% preferred annual return and extends the model that has underpinned XPT's growth since 2017. BharCap, a specialist financial services private equity investor with more than US$2.0bn of capital under management, has committed US$100.0m to Autonomy as its largest investor.
As its inaugural transaction, Autonomy acquired a minority stake in XPT, taking this indirect interest into account, the Group's total economic interest in XPT is 28.9%. Autonomy broadens the Group's access to a fragmented segment of the US insurance distribution market while preserving its economic participation in XPT and generating income from inception.
Date of initial investment: June 2026
Cost of Equity: US$5,178,628 (£3,927,547)
Equity stake: 17.9% (preferred capital interest)
Loan Facility: N/A
Follow-on investment
Pantheon Specialty Group Limited ("Pantheon")
In April 2026, the Group acquired a further 2.0% of Pantheon from members of its management team for £5.5m, based on an equity valuation of £275.0m, increasing its shareholding to 41.0%. Since the Group's initial investment in June 2023, Pantheon has delivered significant growth, developing from its original focus on Global Casualty and Professional Lines into a full-service London market wholesale insurance broker with specialist capabilities spanning Marine, Global Property, Innovation & Technology and Delegated Authorities, alongside the continued development of its Energy offering.
Supported by an experienced leadership team and strong relationships across the global insurance market, Pantheon has established itself as a high-quality, scalable independent specialty broking platform with a growing reputation for the placement of complex risks. Revenue is budgeted to approach £27.7m in the 2026 financial year, compared with approximately £23.8m in 2025, with strong margins and significant cash generation supporting continued reinvestment and growth. Pantheon remains the largest contributor to the Group's NAV, demonstrating the significant value created since the Group's original investment.
Date of initial investment: June 2023
31 July 2026 valuation: £112,360,000
Cost of Equity: £32,800,025
Equity stake: 41.0%
Post-period investment
Dauntless U/W Limited ("Dauntless")
Following the Period end, the Group completed an investment in Dauntless, a newly established London Market underwriting agency specialising in marine hull insurance. The Group acquired a 30.0% equity interest in the business for nominal consideration and provided a £2.0m loan facility to support its development.
Dauntless has been founded by experienced marine underwriters Des Keane and Charles Scott-Hopkins and will focus on niche areas of the marine hull market, including brown-water, older and distressed tonnage. The business will operate as an Appointed Representative of DA Strategy Limited and is supported by A-rated Lloyd's carriers. The investment represents a further example of the Group backing experienced management teams at an early stage and builds on its longstanding experience of investing in specialist businesses operating within the Lloyd's and London insurance markets.
Date of initial investment: October 2026
Equity stake: 30.0%
Loan Facility: £2,000,000
Other portfolio company highlights
ATC Insurance Solutions Pty Ltd ("ATC")
ATC continued to pursue its growth and diversification strategy through the acquisition of Frontier Global UW Limited ("Frontier"), a London- and Sydney-based insurance intermediary comprising a Financial Lines MGA and complementary wholesale broking business. The acquisition establishes a London market presence for ATC, strengthens its international underwriting capabilities and broadens its Financial Lines offering.
Sodalis Capital Limited ("Sodalis")
Since the Group’s investment in November 2025, Sodalis has continued to execute its buy-and-build strategy, acquiring Amiga in March 2026 and launching Brecon Specialty Limited, a London-based wholesale insurance broker focused on Cyber and Technology Errors & Omissions risks globally. The addition of both an underwriting platform and a specialist broking operation within its first year of trading demonstrates early progress in building a broader insurance intermediary group.
Oneglobal Broking Holdings Limited ("Oneglobal")
Oneglobal, the international retail and wholesale specialty insurance broker, has performed strongly throughout 2026, with trading year to date in 2026 significantly ahead of both budget and the prior year. The business continues to offer a diversified specialty offering across a number of niche lines of business across the globe. The Group's investment, structured through cumulative convertible preferred shares carrying an 8.0% preferred annual return, provides a recurring income stream alongside participation in Oneglobal's future growth.
Verve Risk Services Limited ("Verve")
Post-Period, Verve continued to expand its underwriting capabilities through the addition of two specialist teams. The first establishes a dedicated US and International Financial Institutions offering, while the second expands Verve’s US Errors & Omissions capabilities into professional liability risks for Lawyers, Architects & Engineers and Accountants. These additions broaden Verve’s product offering and provide access to a wider range of risks.
Portfolio performance
Over the Period, the valuation of the Group's equity portfolio increased from £273.8m at 31 January 2026 to £296.5m at 31 July 2026. Adjusting for additions and disposals during the Period, this represents an underlying increase of approximately 8.8%, reflecting continued value creation across the portfolio.
The increase was broad-based, with a particularly strong contribution from ATC, whose valuation increased by £6.9m to £44.6m as the business continued to grow and diversify its operations, alongside increases across a number of the Group's developing investments, including Sodalis, Oneglobal, Volt, Ai Marine and Devonshire. Pantheon remains the Group's largest investment by value at £112.4m and continues to deliver strong underlying growth.
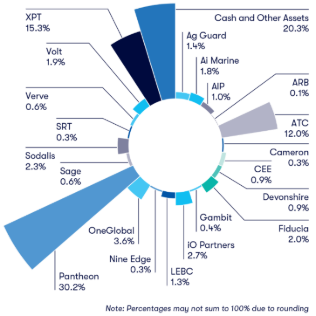
NAV breakdown by portfolio company
The composition of B.P. Marsh's underlying portfolio companies is shown in the chart below.
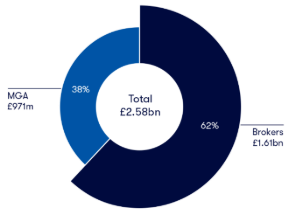
The Group's current insurance investments are budgeting to produce approximately £2.6bn of aggregate gross insurance premium during 2026. A breakdown between the Group's insurance broking and underwriting agency investments is shown below.
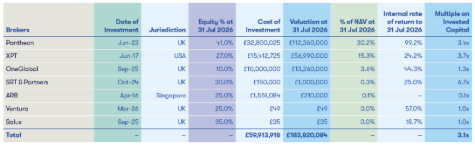
Current insurance brokers
The Group's broking portfolio is budgeting to place over £1.6bn of gross written premium in 2026, generating over £154.7m of brokerage income and accessing specialty insurance markets around the world. The breadth of the broking portfolio provides exposure to a diversified range of specialist classes, geographies and client bases.
Current underwriting agencies
The Group's underwriting agencies are budgeting to underwrite £970.9m of gross written premium in 2026, yielding approximately £112.0m of commission income across a broad range of specialist product areas. These businesses provide exposure to specialist underwriting expertise while retaining the capital-light characteristics of the intermediary model that remains central to the Group's investment strategy.
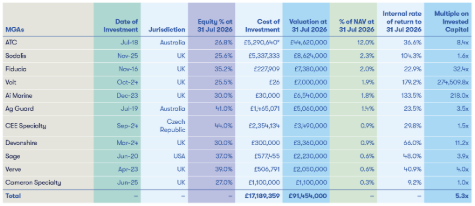
*ATC's equity investment is reported as the combined initial equity investment into ATC, MB Prestige Holdings PTY Limited and Sterling Insurance PTY Limited.
Current other financial services investments
While insurance-related businesses remain B.P. Marsh's primary focus, the Group selectively invests in adjacent financial services where its sector experience, network and patient capital can create value. These investments broaden the portfolio while remaining consistent with the Group's focus on specialist, entrepreneurial financial services businesses.
Current other XPT-related insurance vehicle investments
The Group also maintains interests in insurance-related investment vehicles connected with XPT and the wider development of specialist insurance distribution businesses in North America. These investments provide additional exposure to the growth of the underlying businesses and complement the Group's direct investment in XPT.
Market and new business
The Group’s portfolio remains focused on specialty and niche businesses, many of which are earlier-stage investments where growth is driven more by new client wins, increasing policy count, market share gains and the development of new products and distribution opportunities than by movements in market pricing alone. Together with the fee and commission-based nature of broker and underwriting agency revenues, this continues to support organic growth across the portfolio.
Against this backdrop, commercial insurance pricing continued to moderate during the Period, with global rates declining by 6% in the second quarter of 2026, although trends remained varied across individual classes¹. Given the nature of the Group’s investments and their underlying growth drivers, the portfolio is relatively insulated from movements in headline commercial insurance pricing.
Consolidation across insurance distribution also continued during 2026. During the first half of the year, 41 M&A transactions were announced across the UK insurance distribution sector. Of these, approximately 17 involved private equity capital, representing 41% of total deal activity, while more than a quarter involved specialty businesses2.
The Group continues to view this environment as a source of opportunity, both for existing portfolio companies pursuing selective acquisitions and for experienced teams seeking an independent, long-term capital partner.
The Group received 42 new business enquiries during the Period (six months to 31 July 2025: 32), demonstrating sustained inbound interest in the Group’s partnership-led investment approach and sector expertise. The Group continues to maintain a healthy pipeline of prospective investments across its target markets.
¹ Marsh Global Insurance Market Index, Q2 2026.
2 MarshBerry, A(Nother) Quiet First Half For UK Insurance Distribution M&A, 7 July 2026.
Outlook
With £37.4m of Group funds at 31 July 2026, no debt, a growing income base and a robust pipeline, the Group remains well positioned to balance selective new investment with continued returns to shareholders, and to support its entrepreneurial management teams as they grow their businesses. The Board continues to see attractive opportunities created by sector consolidation and by experienced teams seeking patient, supportive capital, while the increasing maturity of parts of the portfolio provides further potential for cash realisations and capital recycling over time. The post-Period investment in Dauntless demonstrates the continued availability of opportunities to deploy capital in specialist areas where the Group has established market knowledge and experience.
Daniel Topping
Chief Executive Officer
20 October 2026
Chief Finance Officer Update
NAV and returns
At 31 July 2026, the Group's NAV was £372.2m (31 January 2026: £360.2m), an increase of £12.0m (3.4%) over the Period after the payment of £13.0m of dividends and £1.2m of share buy-backs. Including dividends paid, this represented an overall return of 7.0% for the Period (31 July 2025: 9.5%).
Since flotation in 2006, the Group has delivered an annual compound growth rate of 10.9% in NAV after running costs, realisations, losses, distributions and corporation tax (12.9% since 1990).
Investment performance
The Group deployed £9.8m in new and follow-on equity investments during the Period (31 July 2025: £19.7m), including £5.5m to increase its interest in Pantheon, US$5.2m in Autonomy and £0.4m into Sage alongside nominal equity subscriptions in Ventura and Nine Edge.
Income, expenses and profit
Net gains from investments were £24.0m (31 July 2025: £31.3m). Portfolio income was £6.5m (31 July 2025: £4.8m) and operating expenses were £8.2m (31 July 2025: £4.9m). Approximately 79% of the year-on-year increase in operating expenses was attributable to a one-off prior-year catch-up charge of £2.6m, comprising a £1.5m share-based payment charge and £1.1m of associated employer’s National Insurance, arising from the revaluation of share options reallocated to staff in March 2025.
Profit before tax was £22.8m (31 July 2025: £32.1m). On an underlying basis, excluding unrealised investment activity and the one-off catch-up costs, the Group recorded a pre-tax profit of £2.5m (31 July 2025: £0.7m), in line with its strategy of covering expenses from portfolio yield.
Liquidity and loan portfolio
The loan portfolio was £46.9m at 31 July 2026 (31 January 2026: £38.8m), after £18.1m of new loans and drawdowns to support new and existing portfolio companies and £10.1m of repayments, including £1.8m from Amiga. The average interest rate charged on the loan portfolio at 31 July 2026 was 8.3%.
At 31 July 2026, the Group had cash and treasury funds of £37.4m (31 January 2026: £49.5m). The movement during the Period reflects £9.8m of new and follow-on equity investments, £18.1m of portfolio loans, £13.0m of dividends and £1.2m of share buy-backs, offset by £20.7m of equity proceeds, including deferred consideration, and £10.1m of loan repayments. Key receipts included £9.6m from Paladin and US$12.1m from XPT. The Group remains debt free.
NAV per share
Undiluted NAV per share was 1,048.5p (31 January 2026: 1,009.9p) and fully diluted NAV per share was 996.0p (31 January 2026: 959.8p). The diluted figure includes the 761,499 shares held within the Employee Benefit Trust, the associated £1.9m loan and the 1,685,000 share options for which the NAV performance criteria have been met.
Francesca Chappell
Chief Finance Officer
20 October 2026
Forward-looking statements:
Certain statements in this announcement are forward-looking statements. In some cases, these forward looking statements can be identified by the use of forward-looking terminology including the terms "anticipate", "believe", "intend", "estimate", "expect", "may", "will", "seek", "continue", "aim", "target", "projected", "plan", "goal", "achieve" and words of similar meaning or in each case, their negative, or other variations or comparable terminology. Forward-looking statements are based on current expectations and assumptions and are subject to a number of known and unknown risks, uncertainties and other important factors that could cause results or events to differ materially from what is expressed or implied by those statements. Important factors that could cause actual results, performance or achievements of B.P. Marsh to differ materially from the expectations of B.P. Marsh include, among other things, general business and economic conditions globally, industry trends, competition, changes in government and changes in regulation and policy, changes in its business strategy, political and economic uncertainty and other factors. As such, undue reliance should not be placed on forward-looking statements. Other than in accordance with legal and regulatory obligations, B.P. Marsh undertakes no obligation to publicly update or revise any forward-looking statement, whether as a result of new information, future events or otherwise. Nothing in this announcement should be regarded as a profit forecast.
Investments
As at 31 July 2026 the Group's equity interests were as follows. Further detail on each investment is available at www.bpmarsh.co.uk.
Investment | Category | Date of investment | Equity stake | 31 July 2026 valuation |
Ag Guard PTY Limited | Underwriting agency | July 2019 | 41.0% | £5,060,000 |
Ai Marine Risk Limited | Underwriting agency | December 2023 | 30.0% | £6,540,000 |
Asia Reinsurance Brokers (Pte) Limited | Broker | April 2016 | 25.0% | £210,000 |
ATC Insurance Solutions PTY Limited | Underwriting agency | July 2018 | 26.8% | £44,620,000 |
Autonomy Investment Partners LLC | Investment vehicle | June 2026 | 17.9% | £3,848,000 |
Cameron Specialty HoldCo Limited | Underwriting agency | June 2025 | 27.0% | £1,100,000 |
CEE Specialty s.r.o. | Underwriting agency | September 2024 | 44.0% | £3,490,000 |
Devonshire UW Limited | Underwriting agency | March 2024 | 30.0% | £3,360,000 |
The Fiducia MGA Company Limited | Underwriting agency | November 2016 | 35.2% | £7,380,000 |
Gambit Risk Finance LLC | Reinsurance vehicle | August 2025 | 8.3% | £1,393,000 |
iO Finance Partners Topco Limited | Alternative finance | April 2025 | 8.0% | £10,000,000 |
LEBC Holdings Limited | Holding company | April 2007 | 62.0% | £4,900,000 |
New Denison Limited | Holding company | June 2023 | 40.0% | £0 |
Nine Edge Wealth Limited | Financial advice | March 2026 | 30.0% | £1,087,000 |
Oneglobal Broking Holdings Limited | Broker | September 2025 | 10.0% | £13,260,000 |
Pantheon Specialty Group Limited | Broker | June 2023 | 41.0% | £112,360,000 |
Sage Program Underwriters, Inc. | Underwriting agency | June 2020 | 37.0% | £2,230,000 |
Salus Capital Partners Limited | Broker / underwriting agency | September 2025 | 35.0% | £35 |
Sodalis Capital Limited | Intermediary group | November 2025 | 25.6% | £8,624,000 |
SRT & Partners Limited | Broker | October 2024 | 30.0% | £1,000,000 |
Ventura Risk Partners Holdings Limited | Broker | March 2026 | 25.0% | £49 |
Verve Risk Services Limited | Underwriting agency | April 2023 | 39.0% | £2,050,000 |
Volt UW Limited | Underwriting agency | October 2024 | 25.5% | £7,000,000 |
XPT Group LLC | Broker / underwriting agency | June 2017 | 27.0% | £56,990,000 |
XPT Producer Co LLC | Producer platform | September 2025 | 35.0% | £2,565 |
These investments have been valued in accordance with the accounting policies set out in the Group's Annual Report for the year ended 31 January 2026.
Half Year Consolidated Financial Statements
CONSOLIDATED STATEMENT OF COMPREHENSIVE INCOME
FOR THE PERIOD ENDED 31 JULY 2026
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
The result for the period is wholly attributable to continuing activities.
CONSOLIDATED STATEMENT OF FINANCIAL POSITION
AS AT 31 JULY 2026
(Company Number: 05674962)
|
| Unaudited |
| Unaudited |
| Audited | |||
| Notes | 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 | |||
|
| £'000 | £'000 |
| £'000 | £'000 |
| £'000 | £'000 |
ASSETS |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
NON-CURRENT ASSETS |
|
|
|
|
|
|
|
|
|
Property, plant and equipment |
| 321 |
|
| 79 |
|
| 296 |
|
Right-of-use asset |
| 1,726 |
|
| 260 |
|
| 177 |
|
Investments – equity portfolio | 5 | 296,505 |
|
| 271,450 |
|
| 273,766 |
|
Loans and receivables |
| 37,468 |
|
| 22,777 |
|
| 28,724 |
|
|
|
| 336,020 |
|
| 294,566 |
|
| 302,963 |
CURRENT ASSETS |
|
|
|
|
|
|
|
|
|
Trade and other receivables |
| 14,640 |
|
| 15,989 |
|
| 23,379 |
|
Cash and cash equivalents | 6 | 37,422 |
|
| 52,584 |
|
| 49,480 |
|
|
|
| 52,062 |
|
| 68,573 |
|
| 72,859 |
LIABILITIES |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
NON-CURRENT LIABILITIES |
|
|
|
|
|
|
|
|
|
Lease liabilities |
| (1,770) |
|
| (117) |
|
| (15) |
|
Deferred tax liabilities | 10 | (11,780) |
|
| (12,339) |
|
| (12,596) |
|
|
|
| (13,550) |
|
| (12,456) |
|
| (12,611) |
CURRENT LIABILITIES |
|
|
|
|
|
|
|
|
|
Trade and other payables |
| (2,211) |
|
| (980) |
|
| (2,850) |
|
Lease liabilities |
| (72) |
|
| (198) |
|
| (203) |
|
|
|
| (2,283) |
|
| (1,178) |
|
| (3,053) |
|
|
|
|
|
|
|
|
|
|
NET ASSETS |
|
| 372,249 |
|
| 349,505 |
|
| 360,158 |
|
|
|
|
|
|
|
|
|
|
CAPITAL AND RESERVES - EQUITY |
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
Called up share capital | 8 |
| 3,710 |
|
| 3,710 |
|
| 3,710 |
Share premium account |
|
| 29,365 |
|
| 29,359 |
|
| 29,362 |
Fair value reserve |
|
| 183,492 |
|
| 172,084 |
|
| 160,478 |
Reverse acquisition reserve |
|
| 393 |
|
| 393 |
|
| 393 |
Capital redemption reserve |
|
| 44 |
|
| 44 |
|
| 44 |
Capital contribution reserve |
|
| 72 |
|
| 72 |
|
| 72 |
Retained earnings |
|
| 155,173 |
|
| 143,843 |
|
| 166,099 |
|
|
|
|
|
|
|
|
|
|
SHAREHOLDERS’ FUNDS - EQUITY |
|
| 372,249 |
|
| 349,505 |
|
| 360,158 |
|
|
|
|
|
|
|
|
|
|
Net Asset Value per share – undiluted (pence) | 4 |
| 1048.5p |
|
| 956.1p |
|
| 1009.9p |
Net Asset Value per share – diluted (pence) | 4 |
| 996.0p |
|
| 909.8p |
|
| 959.8p |
The Interim Consolidated Financial Statements were approved by the Board of Directors and authorised for issue on 19 October 2026
and signed on its behalf by:
Daniel Topping & Francesca Chappell
CONSOLIDATED STATEMENT OF CASH FLOWS
FOR THE PERIOD ENDED 31 JULY 2026
|
|
|
|
| ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
All differences between the amounts stated in the Consolidated Statement of Cash Flows and the Consolidated Statement of Comprehensive Income are attributed to non-cash movements.
The presentation of the Consolidated Statement of Cash Flows was revised in the financial statements for the year ended 31 January 2026 to better align with the Group’s operations. The same presentation has been adopted in these interim financial statements, and the comparative figures for the six months ended 31 July 2025 have been restated accordingly. There is no change to the net cash flows previously reported.
CONSOLIDATED STATEMENT OF CHANGES IN EQUITY
FOR THE PERIOD ENDED 31 JULY 2026
|
| Unaudited | Unaudited | Audited |
|
| 6 months to | 6 months to | Year to |
|
| 31 July 2026 | 31 July 2025 | 31 January 2026 |
|
| £’000 | £’000 | £’000 |
|
|
|
|
|
Opening total equity |
| 360,158 | 326,410 | 326,410 |
Comprehensive income for the period |
| 23,617 | 31,552 | 48,217 |
Dividends paid |
| (12,989) | (7,973) | (7,973) |
Repurchase of company shares |
| (1,219) | (1,023) | (6,912) |
Share incentive and share option plan |
| 2,621 | 211 | 406 |
Amounts received from the Employee Benefit Trust relating to shares held under joint ownership |
| 80 | - | - |
Other movements |
| (19) | 328 | 10 |
Total equity |
| 372,249 | 349,505 | 360,158 |
|
|
|
|
|
|
|
|
|
|
| Share |
| Reverse | Capital | Capital |
|
|
| Share | premium | Fair value | acquisition | redemption | contribution | Retained |
|
| capital | account | reserve | reserve | reserve | reserve | earnings | Total |
| (£’000) | (£’000) | (£’000) | (£’000) | (£’000) | (£’000) | (£’000) | (£’000) |
|
|
|
|
|
|
|
|
|
At 1 February 2026 | 3,710 | 29,362 | 160,478 | 393 | 44 | 72 | 166,099 | 360,158 |
|
|
|
|
|
|
|
|
|
Comprehensive income for the period | - | - | 23,720 | - | - | - | (103) | 23,617 |
|
|
|
|
|
|
|
|
|
Net transfers on disposal of investments (Note 7) | - | - | (706) |
|
|
| 706 | - |
|
|
|
|
|
|
|
|
|
Dividends paid | - | - | - | - | - | - | (12,989) | (12,989) |
|
|
|
|
|
|
|
|
|
Repurchase of Company shares (Note 8) | - | - | - | - | - | - | (1,219) | (1,219) |
|
|
|
|
|
|
|
|
|
Share-based payment arrangements (Note 11) | - | 3 | - | - | - | - | 2,618 | 2,621 |
|
|
|
|
|
|
|
|
|
Amounts received from the Employee Benefit Trust relating to shares held under joint ownership (Note 11) | - | - | - | - | - | - | 80 | 80 |
|
|
|
|
|
|
|
|
|
Other movements | - | - | - | - | - | - | (19) | (19) |
|
|
|
|
|
|
|
|
|
At 31 July 2026 | 3,710 | 29,365 | 183,492 | 393 | 44 | 72 | 155,173 | 372,249 |
|
|
|
|
|
|
|
|
|
NOTES TO THE CONSOLIDATED FINANCIAL STATEMENTS
FOR THE PERIOD ENDED 31 JULY 2026
ACCOUNTING POLICIES
Basis of preparation of financial statements
These condensed consolidated interim financial statements were approved by the Board for issue on 19 October 2026, and have been prepared as at, and for the six months ended, 31 July 2026. This Interim Report has been prepared in accordance with the AIM Rules for Companies. It does not and is not required to comply with IAS 34 ‘Interim Financial Reporting’. The accounting policies applied by the Group in this Interim Report are consistent with those of the previous financial year and corresponding half year reporting period.
The financial information contained within this Interim Report has been prepared applying the recognition and measurement requirements of UK-adopted international accounting standards expected to apply at 31 January 2027.
These condensed consolidated interim financial statements do not constitute statutory accounts as defined in Section 434 of the Companies Act 2006. The interim financial statements for the half year ended 31 July 2026 were neither audited nor reviewed by the Company’s auditors.
The financial information for the year ended 31 January 2026 is based on audited statutory accounts which have been filed with the Registrar of Companies. The Auditor’s report for 2026 was (i) unqualified, (ii) included no matters to which the auditor drew attention by way of emphasis and (iii) did not contain statements under Sections 498 (2) or 498 (3) of the Companies Act 2006 in relation to the financial statements.
The consolidated financial statements are presented in sterling, the functional currency of the Group, rounded to the nearest thousand pounds (£’000) except where otherwise indicated.
The preparation of financial statements in conformity with UK-adopted international accounting standards requires management to make judgements, estimates and assumptions that affect the application of policies and reported amounts of assets and liabilities, income and expenses. The estimates and associated assumptions are based on historical experience and various other factors that are believed to be reasonable in the circumstances, the results of which form the basis of judgements about the carrying amounts of assets and liabilities. Actual results may differ from those amounts.
Going concern
These condensed consolidated interim financial statements have been prepared on a going concern basis.
In adopting the going concern basis for preparing the financial statements, the directors have considered the Group’s business activities, together with the principal risks and uncertainties likely to affect its future development, performance and position. The directors have also reviewed the Group’s management projections and cash flow forecasts for the period to 31 January 2028.
These forecasts and projections, taking account of reasonably possible changes in trading performance, indicate that the Group will have sufficient financial resources to continue in operational existence for the foreseeable future and to meet its liabilities as they fall due.
Accordingly, the directors continue to adopt the going concern basis in preparing these condensed consolidated interim financial statements.
Significant management judgements
In the process of applying the Group’s accounting policies, management has made the following judgements, which have the most significant effect on the amounts recognised in the financial statements:
Assessment as an investment entity
Entities that meet the definition of an investment entity within IFRS 10: Consolidated Financial Statements (“IFRS 10”) are required to account for their investments in controlled entities, as well as investments in associates at fair value through profit or loss. Subsidiaries that provide investment related services or engage in permitted investment related activities with investees that relate to the parent investment entity’s investment activities continue to be consolidated in the Group results. The criteria which define an investment entity are currently as follows:
an entity that obtains funds from one or more investors for the purpose of providing those investors with investment services; an entity that commits to its investors that its business purpose is to invest funds solely for returns from capital appreciation, investment income or both; and an entity that measures and evaluates the performance of substantially all of its investments on a fair value basis.
The Group’s annual and interim consolidated financial statements clearly state its objective of investing directly into portfolio investments and providing investment management services to investors for the purpose of generating returns in the form of investment income and capital appreciation. The Group has always reported its investment in portfolio investments at fair value. It also produces reports for investors of the funds it manages and its internal management report on a fair value basis. The exit strategy for all investments held by the Group is assessed, initially, at the time of the first investment and this is documented in the investment paper submitted to the Board for approval.
The Board has also concluded that the Company meets the additional characteristics of an investment entity, in that it has more than one investment; the investments are predominantly in the form of equities and similar securities; it has more than one investor and its investors are not related parties. The Board has concluded that B.P. Marsh & Partners Plc and its three trading subsidiaries, B.P. Marsh & Company Limited, B.P. Marsh (North America) Limited and B.P. Marsh Europe Limited, which provide investment related services on behalf of B.P. Marsh & Partners Plc, all meet the definition of an investment entity. These conclusions will be reassessed on an annual basis for changes to any of these criteria or characteristics.
When it is established that a parent company is an investment entity, its subsidiaries are measured at fair value through profit or loss. However, if an investment entity has subsidiaries that provide services that relate to the investment entity’s investment activities, the exception to the Amendment of IFRS 10 is not applicable as in this case, the parent investment entity still consolidates the results of its subsidiaries. Therefore, the results of B.P. Marsh & Company Limited, B.P. Marsh (North America) Limited and B.P. Marsh Europe Limited are consolidated into its Group financial statements for the period.
Significant accounting estimates
Fair value of equity portfolio
The most significant estimates relate to the fair valuation of the equity investment portfolio as detailed in Note 5 to the Financial Statements. The valuation methodology for the investment portfolio is detailed below. The estimates and underlying assumptions are reviewed on an ongoing basis. Revisions to accounting estimates are recognised in the period in which the estimate is revised if the revision affects only that period, or in the period of the revision and future periods if the revision affects both current and future periods.
The accounting policies set out below have been applied consistently to all periods presented in these condensed consolidated interim financial statements.
Basis of consolidation
Subsidiaries
Subsidiaries are entities controlled by the Group. Control, as defined by IFRS 10, is achieved when the Group is exposed, or has rights, to variable returns from its involvement with the investee and has the ability to affect those returns through its power over the investee. Specifically, the Group controls an investee if and only if the Group has:
power over the investee (i.e. existing rights that give it the current ability to direct the relevant activities of the investee); exposure, or rights, to variable returns from its involvement with the investee; and the ability to use its power over the investee to affect its returns.
When the Group has less than a majority of the voting or similar rights of an investee, the Group considers all relevant facts and circumstances in assessing whether it has power over an investee, including:
a) rights arising from other contractual arrangements; and
b) the Group’s voting rights and potential voting rights.
The Group re-assesses whether or not it controls an investee if facts and circumstances indicate that there are changes to one or more of the elements of control.
B.P. Marsh & Partners Plc (“the Company”), an investment entity, has three subsidiary investment entities, B.P. Marsh & Company Limited, B.P. Marsh (North America) Limited and B.P. Marsh Europe Limited, that provide services that relate to the Company’s investment activities. The results of these three subsidiaries, together with other subsidiaries (except for LEBC Holdings Limited (“LEBC”)), are consolidated into the Group consolidated financial statements. The Group has taken advantage of the Amendment to IFRS 10 not to consolidate the results of LEBC. Instead the investment in LEBC is valued at fair value through profit or loss.
Associates
Associates are those entities in which the Group has significant influence, but not control, over the financial and operating policies. Investments that are held as part of the Group’s investment portfolio are carried in the Consolidated Statement of Financial Position at fair value even though the Group may have significant influence over those companies.
Investments – equity portfolio
All equity portfolio investments are designated as “fair value through profit or loss” assets and are initially recognised at the fair value of the consideration. They are measured at subsequent reporting dates at fair value.
The Board conducts the valuations of equity portfolio investments. In valuing equity portfolio investments the Board applies guidelines issued by the International Private Equity and Venture Capital Valuation Committee (“IPEV Guidelines”). The following valuation methodologies have been used in reaching fair value of equity portfolio investments, some of which are in early stage companies:
at cost, unless there has been a significant round of new equity finance in which case the investment is valued at the price paid by an independent third party. Where subsequent events or changes to circumstances indicate that an impairment may have occurred, the carrying value is reduced to reflect the estimated extent of impairment; by reference to underlying funds under management; by applying appropriate multiples to the earnings and revenues and/or premiums of the investee company; or by reference to expected future cash flow from the investment where a realisation or flotation is imminent.
Both realised and unrealised gains and losses arising from changes in fair value are taken to the Consolidated Statement of Comprehensive Income for the period. In the Consolidated Statement of Financial Position the unrealised gains and losses arising from changes in fair value are shown within a “fair value reserve” separate from retained earnings. Transaction costs on acquisition or disposal of equity portfolio investments are expensed in the Consolidated Statement of Comprehensive Income.
Equity portfolio investments are treated as ‘Non-current Assets’ within the Consolidated Statement of Financial Position unless the directors have committed to a plan to sell the investment and an active programme to locate a buyer and complete the plan has been initiated. Where such a commitment exists, and if the carrying amount of the equity portfolio investment will be recovered principally through a sale transaction rather than through continuing use, the investment is classified as an ‘Investments - Assets held for sale’ under ‘Current Assets’ within the Consolidated Statement of Financial Position.
Income
Income comprises:
gross interest from loans, which is taken to the Consolidated Statement of Comprehensive Income on an accruals basis;
dividends from equity investments are recognised in the Consolidated Statement of Comprehensive Income when the shareholders rights to receive payment have been established; and
advisory fees from management services provided to investee companies, which are recognised on an accruals basis in accordance with the substance of the relevant investment advisory agreement.
2. SEGMENTAL REPORTING
The Group operates in one business segment, provision of consultancy services to, as well as making and trading investments in, financial services businesses. The directors consider that there is one reportable segment for the Group as all investments are monitored individually by the Board, which is considered to be the Chief Operating Decision maker based on the definitions within IFRS 8: Operating Segments (“IFRS 8”).
3. OPERATING EXPENSES
|
| Unaudited |
| Unaudited |
| Audited |
|
| 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 |
|
| £'000 |
| £'000 |
| £'000 |
|
|
|
|
|
|
|
Staff costs |
| 3,018 |
| 3,072 |
| 10,994 |
Share-based payment costs and related Employer’s NI (see Note 11) |
| 3,967 |
| 192 |
| 386 |
Other operating costs |
| 1,171 |
| 1,660 |
| 3,410 |
|
| 8,156 |
| 4,924 |
| 14,790 |
4. EARNINGS AND NET ASSET VALUE PER SHARE FROM CONTINUING OPERATIONS ATTRIBUTABLE TO THE EQUITY SHAREHOLDERS
|
| Unaudited |
| Unaudited |
| Audited |
|
| 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 |
|
| £’000 |
| £’000 |
| £’000 |
Earnings |
|
|
|
|
|
|
Earnings for the purposes of basic and diluted earnings per share being total comprehensive income attributable to equity shareholders |
| 23,617 |
| 31,552 |
| 48,217 |
Earnings per share – basic |
|
66.0p |
|
85.7p |
|
132.6p |
Earnings per share - diluted |
| 62.7p |
| 81.4p |
| 125.9p |
|
|
|
|
|
|
|
Number of shares |
| Number |
| Number |
| Number |
Weighted average number of ordinary shares for the purposes of basic earnings per share |
|
35,775,953 |
|
36,828,238 |
|
36,369,701 |
|
|
|
|
|
|
|
Number of dilutive shares under option1 |
| 1,921,259 |
| 1,921,259 |
|
1,921,259 |
|
|
|
|
|
|
|
Weighted average number of ordinary shares for the purposes of dilutive earnings per share |
|
37,697,212 |
|
38,749,497 |
|
38,290,960 |
|
|
|
|
|
|
|
1 The number of dilutive shares under option as at 31 July 2026 comprised 236,259 (31 July 2025 and 31 January 2026: 236,259) unallocated JSOP shares held within the Employee Benefit Trust and 1,685,000 (31 July 2025 and 31 January 2026: 1,685,000) options held under the Group’s Share Option Plan (Note 11).
|
| Unaudited |
| Unaudited |
| Audited |
|
| 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 |
|
| £’000 |
| £’000 |
| £’000 |
Net Asset Value |
|
|
|
|
|
|
Basic Net Asset Value |
|
|
|
|
|
|
Net Asset Value attributable to equity shareholders
|
| 372,249 |
| 349,505 |
| 360,158 |
Adjustment to Net Asset Value1 |
| 1,476 |
| 1,476 |
| 1,476
|
Adjusted Net Asset Value for the purposes of basic Net Asset Value per share being total Net Asset Value attributable to equity shareholders |
|
373,725
|
|
350,981
|
| 361,634 |
|
|
|
|
|
|
|
Diluted Net Asset Value |
|
|
|
|
|
|
Net Asset Value attributable to equity shareholders
|
| 372,249 |
| 349,505 |
| 360,158 |
Adjustment to Net Asset Value2 |
| 1,900 |
| 1,980 |
| 1,980 |
Adjusted Net Asset Value for the purposes of diluted Net Asset Value per share being total Net Asset Value attributable to equity shareholders |
| 374,149 |
| 351,485 |
| 362,138 |
|
|
|
|
|
|
|
Net Asset Value per share – basic |
| 1048.5p |
| 956.1p |
|
1009.9p |
Net Asset Value per share - diluted |
| 996.0p |
| 909.8p |
| 959.8p |
|
|
|
|
|
|
|
Number of shares |
| Number |
| Number |
| Number |
Number of ordinary shares for the purposes of basic Net Asset Value per share |
| 35,644,253 |
| 36,710,555 |
|
35,808,741 |
|
|
|
|
|
|
|
Number of dilutive shares under option3 |
| 1,921,259 |
| 1,921,259 |
| 1,921,259 |
|
|
|
|
|
|
|
Number of ordinary shares for the purposes of dilutive Net Asset Value per share |
| 37,565,512 |
| 38,631,814 |
|
37,730,000 |
|
|
|
|
|
|
|
1 Adjustment to Net Asset Value represents the cash receivable by the Group when the 525,240 (31 July 2025 and 31 January 2026: 525,240) remaining allocated ordinary shares that are held under joint ownership arrangements within the Employee Benefit Trust, and which were considered fully dilutive as at 31 July 2026, are sold.
2 Adjustment to Net Asset Value represents the cash receivable by the Group when the total remaining 761,499 (31 July 2025 and 31 January 2026: 761,499) allocated and unallocated ordinary shares that are held under joint ownership arrangements within the Employee Benefit Trust, are sold.
3 The number of dilutive shares under option as at 31 July 2026 comprised 236,259 (31 July 2025 and 31 January 2026: 236,259) unallocated JSOP shares held within the Employee Benefit Trust and 1,685,000 (31 July 2025 and 31 January 2026: 1,685,000) options held under the Group’s Share Option Plan (Note 11).
5. NON-CURRENT INVESTMENTS – EQUITY PORTFOLIO
Group Investments |
| Continuing Investments | ||
|
| Unaudited | Unaudited | Audited |
|
| 31 July 2026 | 31 July 2025 | 31 January 2026 |
|
| £’000 | £’000 | £’000 |
At valuation |
|
|
|
|
At 1 February |
| 273,766 | 224,095 | 224,095 |
Additions |
| 9,802 | 19,727 | 37,882 |
Disposals |
| (9,967) | (3,200) | (20,861) |
Unrealised gains in this period |
| 22,904 | 30,828 | 32,650 |
|
|
|
|
|
At period end |
| 296,505 | 271,450 | 273,766 |
|
|
|
|
|
At cost |
|
|
|
|
At 1 February |
| 100,691 | 77,116 | 77,116 |
Additions |
| 9,802 | 19,727 | 37,882 |
Disposals |
| (9,261) | (1,945) | (6,437) |
Removal of legacy costs associated with fully impaired investments |
| - | (7,870) | (7,870) |
|
|
|
|
|
At period end |
| 101,232 | 87,028 | 100,691 |
|
|
|
|
|
Group investments by valuation
Name of company | Unaudited 31 July 2026 Fair Value | Unaudited 31 July 2025 Fair Value | Audited 31 January 2026 Fair Value |
| £’000 | £’000 | £’000 |
|
|
|
|
Pantheon Specialty Group Limited | 112,360 | 105,490 | 106,990 |
XPT Group LLC | 56,990 | 60,620 | 64,030 |
ATC Insurance Solutions PTY Limited | 44,620 | 39,210 | 37,680 |
Oneglobal Broking Holdings Limited | 13,260 | NI | 10,000 |
iO Finance Partners TopCo Limited | 10,000 | 10,000 | 10,000 |
Sodalis Capital Limited | 8,624 | NI | 5,337 |
The Fiducia MGA Company Limited | 7,380 | 6,010 | 7,380 |
Volt UW HoldCo Limited | 7,000 | - | 4,250 |
Dempsey Group Limited | 6,540 | 2,290 | 4,000 |
Agri Services Company PTY Limited | 5,060 | 3,790 | 5,060 |
LEBC Holdings Limited | 4,900 | 12,700 | 7,120 |
Autonomy Investment Partners LLC | 3,848 | NI | NI |
CEE Specialty s.r.o. | 3,490 | 3,120 | 3,230 |
Devonshire UW Topco Limited | 3,360 | 300 | 1,500 |
Sage Program Underwriters, Inc | 2,230 | 2,210 | 2,210 |
Verve Risk Services Limited | 2,050 | 670 | 860 |
Gambit Risk Finance LLC | 1,393 | NI | 1,370 |
Cameron Specialty HoldCo Limited | 1,100 | 1,100 | 1,100 |
Nine Edge Wealth Limited | 1,087 | NI | NI |
SRT & Partners Limited | 1,000 | 750 | 830 |
Asia Reinsurance Brokers Pte Limited | 210 | 290 | 110 |
XPT Producer Co LLC | 3 | NI | 3 |
Ventura Risk Partners Holdings Limited | - | NI | NI |
Salus Capital Partners Limited | - | NI | - |
Amiga Specialty Holdings Limited | S | - | 706 |
New Denison Limited | - | - | - |
Stewart Specialty Risk Underwriting Limited | - | 22,900 | S |
|
|
|
|
| 296,505 | 271,450 | 273,766 |
NI = Not invested |
|
|
|
S = Investment sold during the period |
|
|
|
Group equity additions during the period by investment | Unaudited 31 July 2026 |
| £’000 |
|
|
Pantheon Specialty Group Limited | 5,500 |
Autonomy Investment Partners LLC | 3,927 |
Sage Program Underwriters, Inc | 375 |
Ventura Risk Partners Holdings Limited1 | - |
Nine Edge Wealth Limited1 | - |
|
|
| 9,802 |
1 Equity investment made at nominal value (less than £100)
The additions relate to the following transactions in the period:
On 17 March 2026 the Group acquired a 30% cumulative preferred ordinary equity stake in Nine Edge Wealth Limited (“Nine Edge”), for a nominal consideration of £30. Nine Edge is a newly established independent financial advice (“IFA”) business led by Derek Miles, former CEO of Aspira Corporate Solutions Limited. The Group also provided Nine Edge with a loan facility of up to £5,000,000, of which £3,585,000 had been drawn down as at 31 July 2026, with a remaining undrawn facility of £1,415,000.
On 17 March 2026 the Group acquired a 25% cumulative preferred ordinary equity stake in Ventura Risk Partners Holdings Limited (“Ventura”), for a nominal consideration of £49. Ventura is a newly established insurance broker focused on placing energy risks into the Lloyd’s and wider London insurance markets. The Group also provided Ventura with a loan facility of up to £2,000,000, of which £400,000 had been drawn down as at 31 July 2026, with a remaining undrawn facility of £1,600,000.
On 1 April 2026 the Group acquired a further 2% cumulative preferred ordinary equity stake in Pantheon Specialty Group Limited for consideration of £5,500,000, from members of its management team. The investment increased the Group’s equity holding from 39% as at 31 January 2026 to 41% at 31 July 2026.
On 24 June 2026 the Group acquired a 17.86% preferred equity stake in Autonomy Investment Partners LLC (“Autonomy”), through its wholly owned subsidiary B.P. Marsh (North America) Limited, for consideration of USD 5,178,628 (£3,927,547). Autonomy is a newly formed US investment vehicle, established in partnership with the senior management team of XPT Group LLC (“XPT”) and BharCap Partners LLC, a Connecticut-based private equity firm, which will make minority investments in independent US insurance distribution businesses seeking growth capital, while allowing founders and management teams to retain operational control. The Group has committed up to USD 25,000,000 of equity funding to Autonomy, of which USD 19,821,372 (£14,728,319) remained uncalled as at 31 July 2026. Any further drawdown requires the separate approval of the Group.
On 25 June 2026 the Group acquired a further 7% preferred equity stake in Sage Program Underwriters, Inc. (“Sage”), through its wholly owned subsidiary B.P. Marsh (North America) Limited, for consideration of USD 500,000 (£374,697). The investment increased the Group’s equity holding from 30% as at 31 January 2026 to 37% as at 31 July 2026. The transaction includes a performance-based ratchet whereby, if Sage achieves agreed EBITDA growth targets, a proportion of the shares acquired will be transferred to Sage’s management, reducing the additional stake acquired by the Group from 7% to 5%.
Refer to Note 7 for details of the disposals made by the Group during the period.
6. CASH AND CASH EQUIVALENTS
Group |
| Unaudited |
| Unaudited |
| Audited |
|
| 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 |
|
| £'000 |
| £'000 |
| £'000 |
|
|
|
|
|
|
|
Cash and cash equivalents comprise: |
|
|
|
|
|
|
|
|
|
|
|
|
|
Treasury portfolio |
|
26,636 |
|
42,716 |
|
36,085 |
Cash and bank balances |
| 10,786 |
| 9,868 |
| 13,395 |
|
| 37,422 |
| 52,584 |
| 49,480 |
|
|
|
|
|
|
|
Treasury portfolio |
|
|
|
|
|
|
|
|
|
|
|
|
|
At valuation |
|
|
|
|
|
|
|
|
|
|
|
|
|
Market value at 1 February |
| 36,085 |
| 51,693 |
| 51,693 |
Additions at cost |
| 11,500 |
| - |
| 35,795 |
Disposals |
| (21,400) |
| (10,000) |
| (52,995) |
Change in value in the period |
| 451 |
| 1,023 |
| 1,592 |
Market value at period end |
|
26,636 |
|
42,716 |
|
36,085 |
|
|
|
|
|
|
|
The treasury portfolio comprises investment funds managed and valued by the Group's investment managers, GAM London Limited, Rathbone Investment Management Limited and Rothschild & Co Wealth Management UK Limited.
As at 31 July 2026 all amounts held in the funds were non-risk interest bearing deposits (as at 31 July 2025 and 31 January 2026 all amounts held within the funds were non-risk interest bearing deposits).
Investment management costs of £18,634 (6 months to 31 July 2025: £41,771 and 12 months to 31 January 2026: £75,921) were charged to the Consolidated Statement of Comprehensive Income during the period.
7. REALISED GAINS / (LOSSES) ON DISPOSAL OF EQUITY INVESTMENTS
Group |
| Unaudited |
| Unaudited |
| Audited |
|
| 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 |
|
| £'000 |
| £'000 |
| £'000 |
|
|
|
|
|
|
|
Net realised gains on disposal of investments |
| 1,099 |
| 464 |
| 19,651 |
|
| 1,099 |
| 464 |
| 19,651 |
|
|
|
|
|
|
|
The realised gains / (losses) on disposal of investments comprise: |
|
|
|
|
|
|
|
|
|
|
|
|
|
Stewart Specialty Risk Underwriting Limited |
| 739 |
| - |
| 14,382 |
LEBC Holdings Limited |
| 287 |
| - |
| 1,220 |
Paladin Holdings Limited |
| 73 |
| 537 |
| 4,122 |
Sterling Insurance PTY Limited |
| - |
| (73) |
| (73) |
|
| 1,099 |
| 464 |
| 19,651 |
|
|
|
|
|
|
|
The realised gains and losses on disposal of equity investments arising during the period are as follows:
£738,584 of the net gain relates to the sale of the Group’s investment in Stewart Specialty Risk Underwriting Limited (“SSRU”) to Ryan Specialty, LLC, which completed in December 2025. On 14 April 2026 the Group received further consideration of £738,584, representing performance related deferred contingent consideration due to the Group based upon SSRU’s performance in respect of its 2025 financial year, which has been recognised as a realised gain in the period. This brings the total consideration received by the Group to £28,291,020 as at 31 July 2026, representing an overall gain of £28,291,001 above the net cost of investment.
£287,106 of the net gain relates to the receipt of a further distribution from LEBC Holdings Limited (“LEBC”) following LEBC’s receipt (in June 2026) of the second tranche of deferred contingent consideration due over a three year earn-out period in respect of the sale of 100% of Aspira Corporate Solutions Limited, a wholly-owned subsidiary of LEBC, to Titan Wealth Holdings Limited which completed in April 2024. On 8 June 2026 the Group received a distribution of £5,140,407 in respect of its pro rata proportion of the deferred contingent consideration, of which £362,082 was allocated against preferred dividends due to the Group, resulting in net proceeds of £4,778,325. Consistent with the treatment of the first tranche, the Group has recognised the receipt as a partial disposal and written off a proportionate amount of the Group’s original cost of investment in LEBC against the net proceeds received, resulting in the gain of £287,106. The final tranche of deferred contingent consideration is expected to be received by the Group in 2027.
£72,662 of the net gain relates to the Group’s deferred contingent consideration debtor balance held within the Consolidated Statement of Financial Position in relation to the sale of its investment in Paladin Holdings Limited (“Paladin”) in March 2024. The carrying value of the deferred contingent consideration as at 31 January 2026 was £9,491,235. During the period the Group received the second tranche of deferred contingent consideration due in respect of Paladin’s 2025 financial year, amounting to £9,563,897, resulting in the realised gain of £72,662.
£299 of the net gain relates to the disposal of the Group’s entire 39.24% equity holding in Amiga Specialty Holdings Limited (“Amiga”), which completed on 17 March 2026. Under the terms of the transaction Sodalis Capital Limited (“Sodalis”), an investee company of the Group, acquired 100% of Amiga. The Group received initial cash consideration of £706,250, which was in line with the Group’s carrying value of Amiga as at 31 January 2026, resulting in a realised gain of £299. The Group also received full repayment of its outstanding loans to Amiga of £1,825,000. The sellers, including the Group, may receive deferred consideration contingent on Amiga’s Adjusted EBITDA performance for the financial years ending 31 December 2027 and 31 December 2028.
The disposal of Amiga resulted in a net release of previously unrealised gains to Retained Earnings from the Fair Value Reserve of £705,951.
8. SHARE CAPITAL
| Unaudited | Unaudited | Audited |
| 31 July2026 | 31 July2025 | 31 January2026 |
Allotted, called up and fully paid |
|
|
|
Number of Ordinary shares of 10p each | 37,100,000 | 37,100,000 | 37,100,000 |
|
|
|
|
| £’000 | £’000 | £’000 |
|
|
|
|
Ordinary shares of 10p each | 3,710 | 3,710 | 3,710 |
|
|
|
|
During the period the Company paid a total of £1,218,812, including commission, in order to repurchase 181,000 ordinary shares at an average price of 671 pence per share (6 months to 31 July 2025: the Company paid a total of £1,022,887, including commission, in order to repurchase 145,000 ordinary shares at an average price of 703 pence per share and 12 months to 31 January 2026: the Company paid a total of £6,912,286, including commission, in order to repurchase 1,046,814 ordinary shares at an average price of 659 pence per share).
Ordinary shares held by the Company in Treasury
Movement of ordinary shares held in Treasury: | Unaudited | Unaudited | Audited |
| 31 July2026 | 31 July2025 | 31 January2026 |
| Number | Number | Number |
|
|
|
|
Opening total ordinary shares held in Treasury | 1,055,000 | 23,872 | 23,872 |
|
|
|
|
Ordinary shares repurchased into Treasury during the period | 181,000 | 145,000 | 1,046,814 |
|
|
|
|
Ordinary shares transferred to the B.P. Marsh SIP Trust during the period | (16,512) | (15,686) | (15,686) |
|
|
|
|
|
|
|
|
Total ordinary shares held in Treasury at period end | 1,219,488 | 153,186 | 1,055,000 |
|
|
|
|
The Treasury shares do not have voting or dividend rights and have therefore been excluded for the purposes of calculating Earnings per share and Net Asset Value per share.
The repurchase of the ordinary shares is borne from the Group’s commitment to reduce share price discount to Net Asset Value.
9. LOAN AND EQUITY COMMITMENTS
Loan commitments
At 31 July 2026, the Group had undrawn loan facility commitments to various portfolio companies totalling £9,186,304 (31 July 2025: £11,868,228; 31 January 2026: £15,017,682), of which £8,274,846 relates to new or extended facilities granted in the period. The commitment as at 31 July 2026 comprises £3,500,000 re Oneglobal Broking Holdings Limited, £1,600,000 re Ventura Risk Partners Holdings Limited, £1,415,000 re Nine Edge Wealth Limited, £1,000,000 re Salus Capital Partners Limited, £574,083 (AUD 1,100,000) re Agri Services Company PTY Limited, £500,000 re Volt UW HoldCo Limited, £300,000 re Cameron Specialty HoldCo Limited, £185,763 (USD 250,000) re XPT Producer Co LLC and £111,458 (USD 150,000) re Sage Program Underwriters, Inc.
Equity commitments
On 26 November 2024 the Group entered into a Capital Call Agreement in which it has agreed to invest, in certain circumstances, up to USD 5,000,000 in additional cash capital in the form of preferred equity in XPT Group LLC. As at 31 July 2026 XPT had not issued any Capital Call Notices.
On 24 June 2026 the Group committed up to USD 25,000,000 of equity funding to Autonomy Investment Partners LLC, of which USD 19,821,372 (£14,728,319) remained uncalled as at 31 July 2026. Any further drawdown requires the separate approval of the Group.
10. DEFERRED TAX
Group |
| Unaudited |
| Unaudited |
| Audited |
|
| 31 July 2026 |
| 31 July 2025 |
| 31 January 2026 |
|
| £'000 |
| £'000 |
| £'000 |
|
|
|
|
|
|
|
At 1 February |
| 12,596 |
| 11,847 |
| 11,847 |
Tax movement relating to investment revaluation for the period |
| (816) |
| 492 |
| 749 |
|
|
|
|
|
|
|
At period end |
|
11,780 |
|
12,339 |
|
12,596 |
Having assessed the current US portfolio, the directors anticipate that there is a requirement to provide for deferred tax in respect of the unrealised gains on investments under the current requirements of UK-adopted international accounting standards as the US LLC investments currently show a net gain. As such, a provision of £11,780,000 has been made as at 31 July 2026 (Interim 6 months to 31 July 2025: £12,339,000 and full year to 31 January 2026: £12,596,000).
The deferred tax provision of £11,780,000 as at 31 July 2026 has been calculated based upon an assessment of the US tax liability arising from the valuations of the Group’s holdings within US LLCs at 31 July 2026, using the US Federal rate of 21% together with US State Tax rates prevailing in the states where the Group’s US LLCs operate, which range between 0% and 10%. Adjustments were then made based upon available allowances and taxable losses. Given the complexity, the Group utilised the services of a specialist US tax advisory firm.
11. SHARE-BASED PAYMENT ARRANGEMENTS
Joint Share Ownership Plan
During the year to 31 January 2019, B.P. Marsh & Partners Plc entered into joint share ownership agreements (“JSOAs”) with certain employees and directors.
As at 31 July 2026 there were 761,499 shares (as at 31 July 2025 and 31 January 2026: 761,499 shares) held within the Employee Benefit Trust, of which 236,259 shares were unallocated. The Employee Benefit Trust remains the owner of these unallocated shares which have no dividend or voting rights.
During the period £80,000 was received from the Employee Benefit Trust in respect of the £4,106,259 receivable by the Company (6 months to 31 July 2025 and 12 months to 31 January 2026: no amounts were received). As at 31 July 2026 the balance due to the Company was £1,900,000 (as at 31 July 2025 and 31 January 2026: balance due was £1,980,000). As such, provided that the remaining shares are eventually sold from the Employee Benefit Trust for at least 249.5p per share on average, the Company will receive this balance in full.
Share Incentive Plan
During the year to 31 January 2017 the Group established an HMRC approved Share Incentive Plan (“SIP”).
On 20 April 2026, a total of 12 eligible employees (including 3 executive directors of the Company) applied for the 26-27 SIP and were each granted 551 ordinary shares (“26-27 Free Shares”), representing approximately £3,600 at the price of issue.
Additionally, on the same date, all eligible employees were also invited to take up the opportunity to acquire up to £1,800 worth of ordinary shares (“Partnership Shares”). For every Partnership Share that an employee acquired, the SIP Trust offered two ordinary shares in the Company (“Matching Shares”) up to a total of £3,600 worth of shares. All 12 eligible employees (including 3 executive directors of the Company) took up the offer and acquired the full £1,800 worth of Partnership Shares (275 ordinary shares) and were therefore awarded 550 Matching Shares.
The 26-27 Free and Matching Shares are subject to a 1 year forfeiture period.
A total of 16,512 (6 months to 31 July 2025 and also 12 months to 31 January 2026: 15,686) Free, Matching and Partnership Shares were granted to the 12 (6 months to 31 July 2025 and also 12 months to 31 January 2026: 11) eligible employees during the period, including 4,128 (6 months to 31 July 2025 and also 12 months to 31 January 2026: 4,278) granted to 3 (6 months to 31 July 2025 and also 12 months to 31 January 2026: 3) executive directors of the Company.
As at 31 July 2026, and after adjusting for a total of 107,527 ordinary shares withdrawn from the SIP Trust by employees on departure and 11,318 ordinary shares forfeited on departure (since inception), a total of 259,309 (as at 31 July 2025 and 31 January 2026: 244,223) Free, Matching and Partnership Shares had been granted to 12 currently eligible employees under the SIP, including 110,193 (as at 31 July 2025 and 31 January 2026: 106,065) granted to 3 executive directors of the Company.
£41,375 of the IFRS 2 charges (6 months to 31 July 2025: £39,566 and 12 months to 31 January 2026: £79,787) associated with the award of the SIP shares to the 12 (6 months to 31 July 2025 and also 12 months to 31 January 2026: 11) eligible directors and employees of the Company have been recognised in the Consolidated Statement of Comprehensive Income as employment expenses.
The results of the SIP Trust have been fully consolidated within these financial statements on the basis that the SIP Trust is effectively controlled by the Company.
Share Option Plan
On 6 September 2023 the Group established a new employee Share Option Plan (“SOP”).
On 17 October 2023 Share Options (“Options”) over 1,682,500 ordinary shares of 10p each in the Company, in aggregate, were granted to 12 employees, including 3 executive directors of the Company.
The total number of Options available for allocation amounted to 1,685,970, which represented 4.5% of the Company’s total ordinary shares in issue at the time the SOP was adopted.
During the year to 31 January 2026, and as announced on 27 March 2025, 490,000 Options were granted following the lapse of 490,000 Options previously granted in October 2023 due to departing employees, 200,000 of which had previously been granted to a former executive director (as announced on 15 November 2023). These Options were reallocated to the 11 currently eligible employees under the scheme, including 3 executive directors of the Company.
Following the reallocation, the total number of Options granted to the 11 eligible employees, including 3 executive directors of the Company, amounted to 1,685,000. 970 Options remained unallocated as at 31 July 2026.
The Group has exceeded the growth performance criteria such that 100% of the options have vested with 50% exercisable on 6 September 2026 and 50% exercisable on 6 September 2027, assuming the option holder remains an employee as at the exercise date.
£2,558,373 of the IFRS 2 charges (6 months to 31 July 2025: £152,102 and 12 months to 31 January 2026: £306,129) associated with the grant of the SOP options to 11 (6 months to 31 July 2025 and 12 months to 31 January 2026: 11) eligible directors and employees of the Company has been recognised in the Consolidated Statement of Comprehensive Income as employment expenses.
The increase in the IFRS 2 charge for the period compared with the prior periods arises because the 490,000 Options reallocated in March 2025 have been treated as a new grant, measured at their fair value at the date of reallocation. In the year ended 31 January 2026 the reallocated Options were accounted for as a continuation of the original grant made in October 2023. The charge for the period therefore includes a cumulative adjustment of £1,504,856 in respect of the period from the date of reallocation to 31 January 2026, which was not considered material to the financial statements for the year ended 31 January 2026. The ongoing charge is also higher than in prior periods, as the reallocated Options are measured at their fair value as at March 2025, reflecting the higher share price at that date compared with the original grant in October 2023. The Group has also recognised an employer’s National Insurance charge of £1,366,516 in the period in respect of the Options, which includes £1,055,092 relating to the period from the date of reallocation to 31 January 2026. Both the IFRS 2 charge and the associated employer’s National Insurance are included within ‘Share-based payment costs and related Employer’s NI’ in Note 3.
The diluted earnings per share and net asset value per share include the 1,685,000 options over ordinary shares granted as part of the Company’s SOP as these were dilutive for the Group as at 31 July 2026 based upon the performance conditions attached to the options (Note 4).
Since the period end, on 14 September 2026 and following the first exercise date of 6 September 2026, 835,249 Options granted under the Company’s Share Option Plan were exercised at an exercise price of 10p per share, including 430,000 Options exercised by the 3 executive directors of the Company. The exercise was satisfied by the transfer of 835,249 ordinary shares held in Treasury and no new ordinary shares were issued.
On the same day, the employees sold 396,052 of the ordinary shares received in order to satisfy their tax liabilities and other costs arising on exercise. These ordinary shares were repurchased by the Company into Treasury at 664 pence per share, outside of the Company’s Share Buyback Programme announced on 15 July 2026, following which the Company held 875,291 ordinary shares in Treasury.
-Ends-
Related Shares:
B.p Marsh