29th Oct 2026 07:00
THE INFORMATION CONTAINED IN THIS ANNOUNCEMENT IS RESTRICTED AND IS NOT FOR PUBLICATION, RELEASE OR DISTRIBUTION IN THE UNITED STATES OF AMERICA, ANY MEMBER STATE OF THE EUROPEAN ECONOMIC AREA, CANADA, AUSTRALIA, JAPAN OR THE REPUBLIC OF SOUTH AFRICA.
29 October 2026
ALTERNATIVE INCOME REIT PLC
(the "Company" or the "Group")
Annual Report and Financial Statements for the year ended 30 June 2026 and Notice of AGM
The Board of Directors of Alternative Income REIT PLC (ticker: AIRE), the owner of a diversified portfolio of UK commercial property assets predominantly let on long leases with index-linked reviews, is pleased to announce its annual report and financial statements for the year ended 30 June 2026.
Financial Highlights
At 30 June
| 2026 | 2025 | Change |
Net Asset Value (‘NAV’) | £67.0 million | £67.3 million | -0.4% |
NAV per share | 83.27p | 83.64p | -0.4% |
Share price | 69.20p | 74.00p | -6.5% |
Share price discount to NAV A | 16.9% | 11.5% | 5.4% |
Investment property fair value (based on external valuation) | £103.1 million | £107.4 million | -4.0% |
Loan to gross asset value (‘GAV’) A | 34.4% | 36.9% | -2.4% |
Loan facility | £36.6 million | £41.0 million | -10.7% |
For the year ended 30 June
| 2026 | 2025 | Change |
Dividends per share | 5.60p | 6.20p | -9.7% |
Earnings per share (‘EPS’) | 5.39p | 9.02p | -40.2% |
EPRA EPS A | 6.34p | 6.57p | -3.5% |
Operating profit B | £6.7 million | £6.7 million | - |
Dividend cover A | 99.8% | 108.4% | -8.6% |
Share price total return A | 1.3% | 21.6% | -20.3% |
Gross passing rental income | £8.0 million | £8.1 million | -1.2% |
Adjusted EPS A | 5.59p | 6.72p | -16.8% |
Profit before tax | £4.3 million | £7.3 million | -41.4% |
Dividend yield A | 8.1% | 8.4% | -0.3% |
NAV total return A | 6.4% | 11.1% | -4.7% |
Ongoing charges A | 1.52% | 1.57% | -5bps |
A Alternative Performance Measure, please see the Annual Report for further details.
B including gain on sale of investment property but excluding fair value changes.
Financial Highlights
• At the year end the Group is fully invested in 19 properties having disposed one property in the year. |
• The net asset value (‘NAV’) reduced by 0.4% from 83.64 pence per share (‘pps’) to 83.27pps, mainly due to the expected increase in finance costs but also due to increased corporate costs due to corporate transaction activity and the reduction in property values. |
• The dividend for the year of 5.6pps is in line with the previous Board’s target annual dividend, and is a 9.7% decrease on prior year’s dividend of 6.2pps. The resetting of the dividend was due to increase in financing costs of the new long-term debt facilities. |
• Profit before tax of £4.3 million, equivalent to 5.39pps, reflects a decrease in the Group’s property portfolio value plus increased financing costs and exceptional corporate activity costs in the year. |
• The Group’s portfolio benefits from having a strong tenant profile, being fully let, with all rent due from its tenants collected as it falls due and with over 80% of rent reviews being index linked. |
• The Group secured new long-term facilities with HSBC UK Bank plc of £41 million, consisting of a term loan of £31 million and a £10 million revolving credit facility (‘RCF’). Both the term loan and RCF are on floating rates for a fixed term of five years with an option to extend by two years if mutually acceptable. Further details of the new facilities are contained in both the Chairman’s Statement and Note 13 to the Consolidated Financial Statements. |
• Loan to GAV of 34.4% and interest cover ratio (‘ICR’) of 422.2% give significant headroom on the lender’s loan covenants. Further details are contained in Note 13 to the Consolidated Financial Statements. |
Group Operational Overview
At the year end of 30 June 2026:
• The property portfolio had a fair value of £103.1 million across 19 properties (2025: £107.4 million across 20 properties).
• The European Public Real Estate Association (‘EPRA’) NIY A was 7.3%. (2025: 7.1%)
• 81.9% of rental income is inflation linked to the Retail Price Index or the Consumer Price Index. (2025: 92.3%)
• The property portfolio was fully let at both the current and previous year end.
• The weighted average unexpired lease term ('WAULT') was:
- 15.0 years to the earlier of break and expiry (2025: 15.6 years); and
- 16.7 years to expiry (2025: 17.2 years).
Income during the year
• Rent recognised amounted to £8.3 million. (2025: £7.9 million)
• A total of nine rent reviews took place during the year, reflecting an increase of 5.3% on the reviewed rent. The combined rental uplift of £179,000 provides an increase of 2.3% across the portfolio.
A Alternative Performance Measure, please see Annual Report for further details.
Property transactions during the year
• In October 2025, the Group’s petrol filling station in Crawley was sold for £4.5 million (gross of disposal costs).
Significant changes to leases
• In April 2026, Snap Fitness surrendered its lease of the gym in Chiswick, London, where it was paying £158,210 per annum, paying a surrender premium of £225,000 together with contributions of two months rent free and nine months capital fit-out incentive for the new tenant. Pure Gym has taken a new lease of the property, on Snap Fitness surrender, at £120,000 per annum for 15 years, with a tenant break at year 10.
Events after the reporting date
Offer for the Company by Glenstone REIT plc:
On 12 June 2026, Glenstone REIT plc (‘Glenstone’) announced a cash offer to acquire the ordinary share capital of the Company not already held by Glenstone and its concert parties for 70.0 pence per share. On 6 July 2026, Glenstone announced an increased final cash offer of 71.4 pence per share (the ‘Offer’). Following the declaration of the Company’s fourth quarterly interim dividend of 1.4 pence per share on 23 July 2026, the cash consideration payable under the Offer was adjusted to 70.0 pence per share, with eligible shareholders entitled to retain the dividend.
On 9 September 2026, Glenstone announced that the acceptance condition and all other conditions of the Offer had been satisfied or waived, and that the Offer had become unconditional. Following this announcement, the Board reconsidered its recommendation and advised shareholders to accept the Offer, taking into account the certainty of the cash consideration available and the risks associated with remaining a minority shareholder in a Glenstone-controlled company.
As at the date of publication of this Annual Report, Glenstone holds or has received valid acceptances in respect of approximately 87.08% of the Company’s issued ordinary share capital, representing 70,101,776 shares.
Should Glenstone reach the statutory compulsory acquisition threshold of 90% of the shares to which the Offer relates, it intends to exercise its rights under the Companies Act 2006 to acquire the remaining shares and subsequently re-register the Company as a private limited company.
Notice of AGM
The Company’s 2026 AGM will be held on Monday, 7 December 2026 at 10:00 am at the offices of JTC, The Scalpel 18th Floor, 52 Lime Street, London EC3M 7AF.
The Company's Annual Report and Financial Statements for the year ended 30 June 2026 and the formal Notice of the Annual General Meeting will be posted to shareholders. In accordance with UK Listing Rule 6.4.1, copies of the documents have been submitted to the UK Listing Authority and will shortly be available to view on the Company's corporate website at https://www.alternativeincomereit.com/ and for inspection from the National Storage Mechanism at: https://data.fca.org.uk/#/nsm/nationalstoragemechanism.
ENQUIRIES
Alternative Income REIT PLC Adam Smith – Chairman Robert Maybury Benjamin Green
| Via AIRE's Company Secretary, Hanway Advisory Limited:
|
|
|
Hanway Advisory Limited (AIRE's company secretary) Susan Fadil | +44 (0)20 7409 0181 |
Martley Capital Real Estate Investment Management Ltd Jane Blore | 020 4551 1240 |
|
|
|
|
|
|
The Company's LEI is 213800MPBIJS12Q88F71.
Further information on Alternative Income REIT PLC is available at https://www.alternativeincomereit.com/1
1 Neither the content of the Company's website, nor the content of any website accessible from hyperlinks on its website or any other website, is incorporated into, or forms part of, this announcement nor, unless previously published on a Regulatory Information Service, should any such content be relied upon in reaching a decision as to whether or not to acquire, continue to hold, or dispose of, securities in the Company.
NOTES
Alternative Income REIT PLC aims to generate a sustainable, secure and attractive income return for shareholders from a diversified portfolio of UK property investments, predominately in alternative and specialist sectors. The majority of the assets in the Group's portfolio are let on long leases which contain index-linked rent review provisions.
Chairman’s Statement
I am pleased to present the annual audited results of Alternative Income REIT PLC (the ‘Company’) together with its subsidiaries (the ‘Group’) for the financial year ended 30 June 2026.
Overview
A number of key changes have taken place subsequent to the financial year ended 30 June 2026, including the takeover of the Company by Glenstone REIT plc whose offer became unconditional on 9 September 2026 and led to the appointment of a new board.
From a property perspective, the year under review has been challenging, with geopolitical instability in the Gulf adding further uncertainty to the on-going global tariff disputes. Closer to home, business confidence has remained low as increasing tax burdens and persistent inflationary pressures continue to negatively influence investor sentiment and occupational demand.
Rental growth across the market has remained modest and whilst interest rates have held steady, the market expectations are that interest rates are more likely to rise, rather than fall. These factors have contributed to a further period of stagnation within the real estate sector.
From an income perspective, the Group continues to perform well in this challenging market with the portfolio demonstrating some degree of resilience. The portfolio benefits from its long-dated and high yielding leases, together with index-linked rental uplifts, providing a stable and predictable income stream.
During the year, one property transaction was completed, being the sale of the Group’s petrol filling station in Crawley for £4.5 million, a gain of £0.5 million based on its market value at the end of the previous year, with the net proceeds being used to repay £4.4 million of debt. Mainly as a result of this sale, the portfolio value has decreased by £4.24 million and at 30 June 2026 was valued at £103.11 million (2025: £107.35 million). On a like-for-like basis, making allowance for the sale of Crawley, the value of the Group’s properties decreased marginally by £240,000.
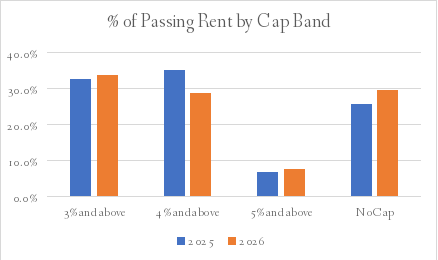
The portfolio should continue to perform relatively well during periods of higher inflation, given that 81.9% of its rental income is subject to index-linked reviews and 18.1% of rental income is not subject to any cap on rental increases. During the financial year, a total of nine rent reviews took place, generating an aggregate rental uplift of circa £179,000. This represents a 2.3% increase in contracted rental income across the Group’s portfolio and further demonstrated the defensive characteristics of the Group’s long- term strategy.
In the Chairman’s Statement last year, it was reported that the Group has secured new long- term debt facilities with HSBC UK Bank plc (‘HSBC’) for a term of five years, with an option to extend by two years if mutually acceptable to both parties.
Together with the active asset management initiatives being undertaken, the Board believes that the portfolio will continue to deliver an attractive and sustainable yield, supported by its improving rental income profile. This position is encouraging as global inflationary pressures continue to show signs of persisting. In the UK, concerns around renewed inflation continue to constrain the prospect of meaningful reductions in interest rates, thereby delaying the broader economic stimulus that lower borrowing costs would otherwise be expected to provide.
At the year end, the portfolio net initial yield has increased to 7.3% (2025: 7.1%) and a WAULT to the first break of 15.0 years and 16.7 years to expiry (30 June 2025: 15.6 and 17.2 years, respectively).
Refinancing of the Group’s Debt
The Group’s £41.0 million loan facility with Canada Life matured and was repaid on its due date of 20 October 2025.
The Group successfully refinanced its £41 million 3.19% fixed rate debt with Canada Life during the year with new long-term debt facilities with HSBC comprising a fixed term loan of £31 million and a £10 million RCF and were used to refinance the Group’s £41 million loan with Canada Life which ended on 20 October 2025.
The facilities are for a fixed term of five years from 20 October 2025, with an option to extend by two years if mutually acceptable. Whilst there is no present intention, AIRE has the right, through an accordion mechanism, to request an increase in the size of the RCF by up to a further £10 million, over the course of the facility.
Both the HSBC loan and RCF are floating rate with a margin of 1.7% per annum plus SONIA (sterling overnight index average rate). The margin represents an improvement in terms on the previous debt facilities, but total finance costs have increased as a result of the higher prevailing base rates. At 30 June 2026, the weighted average interest cost was 4.76%. The loan and the RCF are aggregated for the purposes of the debt’s financial covenants and, being based on a Loan to Value covenant which is not to exceed 60% and an Interest Cover Ratio (‘ICR’) to be greater than 160%, represent an improvement over the previous terms.
At year end, the Group had drawn down a total of £36.6 million from the facility, made up of the loan of £31 million and the RCF of £5.6 million, following the use of the proceeds from the disposal of Crawley to reduce the RCF by £4.4 million (30 June 2025: debt £41.0 million).
Following the Glenstone takeover offer being declared unconditional on 9 September 2026, HSBC issued a Reservation of Rights letter in connection with the change of control in the Group. On 28 October 2026, AIRE and HSBC entered into a waiver and amendment letter to the Facility Agreement, under which HSBC consented to the change of control and the Company’s subsequent de-listing from the London Stock Exchange, agreed to continue funding future utilisations and waived any right to require repayment as a result of the change of control.
Corporate activity and change of control
The financial year ended 30 June 2026 and the period subsequently have been marked by significant corporate activity, culminating in a change of control of the Company following Glenstone’s takeover of the Company.
In March 2026, AEW UK REIT plc (‘AEWU’) had announced that it was considering a possible all-share offer for the Company. Following discussions and due diligence, AEWU confirmed on 21 April 2026 that it would not proceed with its possible offer. AEWU subsequently announced a renewed possible all-share offer in July 2026, which was also withdrawn in August 2026 without a firm offer being made.
These approaches, together with the subsequent Glenstone Offer, resulted in the Company incurring professional advisory and other transaction-related costs which have had a one-off impact to the Company’s reported earnings for the year to 30 June 2026 and will also impact the current financial year’s earnings.
With respect to the year under review, professional costs incurred by the Company’s previous Board, principally in dealing with AEWU’s possible offer which was aborted on 21April 2026, amounted to £732,000 (0.91 pence per share).
On 12 June 2026, Glenstone announced a cash offer for the shares in the Company that it did not already own. This was followed on 6 July 2026 by an increased final cash offer of 71.4 pence per share, subsequently adjusted to 70.0 pence per share following the declaration of the Company’s fourth quarterly interim dividend of 1.4 pence per share, which eligible shareholders were entitled to retain.
On 9 September 2026, Glenstone announced that the Offer had become unconditional, following satisfaction of the acceptance condition and all other relevant conditions.
Changes to the composition of the Board followed this change of control, including the resignations of both Simon Bennett and Stephanie Eastment and the appointment of three new Glenstone directors to the Board, including my own re-appointment. I would like to acknowledge the contribution of both Simon and Stephanie whom I enjoyed working with and thank them for their stewardship of the Company over the last few years.
As at the date of publication of this Annual Report, Glenstone holds or has received valid acceptances in respect of approximately 87.08% of the Company’s issued ordinary share capital. The Offer will remain open until acceptances reach a level whereby Glenstone can effect the compulsory acquisition of the remaining shares, following which the Company will be de-listed and re-registered as a private company and 100%-owned subsidiary of Glenstone. In the meantime, the Board’s priority is to oversee an orderly transition, maintain appropriate governance and ensure that the Company’s property portfolio continues to be managed responsibly by AIRE’s current service providers.
Dividends and Earnings
During this financial year, the Company declared four interim dividends totalling 5.6 pence per share (‘pps’) (30 June 2025: 6.2pps). Historically the Board has paid dividends in four instalments each financial year. The Board does not intend to continue with this practice and, instead, will declare dividends in the future in compliance with the REIT regime’s rules.
Discount
The discount of the share price to NAV at 30 June 2026 widened to 16.9% (30 June 2025: 11.5%). The Board monitors the discount level throughout the year and has the authority to both issue and buy back shares. Although these powers have not been used to date, the Board believes these authorities are important powers for it to have available, if required, and therefore recommends that shareholders vote in favour of their continuance at the forthcoming AGM.
Board
The Board, comprising three directors, has always been deliberately kept small given the size of the Company. I had served on the Board as Glenstone’s representative since March 2021 until I resigned on 6 July 2026 when Glenstone announced its takeover offer.
I have therefore had influence and knowledge of the strategy of the Company for a considerable amount of time and deep knowledge of the portfolio.
Following my subsequent reappointment to the Board on 15 September 2026, a new Board, comprising myself, Ben Green and Rob Maybury, was appointed on 30 September 2026. My fellow directors appointed me to be Chair.
We are committed to ensuring the Company maintains appropriate levels of governance during the period and to acting in the best interests of all shareholders. Following our initial governance review, we have maintained the Company’s previous committee structure and each of the Committees comprise all members of the Board. The Audit Committee is chaired by Rob Maybury. The Management and Engagement Committee is chaired by myself.
It is Glenstone’s intention to keep its offer open and to reach a level of acceptances whereby it can exercise its rights to acquire AIRE’s remaining shares compulsorily under the Companies Act (‘Squeeze Out’) and apply to de-list the Company’s shares from the London Stock Exchange and re-register AIRE as a private company, wholly owned by Glenstone. In the event that acceptances for Glenstone’s offer do not reach the required threshold for the Squeeze Out to proceed, then the Company will appoint a new independent director to join the Board of AIRE.
AGM
The Company will hold its AGM at 10:00am on Monday 7 December 2026 at the offices of JTC, The Scalpel 18th Floor, 52 Lime Street, London EC3M 7AF.
The Board always welcomes engagement with shareholders, who should be aware that if they are unable to attend in person, they can submit questions to the Board by emailing the Company Secretary at AIRE.Cosec@jtcgroup. com or by writing to me at the Group’s registered office, namely, Alternative Income REIT PLC, The Scalpel 18th Floor, 52 Lime Street, London EC3M 7AF.
Outlook
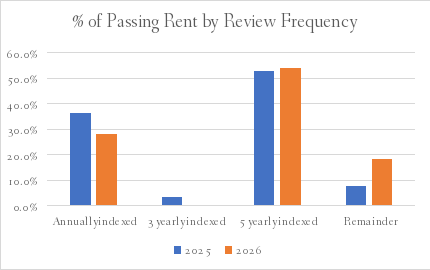
The Group’s index-linked portfolio, with its properties let on predominantly long dated and high yielding leases, has continued to perform relatively well, when compared with its peer group. In the coming financial year, approximately 41.9% of the Group’s income will be subject to rent reviews (27.9% as annual index-linked rent reviews and the remaining 14.0% being periodic three or five yearly index-linked rent reviews).
Interest rates have fallen 50 basis points since June 2025, with the Bank of England’s base rate now standing at 3.75%, providing a more supportive backdrop for property valuations.
With most of the portfolio on index-linked leases, the sustained inflationary environment has continued to drive rental income growth in real terms, providing shareholders with a natural inflation hedge. Combined with the Group’s active asset management initiatives, the Board remains confident the portfolio will continue to deliver an attractive yield underpinned by its secure and growing rental income.
As set out in the Offer Document, Glenstone now intends to proceed with the Delisting and will, accordingly, procure that the Company makes applications (i) to the Stock Exchange for the cancellation of the admission to trading of the Company’s shares on the main market for listed securities and (ii) to the FCA for the cancellation of the listing of the Company’s shares on the closed ended investment funds category of the Official List, together being the Delisting.
It is expected that the Delisting will take effect once Glenstone is able to exercise its statutory squeeze-out rights to compulsorily acquire the Company’s remaining shares held by non-assenting shareholders.
I would like to take this opportunity to thank all the Company’s advisers for their professional services and support during the financial year.
Adam Smith Chairman 28 October 2026
Business Model and Strategy
Alternative Income REIT PLC is a real estate investment trust listed on the closed-ended investment funds category of the Official List of the Financial Conduct Authority (‘FCA’) and traded on the Main Market of the London Stock Exchange. As part of its business model and strategy, the Group has maintained and intends to maintain its UK REIT status.
The Company is governed by a Board of non-executive directors (the ‘Board’) and has no employees. The Board is responsible for determining the Company’s investment objective and investment policy. Like many other REITs and investment companies, the day-to-day management and administration of the Company is outsourced by the Board to third party providers, including Martley Capital Real Estate Investment Management Limited (‘Martley Capital’) as Investment Adviser, Langham Hall Fund Management LLP as AIFM and JTC (UK) Limited as Company Secretary.
Investment Objective
The investment objective of the Group is to generate a secure and predictable income return, sustainable in real terms, whilst at least maintaining capital values, in real terms, through investment in a diversified portfolio of UK properties, predominantly within the alternative and specialist sectors.
Investment Policy
In order to achieve the investment objective, the Group invests in freehold and long leasehold properties across the whole spectrum of the UK property sector. The Group’s emphasis is on alternative and specialist property sectors in order to access the attractive value and capital preservation qualities which such sectors offer.
The Group invests in properties that can generate predictable income streams through long leases which have contractual exposure to inflation rates, focusing on properties which have the ability to deliver secure income and preserve capital value, with an attractive entry yield.
The Group will supplement this with active asset management initiatives for certain properties.
Permitted sectors include, but are not limited to the following, subject at all times to the assessment of their appeal and specific asset investment opportunities: healthcare; leisure; hotels and serviced apartments; education; automotive; car parks; residential; supported living; student accommodation; logistics; storage; communications; supermarkets (within the alternative and specialist real estate sectors). In addition, permitted sectors include: offices; shopping centres; retail and retail warehouses; and industrial (being defined as ‘Traditional’ real estate sectors), subject to the limitations on sector exposure below.
The Group is not permitted to invest in land assets, including development land which does not have a development agreement attached, agriculture or timber.
Each investment must enable the portfolio to comply with the following minimum targets at the time of investment:
a weighted average unexpired lease term (‘WAULT’) in excess of ten years;at least 75% of the gross passing rent being from leases with rent reviews linked to a commonly used measure of inflation (typically RPI or CPI);at least 50% of the gross asset value (‘GAV’) of properties being in alternative and specialist sectors; andover 90% of properties being freehold or very long leasehold (over 100 years).
Whilst each acquisition is made on a case-by-case basis, properties typically offer the following characteristics:
a value of between £2 million and £30 million;existing tenants with strong business fundamentals and profitable operations;depth of tenant/operator demand;alternative use value;current passing rent close to or below rental value; andlong-term demand drivers, including demographics, use of technology or built-for-purpose real estate.
The Group may invest in commercial properties or portfolios of commercial property assets which, in addition, include ancillary or secondary utilisations.
The Group may invest in corporate and other entities that hold property and the Group may also invest in conjunction with third-party investors.
The Group may engage in full or partial interest rate hedging or use derivatives to seek to mitigate the risk of interest rate increases as part of the Group’s portfolio management.
Investment limits
The Group will invest and manage its assets with the objective of spreading investment risk through the following:
Investment in a single property limited to 15% of GAV (measured at the time of investment).Exposure to a single tenant covenant will be limited to 15% of GAV.The Group may commit up to a maximum of 10% of its GAV (measured at the point of capital commitment) in development activities.Investment in unoccupied and non-income producing assets will, at the time of investment, not exceed 5% of Estimated Rental Value (‘ERV’).The Group will not invest in other closed-ended investment companies.
If the Group invests in derivatives for the purposes of efficient portfolio and cash management, the total notional value of the derivatives at the time of investment will not exceed, in aggregate, 20% of GAV.
Borrowings
The Group may utilise borrowings with a view to enhancing returns over the medium term. Borrowings, where utilised will be on a limited recourse basis for each investment on all or part of the total portfolio and will not exceed 40% of GAV (measured at drawdown) of each relevant investment or of the portfolio.
Dividend Policy
The Board's policy during the year under review was to pay dividends in four instalments each financial year. The Board does not intend to continue with this practice and, instead, will declare dividends in the future in compliance with the REIT regime’s rules.
Key Performance Indicators
KPI AND DEFINITION | RELEVANCE TO STRATEGY | PERFORMANCE |
Adjusted EPS1 |
| 5.59pps |
Adjusted EPS from core operational activities, as adjusted for non-cash items. A key measure of a company’s underlying operating results from its property rental business and an indication of the extent to which current dividend payments are supported by earnings. See Note 8 to the financial statements. | This reflects the Group’s ability to generate earnings from the portfolio which underpins dividends.
| For the year ended 30 June 2026 (2025: 6.72pps) |
Dividend per share2 |
| 5.60pps |
Dividends declared in relation to the period are in line with the stated dividend target as set out in the Prospectus at IPO. Having achieved the target dividend of 5.60 pence per Ordinary Share per annum, the aim is to ensure an increasing dividend in line with the Company’s Investment Objective. | The Group seeks to deliver a sustainable income stream from its portfolio, which it distributes as dividends.
| For the year ended 30 June 2026 (2025: 6.20pps) |
Net Asset Value (‘NAV’)1 per share |
| £67.04 million/ 83.27pps |
NAV is the value of an entity’s assets minus the value of its liabilities. See Note 8 to the financial statements. | Provides stakeholders with the most relevant information on the fair value of the assets and liabilities of the Group. | At 30 June 2026 (2025: £67.33 million/83.64pps) |
Leverage (Loan-to-GAV)3 |
| 34.43% |
The proportion of the Group’s assets that is funded by borrowings. | The Group utilises borrowings to enhance returns over the medium term. Borrowings will not exceed 40% of GAV (measured at drawdown). | At 30 June 2026 (2025: 36.88%) |
Net Initial Yield (‘NIY’) |
| 7.25% |
Annualised rental income based on the cash rents passing at the balance sheet date, less non-recoverable property operating expenses, divided by the market value of the property, increased with purchasers’ costs estimated by the Group’s External Valuers. | The NIY is an indicator of the ability of the Group to meet its target dividend after adjusting for the impacts of leverage and deducting operating costs.
| At 30 June 2026 (2025: 7.07%)
|
Weighted Average Unexpired Lease Term (‘WAULT’) to break and expiry |
| 15.0 years to break and 16.7 years to expiry |
The average lease term remaining to expiry across the portfolio, weighted by contracted rent. | The WAULT is a key measure of the quality of the portfolio. Long leases underpin the security of our future income.
| At 30 June 2026 (2025: 15.6 years to break and 17.2 years to expiry) |
1 The reconciliation of this APM is set out in Note 8 of the Notes to the Consolidated Financial Statements. 2 The reconciliation of this APM is set out in Note 9 of the Notes to the Consolidated Financial Statements. 3 The reconciliation of this APM is set out in the Alternative Performance Measures Calculations section following the Notes to the Consolidated Financial Statements.
| ||
EPRA Performance Measures
The EPRA performance measures of the Group follow. All are Alternative Performance Measures.
MEASURE AND DEFINITION | PURPOSE | PERFORMANCE |
EPRA Net Tangible Assets1 |
| £67.04 million/83.27pps |
The EPRA NTA deducts the break cost of bank borrowings from the EPRA NAV. | A measure that assumes entities buy and sell assets, thereby crystallising certain levels of deferred tax liability. The Group has UK REIT status and as such no deferred tax is required to be recognised in the accounts.
|
At 30 June 2026 (2025: £67.33 million/83.64pps)
|
EPRA Net Reinstatement Value1 |
| £73.74 million/91.60pps |
The EPRA NRV adds back the purchasers’ costs deducted from the EPRA NAV and deducts the break cost of bank borrowings. | A measure that highlights the value of net assets on a long-term basis.
| At 30 June 2026 (2025: £74.31 million/92.30pps) |
EPRA Net Disposal Value1 |
| £67.04 million/83.27pps |
The EPRA NDV deducts the break cost of bank borrowings from the EPRA NAV. | A measure that shows the shareholder value if assets and liabilities are not held until maturity. | At 30 June 2026 (2025: £67.33 million/83.64pps) |
EPRA LTV2 |
| 32.90% |
Debt (net of cash balances) divided by the market value of properties (including net receivables). | A key (shareholder-gearing) metric to determine the percentage of debt comparing to the appraised value of the properties. | At 30 June 2026 (2025: 34.82%) |
EPRA Earnings/EPS1 |
| £5.11 million/6.34pps |
Earnings from operational activities. | A key measure of a company’s underlying operating results and an indication of the extent to which current dividend payments are supported by earnings. | For the year ended 30 June 2026 (2025: £5.29 million/6.57pps) |
EPRA NIY2 - unaudited |
| 7.25% |
Annualised rental income based on the cash rents passing at the balance sheet date, less non-recoverable property operating expenses, divided by the market value of the property, increased with (estimated) purchasers’ costs. | A comparable measure for portfolio valuations. This measure should make it easier for investors to judge themselves, how the valuation of two portfolios compare. | At 30 June 2026 (2025: 7.07%) |
EPRA ‘Topped-up’ NIY2 - unaudited |
| 7.25% |
This measure incorporates an adjustment to the EPRA NIY in respect of the expiration of rent-free periods (or other unexpired lease incentives such as discounted rent periods and step rents).
|
A comparable measure for portfolio valuations. This measure should make it easier for investors to judge themselves, how the valuation of two portfolios compare.
|
At 30 June 2026 (2025: 7.25%)
|
EPRA Vacancy2 - unaudited |
| 0.00% |
Estimated Rental Value (‘ERV’) of vacant space divided by ERV of the whole portfolio. | A ’pure’ percentage measure of investment property space that is vacant, based on ERV. | At 30 June 2026 (2025: 0.00%)
|
EPRA Cost Ratio2 - unaudited |
| 23.07% |
Administrative and operating costs (including and excluding costs of direct vacancy) divided by gross rental income. | A key measure to enable meaningful measurement of the changes in a company’s operating costs. | For the year ended 30 June 2026 15.14% |
1 The reconciliation of this APM is set out in Note 8 of the Notes to the Consolidated Financial Statements.
2 The reconciliation of this APM is set out in the EPRA Performance Measures Calculations section following the Notes to the Consolidated Financial Statements.
Investment Adviser’s Report
Market Outlook
UK Economic Outlook
The UK economy maintained stronger-than-expected momentum through the second quarter of 2026. GDP grew by 0.6% in Q1 and monthly output expanded by 0.1% in May, reversing April’s 0.1% decline. This left GDP 0.7% higher in the three months to May than in the preceding three-month period, marking a sixth consecutive period of underlying expansion A. Annual GDP growth strengthened to 1.3% in May, its fastest pace since mid-2025, although the Bank of England continues to caution that the effects of the Middle East energy shock may weigh on activity in the second half of the year B. The UK’s relative performance has improved, with Q1 growth outpacing both the Eurozone (-0.2%) and the United States (0.4%), leaving the UK 6.0% above its Q4 2019 level compared with 6.6% for the Eurozone and 15.1% for the US C.
Labour market conditions softened further but remained broadly resilient. The unemployment rate was 4.9% in the three months to May 2026, unchanged from the previous quarter but 0.2 percentage points higher than a year earlier.
Unemployment claimants increased to 1.69 million in June and youth unemployment climbing to 14.7% D. Payrolled employment continued to edge lower and vacancies remained on a downward trend, consistent with ongoing hiring caution among employers. Annual regular pay growth held at 3.4% in the three months to May, its weakest rate since 2020 and further evidence that wage pressures are easing E. The British Chambers of Commerce continues to expect a gradual loosening of labour market conditions, forecasting unemployment to average 5.2% in 2026 and business investment to contract by 2.2% F.
Inflationary pressures eased during Q2 as energy-related price pressures moderated. CPI inflation fell to 2.6% in June 2026 from 2.8% in May G; with lower motor fuel prices making the largest downward contribution to the decline following the US-Iran ceasefire and the associated de-escalation in Middle East energy risk. Services inflation also eased to 3.6% from 3.7%, although underlying domestic price pressures remain above levels consistent with the Bank of England’s 2% target. The Bank’s June Monetary Policy Report revised down its near-term inflation outlook, reflecting lower energy prices and a more limited pass-through from the earlier Middle East energy shock H.
Against this backdrop, the Monetary Policy Committee left Bank Rate unchanged at 3.75% in both June and July. The June decision was passed by a 7-2 majority, with two members voting for a 25 basis point increase, – the two dissenters favouring a 0.25 percentage point increase to 4% – as falling global energy prices were weighed against services inflation of 3.7% I. By the end of July, markets had largely abandoned expectations of further policy easing during 2026, reflecting concerns over persistent services inflation and the risk of renewed energy price pressures J. Since then, markets have moved to price a high probability of a rate increase in November, and 10-year gilt yields have risen above 5.4%, their highest level in nearly two decadesK . This marks a sharp reversal from pre-conflict pricing, which had implied additional easing through 2026.
Survey evidence paints a mixed but gradually improving picture. ONS business surveys suggest that turnover expectations have stabilised after weakening earlier in the year, while consumer confidence has recovered noticeably from its spring lows. The July ONS Business Insights and Conditions Survey found 14% of trading businesses expecting a turnover decrease, roughly in line with the 13% recorded in March and well down from the deterioration seen through the conflict-hit spring months L. Meanwhile, the Consumer Confidence Index rose to -13 in July, its strongest reading since early 2022, supported by easing inflation and lower fuel costs M.
Overall, while growth has remained resilient, the outlook has deteriorated since the period end. Inflation has risen to 3.1% in August N and the Bank of England expects it to exceed 4% in early 2027 O, although wage pressures continue to moderate. The labour market is also gradually loosening and business investment remains subdued. The Bank of England’s decision to hold the Bank Rate signals continued caution in the face of persistent services inflation and uncertainty over the energy outlook. The BCC continues to forecast subdued 2026 growth (0.9%), rising unemployment (5.2%) and contracting business investment, and while sentiment has improved from its spring lows it remains fragile. The result is an outlook of modest expansion rather than renewed acceleration, with the principal risks stemming from energy markets, inflation persistence and the prospect of a further rise in interest rates.
UK Real Estate Outlook
UK real estate investment totalled £51.2 billion in the 12 months to June 2026, a period characterised by an exceptionally strong end to 2025 followed by a more cautious first half of 2026. Activity peaked at £21.6 billion in Q4 2025, supported by Welltower’s £6.4 billion acquisition of the Barchester and HC-One care home portfolios, before moderating to a combined £20.7 billion across Q1 and Q2 2026 as geopolitical uncertainty and higher financing costs tempered investor activity P. Despite softer volumes, large-scale transactions remained a defining feature of the market, including Unite Group’s £723 million acquisition of Empiric Student Property and Morgan Stanley/Ridgeback’s £1.0 billion purchase of the Metra Living PRS portfolio. Overseas capital continued to play a leading role, with inflows doubling to a near four-year high of £8.3 billion in Q4 on a 116% surge in North American buying, before rotating from a six-year-high European quarter in Q1 (£2.1 billion) to a North American-led Q2 (£2.9 billion), although net overseas investment fell sharply in Q2 as elevated disposal activity reduced net purchasing to one of the lowest levels on record.
Monetary and pricing conditions became more challenging during the year. Following the Bank of England’s reduction of Bank Rate to 3.75% in December 2025, expectations for further easing were disrupted by the Middle East conflict and its impact on energy markets. CPI inflation rose to 3.3% in March 2026 before easing to 2.6% in June 2026, while the Monetary Policy Committee maintained Bank Rate at 3.75% throughout 2026, including at its July meeting. The June decision was split 7-2, with two members voting for a 25 basis point increase Q. The investment market reflected this shift in sentiment. Prime All Property yields hardened from 5.58% in Q3 2025 to 5.55% in Q4, before softening to 5.63% in Q1 2026 and 5.66% in Q2 2026 as investors reassessed interest rate and inflation risks P. As a consequence, Oxford Economics has revised its 2026 forecast for All Property capital growth to broadly flat, with total returns expected to be approximately 4.9%, compared with pre-conflict expectations of around 7.8%, although returns are still forecast to strengthen to 6-7% per annum during 2027-28 R.
The living sector remained the dominant area of the market, attracting £22.4 billion of investment, equivalent to 44% of total annual transaction volumes. Following a record £10.6 billion in Q4 2025, activity normalised during the first half of 2026, although build-to-rent and private rented sector assets continued to attract significant institutional interest and hotels recorded their strongest transaction volumes for two years P. Industrial and retail markets experienced greater volatility, both benefiting from large transactions in late 2025 before weaker activity in early 2026. Nevertheless, performance remained resilient: MSCI data indicate retail delivered total returns of approximately 3.7% during the first half of 2026, ahead of industrial at 2.6%, highlighting the continued importance of income growth and constrained supply in supporting values S.
Within listed real estate, UK REIT discounts continued to narrow. By June 2026, the eight companies in the AIC UK Commercial Property sector traded at an average 20.7% discount to NAV, compared with approximately 28% at the start of the year, although still above the long-term average of around 17% T. Against this backdrop, AIRE continued to demonstrate operational resilience. The Company achieved its targeted annual dividend of at least 5.6p per share for FY2026, reported a NAV of 83.3p per share, and generated a 1.5% NAV total return during the quarter to June 2026. Performance was supported by a fully let portfolio, 100% rent collection, 82% index-linked leases and a 7.2% net initial yield U. The share price discount widened to 16.9%, reflecting broader sector sentiment rather than portfolio-specific factors U. Long-term capital market assumptions published by J.P. Morgan Asset Management continue to suggest that core real assets can generate high single-digit annualised returns over the coming decade, supporting the investment case for income-focused strategies V.
UK real estate enters the second half of 2026 against a backdrop of resilient occupier fundamentals but increased macroeconomic uncertainty. Transaction volumes remain heavily dependent on a relatively small number of large transactions, while vendors continue to resist price adjustments in the absence of financial pressure P. With expectations of near-term yield compression largely removed, income growth has become the principal driver of returns. Oxford Economics forecasts retail to deliver annual total returns of approximately 7.5% to 2030, ahead of 6.4% for the All Property market, reflecting attractive starting yields and improving occupational fundamentals R. At the same time, constrained supply, continued rental growth, tightening sustainability requirements and the UK’s enduring appeal to international capital should provide support to values over the medium term, notwithstanding ongoing geopolitical and inflation-related risks.
Sources: A |
ONS (2026), GDP monthly estimate, UK: May 2026; |
B | Bank of England (2026), Monetary Policy Report – April 2026; |
C | House of Commons Library (2026), GDP international comparisons: Economic indicators; |
D | ONS (2026), Labour market overview, UK: July 2026; |
E | ONS (2026), Average weekly earnings in Great Britain: May 2026; |
F | British Chambers of Commerce (2026), Quarterly Economic Forecast Q2 2026; |
G | ONS (2026), Consumer price inflation, UK: June 2026; |
H | Bank of England (2026), Monetary Policy Report – June 2026; |
I | Bank of England (2026), Monetary Policy Summary and Minutes – June 2026; |
J | Reuters poll (2026), cited in BritSavvy, Bank of England July 2026 rate decision; |
K | Trading Economics (2026), UK Gilt Yields Rise as Energy Prices Lift Rate-Hike Bets, 28 September 2026; |
L | ONS (2026), Business Insights and Conditions Survey (March and June/July 2026 waves); |
M | NIQ/GfK (2026), UK Consumer Confidence Index – March-July 2026; |
N | ONS (2026), Consumer price inflation, UK: August 2026; |
O | Bank of England (2026), Monetary Policy Summary and Minutes – September 2026; |
P | LSH Research (2026), UKIT Q3 2025, UKIT Q4 2025, UKIT Q1 2026, UKIT Q2 2026 – UK Investment Transactions; |
Q | Bank of England (2025/2026), Monetary Policy Summary and Minutes, December 2025 – June 2026; |
R | LSH Research/Oxford Economics (2026), UKIT Q2 2026 All Property Total Return Forecast; |
S | CBRE (2026), UK All Property Q1/Q2 2026 press releases; |
T | The AIC (2026), AEW UK REIT bid situation update, 29 June 2026; |
U | Alternative Income REIT PLC (2026), NAV, Dividend Declaration & Portfolio Valuation updates, FY2026; |
V | J.P. Morgan Asset Management (2026), Guide to the Markets – UK. |
Portfolio Activity During the Year
The following transactions happened during the year:
The sale of the petrol filling station in Crawley, let to Rontec Roadside Retail Limited, completed in October 2025 for £4.5 million (gross of disposal costs). The price reflects 17.8% premium on original purchase price and £500,000 premium on the property’s book value at 30 June 2025 and a net exit yield of 6.3%. The proceeds were used to reduce the HSBC RCF.The following asset management initiatives were undertaken during the year:
In April 2026 Snap Fitness has surrendered its lease of the gym in Chiswick, London paying a surrender premium of £225,000 together with contributions of two months rent free and nine months capital fit out incentive for the new tenant. Simultaneously Pure Gym has taken a new lease at £120,000 per annum for 15 years with a tenant’s break at year 10.Rent Reviews
A total of nine rent reviews took place (excluding Crawley) during the year with a combined uplift of £179,016 with an average increase in contracted rent of 5.1%. The portfolio showed an increase of 2.3% on a like-for-like basis.
Negotiations are in progress in respect of lease regears and renewals with many tenants including Meridian Steel, B&M, Pets at Home and BGEN. The Company remains supportive of its occupiers to work together to improve the environmental sustainability of the portfolio.
NAV Movements
For the year ended 30 June | 2026 | 2025 | ||
| Penceper share | £m | Penceper share | £m |
NAV at beginning of year | 83.64 | 67.33 | 80.90 | 65.12 |
Change in fair value of investment property | (0.43) | (0.35) | 2.45 | 1.97 |
Income earned for the year | 11.11 | 8.94 | 10.64 | 8.57 |
Gain on disposal of property | 0.39 | 0.31 | – | – |
Finance costs for the year | (2.51) | (2.02) | (1.78) | (1.44) |
Expenses for the year 2026 | (2.26) | (1.81) | (2.29) | (1.84) |
Exceptional corporate activity costs* | (0.92) | (0.73) | – | – |
Dividends paid during the year | (5.75) | (4.63) | (6.28) | (5.05) |
NAV at the end of the year | 83.27 | 67.04 | 83.64 | 67.33 |
* Exceptional corporate activity costs arose from professional advisory, legal, corporate finance and other costs in connection with evaluating and responding to a number of unsolicited takeover and corporate proposals.
Valuation
At 30 June 2026 the Group owned 19 property assets (2025: 20) and the portfolio was valued at £103.11 million (2025: £107.35 million). During the year the Group successfully sold the petrol filling station in Crawley, therefore on a like-for-like basis, the value of the Group’s properties decreased marginally to £103.11 million from £103.35 million.
Summary by Sector
at 30 June 2026
Sector | Number of Properties | Valuation(£m) | MarketValue(%) | Occupancy by ERV(%) | WAULTto break(years) | Gross Passing Rental Income(£m) | ERV (£m) | ERV 1(%) |
Industrial Warehouse | 4 | 26.6 | 25.8 | 100.0 | 21.5 | 1.9 | 2.0 | 27.4 |
Healthcare | 3 | 17.2 | 16.7 | 100.0 | 22.5 | 1.3 | 1.2 | 15.8 |
Hotel | 2 | 11.9 | 11.6 | 100.0 | 11.5 | 1.0 | 0.8 | 11.4 |
Automotive & Petroleum | 2 | 11.8 | 11.4 | 100.0 | 10.9 | 0.9 | 0.8 | 10.5 |
Residential | 1 | 10.9 | 10.5 | 100.0 | 15.1 | 0.9 | 0.8 | 11.3 |
Leisure | 3 | 10.4 | 10.1 | 100.0 | 7.9 | 0.9 | 0.8 | 10.4 |
Retail Warehouse | 1 | 5.6 | 5.4 | 100.0 | 2.8 | 0.5 | 0.4 | 5.3 |
Power Station | 1 | 4.5 | 4.4 | 100.0 | 5.7 | 0.3 | 0.3 | 4.5 |
Education | 2 | 4.2 | 4.1 | 100.0 | 15.0 | 0.3 | 0.2 | 3.4 |
Total/Average | 19 | 103.1 | 100.0 | 100.0 | 15.0 | 8.0 | 7.3 | 100.0 |
Summary by Geographical Area
at 30 June 2026
Geographical Area | Number of Properties | Valuation(£m) | MarketValue(%) | Occupancy by ERV(%) | WAULTto break(years) | Gross Passing Rental Income(£m) | ERV (£m) | ERV 1 (%) |
West Midlands | 4 | 27.4 | 26.5 | 100.0 | 8.6 | 2.2 | 2.0 | 27.2 |
The North West & Merseyside | 2 | 22.7 | 22.0 | 100.0 | 32.5 | 1.6 | 1.5 | 21.3 |
Rest of South East | 4 | 17.2 | 16.7 | 100.0 | 7.4 | 1.3 | 1.2 | 16.4 |
South West | 2 | 12.1 | 11.8 | 100.0 | 19.9 | 1.0 | 0.9 | 12.0 |
London | 3 | 10.4 | 10.1 | 100.0 | 7.9 | 0.9 | 0.8 | 10.5 |
Eastern | 2 | 7.0 | 6.8 | 100.0 | 8.1 | 0.5 | 0.4 | 6.1 |
Yorkshire and the Humber | 2 | 6.3 | 6.1 | 100.0 | 15.6 | 0.5 | 0.5 | 6.5 |
Total/Average | 19 | 103.1 | 100.0 | 100.0 | 15.0 | 8.0 | 7.3 | 100.0 |
1 The ERV (%) in the summary by sector and geographical area is calculated using the precise unrounded ERV figures, not the rounded ERV (£m).
Income Allocation by Type
|
|
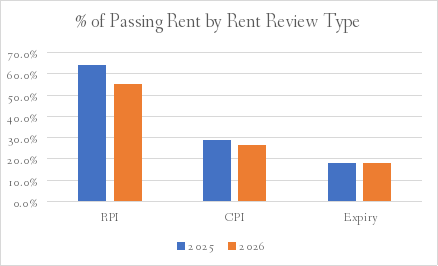
Inflation linked – RPI | 55.2% (2025: 64.2%) |
Inflation linked – CPI | 26.7% (2025: 28.1%) |
Expiry or Open Market Value Reviews | 18.1% (2025: 7.7%) |
The table below illustrates the weighting of the Group’s contracted rental income, based on the type of rent review associated with each lease.
% of Passing Rent by Rent Review Type
% of Passing Rent by Review Frequency
% of Passing Rent by Cap Band
Property Portfolio at 30 June 2026
Property | Sector | Region | Market Value |
| Pocket Nook Industrial Estate, St Helens | Industrial Warehouse | The North West & Merseyside | £11.80m |
| Bramall Court, Salford | Residential | The North West & Merseyside | £10.85m |
| Grazebrook Industrial Estate, Works 1 & 2, Dudley | Industrial Warehouse | West Midlands | £8.05m |
| Motorpoint, Birmingham | Automotive & Petroleum | West Midlands | £7.55m |
| Silver Trees, Bristol | Healthcare | South West | £6.83m |
| Premier Inn, Camberley | Hotel | Rest of South East | £6.63m |
| Prime Life Care Home, Solihull | Healthcare | West Midlands | £6.20m |
| Droitwich Spa Retail Park, Droitwich | Retail Warehouse | West Midlands | £5.55m |
| Duke House, Swindon | Hotel | South West | £5.30m |
| Virgin Active, London | Leisure | London | £5.28m |
| Unit 2, Dolphin Park, Sittingbourne | Industrial Warehouse | Rest of South East | £4.69m |
| Hoddesdon Energy, Hoddesdon | Power Station | Eastern | £4.53m |
| Volvo Slough, Slough | Automotive & Petroleum | Rest of South East | £4.25m |
| Prime Life Care Home, Brough | Healthcare | Yorkshire and the Humber | £4.20m |
| Pure Gym, Vauxhall, London | Leisure | London | £3.58m |
| Champneys Beauty College, Tring | Education | Eastern | £2.50m |
| Unit 14, Provincial Park, Sheffield | Industrial Warehouse | Yorkshire and the Humber | £2.10m |
| YMCA Nursery, Southampton | Education | Rest of South East | £1.68m |
| Pure Gym, Chiswick, London | Leisure | London | £1.57m |
Total |
|
| £103.1m |
Top Ten Tenants at 30 June 2026
Tenants | Property | Annual Contracted Rental Income (£’000) | % of PortfolioTotal PassingRental Income | WAULT to break(Years) |
Mears Group Plc | Bramall Court, Salford | 838 | 10.5% | 15.1 |
Meridian Steel Ltd | Grazebrook Industrial Estate, Dudley & Sheffield | 824 | 10.3% | 0.9 |
Prime Life Ltd | Prime Life Care Home, Brough & Solihull | 808 | 10.1% | 22.4 |
Motorpoint Ltd | Motorpoint, Birmingham | 568 | 7.1% | 11.0 |
Virgin Active Health Clubs Ltd | Virgin Active, London | 521 | 6.6% | 8.3 |
Handsale Ltd | Silver Trees, Bristol | 509 | 6.4% | 22.6 |
Premier Inn Hotels Ltd | Premier Inn, Camberley | 504 | 6.3% | 5.7 |
Travelodge Hotels Ltd | Duke House, Swindon | 481 | 6.0% | 17.9* |
Pure Gym Ltd | Pure Gym, Chiswick & Vauxhall | 407 | 5.1% | 7.4 |
B&M Bargains | Droitwich Spa Retail Park, Droitwich | 364 | 4.6% | 3.2 |
Total |
| 5,824 | 73.0% | 11.8** |
* The WAULT calculations includes an additional three years reflecting a landlord’s option to extend until 31 May 2044. ** This WAULT calculation, which considers income solely from the top ten tenants, differs from the portfolio-wide WAULT of 15.0 years.
Tenancy Schedule
Tenant | Property | Annual Contracted Rental Income (£’000) | Break Date | Expiry Date |
Mears Group Plc | Bramall Court | 838 |
| 16/08/2041 |
Motorpoint Ltd | Motorpoint | 568 |
| 24/06/2037 |
Virgin Active Health Clubs Ltd | Virgin Active | 521 |
| 28/09/2034 |
Handsale Ltd | Silver Trees | 509 |
| 14/01/2049 |
Premier Inn Hotels Ltd | Premier Inn | 504 | 25/03/2032 | 24/03/2037 |
Travelodge Hotels Ltd | Duke House | 481 |
| 31/05/2044 |
Prime Life Ltd | Prime Life Care Home, Solihull | 473 |
| 21/11/2048 |
Meridian Steel Ltd | Grazebrook Industrial Estate, Works 2 | 400 |
| 21/05/2027 |
B&M Bargains | Droitwich Spa Retail Park | 364 |
| 31/08/2029 |
Prime Life Ltd | Prime Life Care Home, Brough | 335 |
| 21/11/2048 |
Hoddesdon Energy Ltd | Hoddesdon Energy | 333 | 27/02/2032 | 26/02/2050 |
Doré Metal Services Southern Ltd | Unit 2, Dolphin Park | 307 | 13/09/2028 | 12/09/2033 |
Pure Gym Ltd | Pure Gym, Vauxhall, London | 287 |
| 10/12/2032 |
Volvo Car UK Ltd | Volvo Slough | 281 |
| 16/03/2037 |
Meridian Steel Ltd | Grazebrook Industrial Estate, Works 1 | 267 |
| 21/05/2027 |
Biffa Waste Services Ltd | Pocket Nook Industrial Estate | 203 |
| 24/02/2133 |
Secretary of State for Communities & Local Government | Pocket Nook Industrial Estate | 200 | 30/01/2033 | 29/01/2048 |
Champneys Tring | Champneys Beauty College | 175 |
| 18/04/2039 |
Meridian Steel Ltd | Unit 14, Provincial Park | 157 |
| 21/05/2027 |
Biffa Waste Services Ltd | Pocket Nook Industrial Estate | 150 |
| 31/03/2134 |
BGEN Ltd | Pocket Nook Industrial Estate | 145 |
| 04/04/2027 |
YMCA Fairthorne Group | YMCA Nursery | 145 |
| 17/02/2044 |
Pure Gym | 500 Chiswick High Road | 120 | 23/04/2036 | 23/04/2041 |
Pets at Home | Droitwich Spa Retail Park | 113 |
| 13/01/2028 |
BGEN Ltd | Pocket Nook Industrial Estate | 66 | 05/04/2027 | 04/04/2030 |
The Salvation Army Trustee Company | Duke House | 27 |
| 17/07/2032 |
Kingscrown Land & Commercial Ltd | Pocket Nook Industrial Estate | -* |
| 28/09/2045 |
Camberley Properties Ltd | Premier Inn | - |
| 23/06/3010 |
Southern Electric Parcel Distribution Plc | Premier Inn | - |
| 20/02/2111 |
GreenSquareAccord Limited | Duke House | - |
| 17/09/3006 |
* Ground rents less than £150 per annum.
Environmental, Social and Governance Report
The Group recognises that Environmental, Social and Governance (‘ESG’) matters and Climate-Related risks are of utmost importance to sustainable investment, long term performance of the Group’s property portfolio and a focus for the business and investor community. The Group is committed to understanding how best to consider ESG factors in all facets of its business, from business strategy to investment decisions and company operations.
In order to meet investors’ expectations, the Group and its advisers adopt both financial and non-financial strategies to drive long-term value with an innovative yet disciplined and conscientious approach to ESG in respect of the property portfolio management including but not limited to:
Environmental
A proactive approach to procurement of Energy Performance Certificate (‘EPC’) reassessments ahead of the requirements set out in the Minimum Energy Efficiency Standards 2023, maintaining quarterly reviews of EPC schedules, identification of opportunities to improve energy efficiency, and working closely with tenants who occupy under full repairing and insuring leases.Ongoing environmental reviews and audits as part of regular due diligence, including regular asset inspections to avoid any breach in environmental legislation.Responsible refurbishment in respect of all works to assets with consideration of the best approach to improving the EPC rating against potential spend, liaising with tenants in respect of any fit-out or alterations to reuse existing materials where feasible to reduce waste.Leverage technology for data management being used to monitor and drive efficiency.Social
Commitment to occupier engagement.Encourage improvements to each asset such as installing defibrillators & electrical charging points.Provision of regular training and awareness to all managers on issues, such as wellbeing and mental health.Governance
Client checks being completed on all tenants as well as new suppliers and contractors.Regular tenant engagement and inspections to ensure assets are used as agreed within leases.Effective tracking of legislative requirements to assess and monitor risks and opportunities.The Group is limited in its ability to influence ESG factors for the Group’s properties as the properties are fully let on commercial full repairing leases in accordance with the Group’s strategy to hold long leases.Diversity
As an externally managed business, the Company does not have any employees or office space. As such, the Group does not operate a diversity policy with regards to any administrative, management and supervisory functions. A description of the Board’s policy on director diversity can be found in the Corporate Governance Report of the Annual Report.
Employees
The Group has no employees and accordingly no requirement to report separately in this area as the management of the portfolio has been delegated to the AIFM and Investment Adviser.
The AIFM and Investment Adviser are equal opportunities employers who respect and seek to empower each individual and the diverse cultures, perspectives, skills and experiences within their workforce.
Human Rights
The Group is not within the scope of the Modern Slavery Act 2015 because it has not exceeded the turnover threshold and therefore no further disclosure is required in this regard.
Business Relationships
As well as the critical day-to-day portfolio management, the Group has service providers that ensure the smooth running of the Group’s activities. The Group’s key service providers are listed in the Annual Report, and the Management Engagement Committee (‘MEC’) annually review the effectiveness and performance of these service providers, taking into account any feedback received.
The Group, AIFM and Investment Adviser and other third-party service providers maintain high standards of business conduct by acting in a collaborative and responsible manner with all business partners that protects the reputation of the Group as a whole.
Climate-Related Reporting
The Board has considered the applicability of the Task Force on Climate-Related Financial Disclosures (TCFD) recommendations and the evolving UK sustainability reporting framework. The Company has not, for the year ended 30 June 2026, prepared disclosures fully aligned with all TCFD recommendations or IFRS Sustainability Disclosure Standards. The Board considers its current approach proportionate to the nature, size and externally managed structure of the Company but will continue to review reporting requirements and investor expectations as the regulatory landscape develops.
The Company nevertheless considers climate-related risks within its principal risk management and investment oversight processes.
As an externally managed REIT, the Company relies on the AIFM and Investment Adviser to assess and monitor ESG matters and Climate-Related risks and to report regularly to the Board on relevant developments.
Greenhouse Gas Emissions
As an investment company, the Group’s own direct environmental impact is minimal and greenhouse gas (‘GHG’) emissions are negligible. The GHG emissions in relation to the Group’s property portfolio is disclosed below.
The Group has followed UK Government environmental reporting guidelines and used the UK Government 2026 greenhouse gas reporting conversion factors for company reporting to identify and report relevant GHG emissions over which it has Operational Control (where data is available) for the 12-month period to 30 June 2026.
An independent consultancy specialising in the application of sustainability in commercial real estate was appointed to calculate the GHG statement and provide verification on the approach used.
Scopes
GHG emissions have been reported against the following ‘Scopes’, as defined by the GHG Protocol and where relevant:
Scope 1: (not relevant to AIRE): Direct emissions from owned vehicles, controlled boilers and fugitive emissions from air conditioning systems under landlord control.
Scope 2: Indirect emissions from electricity purchased by the Company and consumed within real estate assets owned by the Company.
Scope 3: Indirect emissions from electricity and gas purchased/consumed within AIRE assets, by tenants, where the tenant is counterparty to the energy supply.
Statement of GHG Emissions
The table below sets out the emissions per sector and for the Group overall in the year ended 30 June 2026. The approach taken follows guidance provided by UK Government Reporting Guidelines and EPRA Best Practice Recommendations of Sustainability Reporting 2024.
Sector | Scope | Absolute tonnes of carbon dioxide equivalent(tCO2e) | Like-for-like comparison ofcarbon dioxide equivalent(tCO2e)* | Tonnes of carbon dioxide equivalent per m2 (tCO2e) | |||
2025/26 | 2024/25 | Difference (tCO2e) | % change | 2025/26 | 2024/25 | ||
Retail Park | Scope 2 | 1.07 | 1.43 | -0.36 | -25.17% | n/a** | n/a |
Industrial warehouse | Scope 3 – Elec. | 50.64 | 72.95 | -22.31 | -30.58% | 0.0083 | 0.012 |
Total | Scope 2 & 3 | 51.71 | 74.38 | 22.67 | -30.48% | 0.0083 | 0.012 |
* Like-for-like requires 24 months of data for the current and previous reporting year (July 2024 – June 2026). Both assets provided 24 months of data therefore like-for-like calculations were possible.
** A carbon dioxide equivalent for Scope 2 is not possible as only external areas covered.
Statement of Energy Usage
The table below sets out the energy use per sector and for the Group overall. The approach follows guidance provided by the GHG Reporting Guidelines (DESNZ, 2025) and the EPRA Best Practice Recommendations on Sustainability Reporting 2024.
Sector | Energy Source | Absoluteenergy usage(kWh) | Like-for-likeenergy usage(kWh) | ||
2025/26 | 2024/25 | Difference (kWh) | % change | ||
Retail park | Electricity | 8,151 | 8,085 | 66 | 0.81% |
Industrial warehouse | Electricity | 386,726 | 412,171 | -25,445 | -6.17% |
Total | Electricity | 394,877 | 420,256 | -25,379 | -6.04% |
Intensity Ratios
In addition to reporting relevant absolute GHG emissions (per scope and per sector), the Group has chosen to report intensity ratios, where appropriate. An intensity measure is reported for assets within the like-for-like portfolio, where:
No major renovation or refurbishment has taken place i.e. affecting more than 50% of the building by area or number of occupantsOccupancy is at least 75%At least 24 months data is availableEmissions reported relate to an indoor areaWhilst no landlord meters reflect the above criteria for an intensity metric, the Group has applied an intensity figure for one asset, Pocket Nook, an Industrial Warehouse, where the landlord procures the energy and directly recharges this to the tenant. An intensity metric has not been produced for Droitwich Spa retail park on the basis that the landlord-controlled meter does not reflect the above criteria (emissions reported relate to an indoor area).
Normalisation factors
No normalisation factors have been considered for this annual report.
Assurance Statement
The Group’s GHG emissions have been calculated and verified by an independent third-party in accordance with the principles of ISO 14064. A full copy of the methodology used, including scope, source or data and conversion factors, is available on request.
Property Portfolio ESG Activity
During the year ended 30 June 2026, the Group has worked closely with its tenants to encourage improvements in ESG activities within the property portfolio.
Two new EPC’s ratings have been carried out for the Driving Centre in St Helens which improved from B46 to A+-6 following refurbishment works & installation of PV panels by the DVLA, and YMCA which fell from B32 to C59 due to the changes in EPC grading for gas fired heating systems. Recommendations of EPC assessors are being considered on two other properties by the occupiers including replacement of LED lighting and boiler replacement.
Year-on-Year EPC Comparison
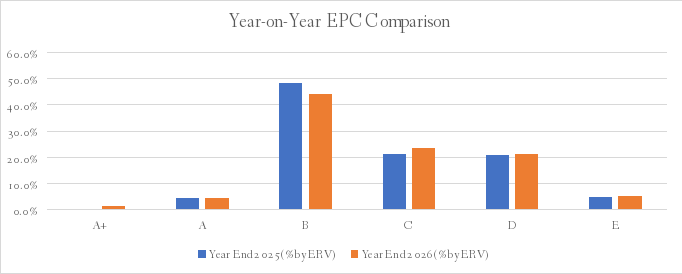
Other than the changes for SoS and YMCA’s EPC rating and the disposal of Crawley (B) the changes within the graph above are as a result of changes to relative ERV levels.
In the histogram above, the highest EPC rating of E applies to Unit 14 Provincial Park, Sheffield where the tenant is considering the cost efficiency of replacing their oil-fired boiler to electric. At Unit 2 Pocket Nook, St Helens, though the nature of the open-ended industrial process does not conform to EPC standard assessment, an exemption can be sought. The remaining properties in the portfolio have an EPC rating of D or above. 50.0% of the portfolio falls between A+ and B.
Section 172(1) Statement
The following disclosure describes how the directors have had regard to the matters set out in section 172(1)(a) to (f) of the Companies Act 2006, in promoting the success of the Company for the benefit of members as a whole.
This section describes how the Board has regard to the likely consequences of any decision in the long term, the need to foster the Company’s business relationships with suppliers, customers and others, the desirability of the Company maintaining a reputation for high standards of business conduct, and the need to act fairly as between members of the Company. The Company does not have any employees and therefore s172(1)(b) is not applicable to the Company. The impact of the Company’s operations on the community and the environment is set out more fully in the Environmental, Social and Governance section above.
Stakeholder | Issues of importance | Engagement | Effect of engagementon key decisions |
ShareholdersThe Group’s investment objective is to deliver an attractive total return to shareholders. Shareholders are directly impacted by changes to the Company’s NAV and thus the share price and dividends. | • Attractive and sustainable level of income, earnings and dividends. • Long-term income stream linked to inflationary growth. • Robust corporate governance structure and well-performing service providers. • Strategic direction of the Company. • Execution of investment objective. • Value for money – low ongoing charges. | • Shareholder engagement is set out in the Corporate Governance Report in the Annual Report. • As a publicly listed Company, the Company is subject to Listing Rules and other regulatory disclosure requirements which the Board abides by with the assistance of the Company Secretary and corporate broker. | The effect of shareholder engagement has fed into each aspect of the Board’s decision-making. The total aggregate dividends for the year have decreased compared to the prior year and the Board has also worked to keep expenses under control. |
Service Providers As an externally managed REIT, the Company conducts all its business through its service providers, the key ones being the Investment Adviser, Property Manager, Company Secretary, AIFM, depositary and corporate broker. | • Reputation of the Company and maintaining high standards of business conduct. • Productive working relationships with the Company. • Fair and transparent service agreements. • Collaboration. | • Effective and consistent engagement both through formal Board meetings and regularly outside the meetings. • Annual evaluation of key service providers. • Culture set by the Board and communicated to all providers. | Clear and effective strategic oversight and culture by the Board has been crucial to enhancing the effectiveness of the Company’s key service providers. The Board has worked closely with its service providers to maintain and continually improve processes and to ensure that the Company’s values are aligned with them. |
TenantsTenants with strong business fundamentals and profitable operations are one of the key components to ensure a consistent income stream and ability to pay dividends to the Company’s shareholders. | • Positive working relationship with the Board, Investment Adviser and Property Manager.Rent reviews.Fair lease terms.Long-term strategy and alignment with the tenant’s business operations.Financial stability of tenants. | • To ensure the Investment Adviser and Property Manager generate and foster good relationships with our tenants. • Focus on asset management initiatives to assist our tenants where applicable. | There is regular contact between the Property Manager and all the Group’s tenants. Rent reviews have all been completed on time and collection of rent at 100% is indicative of good tenant relations. |
Debt provider The Board and the Investment Adviser maintain a positive working relationship with its debt provider, HSBC UK Bank plc. | • Compliance with loan covenants.Responsible portfolio management. | • Ongoing engagement by the Investment Adviser throughout the year and by the Board. | The Board and the Investment Adviser have a good relationship with the Group’s debt provider. |
Society and the environment As an investor in real estate, the Company’s assets have an impact on the built environment. Environmental, Social and Governance (‘ESG’) factors increasingly apply alongside of financial returns. | • Responsible investing together with sustainability. • Long-term strategy to take account of ESG considerations without negatively impacting financial returns. | • Regular engagement with tenants in respect of EPC requirements. • Ensuring shareholder engagement covers ESG. | The Board has encouraged both the Investment Adviser and Property Manager to consider ESG on investment and on an ongoing basis. |
Principal decisions
Principal decisions are those that have a material impact to the Group and its key stakeholders. In taking these decisions, the directors considered their duties under section 172 of the Act.
Dividend and Dividend Policy
Given the Company’s Investment Objective, dividends are a key matter for the Board to consider and have a material impact on shareholders, as a key stakeholder. For the year ended 30 June 2026, the Board declared four interim dividends totalling 5.6pps (2025: 6.2pps), representing a 9.7% decrease on the previous year.
As last year, the Board paid four interim dividends at quarterly intervals to provide shareholders with a consistent and timely income stream. The Board does not intend to continue with this practice and, instead, will declare dividends in the future in compliance with the REIT regime’s rules.
Property Transactions
In the year, one property transaction completed, being the sale of the Group’s petrol filling station at Crawley for £4.5 million (gross of disposal costs). This property represented 4.0% of the Group’s portfolio capital valuation at 30 September 2025. The disposal represented a net initial yield of 6.3%.
Investment Advisory Fees
The Group’s Investment Adviser is Martley Capital Real Estate Investment Management Ltd (‘Martley Capital’), with effect from 1 January 2026 the terms of the management fee have been altered so that the Investment Adviser shall be entitled to receive a rate equivalent of 0.50% per annum of NAV (subject to a minimum fee of £400,000 per annum) payable quarterly in advance. This fee is subject to an annual increase from 1 January each year in line with the percentage to change in the Retail Prices Index (RPI) published by the UK Office for National Statistics subject to a minimum annual increase of 3% and a maximum annual increase of 5%.
During the year the Group incurred £380,000 in respect of investment advisory fees to Martley Capital (2025: £360,000). No amounts were accrued at the year-end (2025: £ nil).
Principal Risks and Uncertainties
The Group’s assets consist of UK commercial property. Its principal risks are therefore related to the commercial property market in general, but also to the particular circumstances of the individual properties and the tenants within the properties.
The Board has overall responsibility for reviewing the effectiveness of the system of risk management and internal control which is operated by the AIFM and, where relevant, the Investment Adviser. The Group’s ongoing risk management process is designed to identify, evaluate and mitigate the risks the Group faces.
The Board undertakes a semi-annual risk review with the assistance of the Audit Committee, to assess the adequacy and effectiveness of the AIFM’s, and where relevant the Investment Adviser’s, risk management and internal control systems.
The Board has carried out a robust assessment of the principal and emerging risks facing the Group, including those that would threaten its business model, future performance, solvency or liquidity.
An analysis of the principal risks and uncertainties is set out in the table below. This does not purport to be exhaustive as some risks are not yet known and some risks are currently not deemed material but could turn out to be material in the future.
Principal risks and their potential impact | How risk is managed | Risk assessment |
Real estate risks |
|
|
1. Tenant default Failure by tenants to comply with their rental obligations could affect the income that the properties earn and the ability of the Group to pay dividends to its shareholders.Macroeconomic trends discussed through the report, including rising interest rates, higher inflation and the possibility of recession have the ability to materially impact on a tenant’s business. This could result in tenants being unable to comply with their rental obligations. | The Group’s investment policy limits our exposure to any one tenant to 15% of Gross Asset Value. The maximum exposure to any one tenant (calculated by GAV) is 10.1% as at 30 June 2026. The Group benefits from a balanced portfolio with a diversified tenant base and is therefore not reliant on a single tenant or sector. In the due diligence process prior to acquiring a property, covenant checks are carried out on tenants which are repeated on a regular basis. The Investment Adviser and Property Manager conduct ongoing monitoring and liaise with tenants to manage potential bad debt risk. | Probability:Moderate to highImpact:HighMovement:No change |
2. Portfolio concentration Any downturn in the UK and its economy or regulatory changes in the UK could have a material adverse effect on the Group’s operations or financial condition. Greater concentration of investments in any sector or exposure to the creditworthiness of any one tenant or tenants may lead to greater volatility in the value of the Group’s investments, NAV and the Company’s share price. | The Group has investment restrictions in place to invest and manage its assets with the objective of spreading and mitigating risk. Having a diversified portfolio in respect of both sector and tenants provides reduced potential volatility in the portfolio and the impact rating for this risk is accordingly set at low to moderate. | Probability:Low to moderateImpact:Low to moderateMovement:No change |
3. Property defects Due diligence may not identify all the risks and liabilities in respect of an acquisition (including any environmental, structural or operational defects) that may lead to a material adverse effect on the Group‘s profitability, the NAV and the Company’s share price. | The Group’s due diligence relies on the work (such as legal reports on title, property valuations, environmental, building surveys) outsourced to third parties that have appropriate Professional Indemnity cover in place. Both the AIFM and Board review the report produced by the Investment Manager for each prospective acquisition and will challenge accordingly. | Probability: Low to ModerateImpact: ModerateMovement: No change |
4. Rate of inflation Rent review provisions may have contractual limits to the increases that may be made as a result of the rate of inflation. If inflation is in excess of such contractual limits, the Group may not be able to deliver targeted returns to shareholders. | The inflation linked (RPI/CPI) leases in the portfolio have contractual rent review collars, with the lowest floor being 0%, and the lowest cap at 3%. The majority of caps are in excess of RPI and CPI forecasts during the next five-year rent review cycle:
- Half of the caps are 4.00% or above, including a number with no caps- RPI forecast for next five years of 2.8%- CPI forecast for next five years of 2.1% The risk of inflation is somewhat mitigated by the leases that have no cap. In addition, a total of five leases undergo reviews annually which will allow inflation changes to be reflected expeditiously. | Probability:ModerateImpact:ModerateMovement:No change |
5. Property market Any recession or future deterioration in the property market could, inter alia, (i) lead to an increase in tenant defaults, (ii) make it difficult to attract new tenants for its properties, (iii) lead to a lack of finance available to the Group, (iv) cause the Group to realise its investments at lower valuations; and (v) delay the timings of the Group’s realisations.Any of these factors could have a material adverse effect on the ability of the Group to achieve its investment objective. | The Group has investment restrictions in place to invest and manage its assets with the objective of spreading and mitigating risk.
Most of the leases provide a relatively long unexpired term and contain upward only rent reviews which are linked to either RPI or CPI. Because of these factors, the Group expects that the assets will show less volatile valuation movement over the long term. | Probability: Moderate to highImpact: Moderate to highMovement: No change |
6. Property valuation Property is inherently difficult to value due to the individual nature of each property. There may be an adverse effect on the Group’s profitability, the NAV and the Company’s share price in cases where properties are sold whose valuations have previously been materially overstated. | The Group uses an independent valuer (Knight Frank LLP) to value the properties on a quarterly basis at fair value in accordance with accepted RICS appraisal and valuation standards. | Probability:Low to moderateImpact:Moderate to highMovement:No change |
7. Operational Risk Property defect in non-freehold/indirectly managed assets leading to loss. Where the Company holds a long lease (or similar interest) rather than the freehold, and/or where day to day building management and buildings insurance are considered by a third party (e.g. freeholder or their managing agent), a building fabric failure or inherent defect (e.g. water ingress, structural or services fault) can: (i) interrupt occupation and rent payments; (ii) create cash-flow timing mismatches pending loss of rent recoveries; (iii) delay remedial works due to third party control over diagnosis, tendering and reinstatement; (iv) cause valuation pressure and additional asset management time; and (iv) generate stakeholder/tenant dissatisfaction and reputational impact. Insurance may respond, but recoveries can be subject to deductibles, scope disputes and prolonged adjusting. | At purchase, the Investment Adviser and AIFM undertake technical due diligence (surveys, services and envelope inspections; review of service charge regimes, repairing obligations and inherent defect provisions), and legal due diligence is performed to tighten lease covenants, secure step in and information rights, and to require timely remedial action by the freeholder/managing agent. Furthermore, the contractual/insurance structure documents and maintains loss of rent (LoR) cover and verifies the freeholder’s buildings insurance adequacy. The Investment Adviser, drawing on extensive property experience, actively communicates with the tenant, AIFM and the Company Board to monitor progress and mitigate operational disruption. In addition, the portfolio is significantly diversified by sector and geography, which reduces risk concentration and limits the propagation of localised events (e.g. flooding) across the portfolio. | Probability:ModerateImpact:LowMovement:N/A (new risk) |
8. Investments are illiquid The Group invests in commercial properties. Such investments are illiquid; they may be difficult for the Group to sell and the price achieved on any realisation may be at a discount to the prevailing valuation of the relevant property. | The Group aims to hold the properties for long-term income and all property investment/disinvestment is managed carefully to ensure there is no undue pressure on cash flow that would require a quick sale of assets.
The Company’s dividend is funded from net revenue and is not affected by the portfolio’s (il)liquidity. | Probability:LowImpact:ModerateMovement:No change |
9. Environment The Group is subject to environmental regulations. In addition to regulatory risk, there is a growing importance being placed on ESG credentials by tenants, which could lead to difficulty in letting vacant space. Properties could be impacted by extreme environment events such as flooding. Climate change could accelerate more quickly leading to adverse physical impacts as well as regulatory change. Failure by the Group to meet current or future environmental targets could result in penalties, increased costs, a reduction in asset values and have an adverse effect on the Company’s reputation, leading to loss of good quality tenants. | The current regulations require annual mandatory Green House Gas (GHG) reporting, which will be carried out as part of the annual report and will result in minimal expenditure for the Group.
Furthermore, the Investment Adviser has prepared an ESG strategy to ensure it meets legal requirements and remains attractive to current and future tenants. Please see the ‘Environmental, Social and Governance’ section for further information. In depth research is undertaken on each property at acquisition. The Investment Adviser has adopted an environmental policy which it is in the process of applying to all properties within the portfolio. | Probability:ModerateImpact:ModerateMovement:No change |
Borrowing risks |
|
|
10. Breach of borrowing covenants The Group refinanced its £41 million fixed rate loan facility with a term loan of £31 million and a Revolving Credit Facility (‘RCF’) of £10 million both with HSBC UK. The covenants for the new facility are that Loan to Value should not exceed 60% and the Interest Cover Ratio (ICR) should be greater than 160% for cash trap and 150% for default ICR, which are both favourable to the previous fixed rate loan.The Group has had no breach of its covenants. Material adverse changes in valuations and net income may lead to breaches in the LTV and interest cover ratio covenants.If the Group is unable to operate within its debt covenants, this could lead to default and the loan facility being recalled. This could result in the Group being forced to sell properties to repay the loan facility, possibly resulting in a substantial fall in the NAV. | The Group monitors the borrowing covenants on a regular ongoing basis by cash flow forecasting, quarterly risk reports and a quarterly compliance certificate. The Group’s gearing at 30 June 2026 was 34.4%, materially below the covenant’s default LTV of 60%. On the same date the Group’s ICR was 422.2%, materially above the covenant cash trap ICR of 160%. Borrowing is carefully monitored by the Group, and action will be taken to conserve cash where necessary to ensure that this risk is mitigated. It is ensured that there is significant headroom in the LTV and interest cover covenants as part of the monitoring process.Diversification of both the portfolio and tenants limit the risk to the Group of any one geographic or sector property event and any one tenant default. Following the year end, the offer by Glenstone REIT plc (“Glenstone”) was declared unconditional on 9 September 2026, constituting a change of control under the Group’s £41 million HSBC facility. This initially gave HSBC the right to withhold further drawings and to require repayment of amounts outstanding, together with accrued interest. However, on 28 October 2026, AIRE and HSBC entered into a waiver and amendment letter under which HSBC consented to the change of control and subsequent de-listing, agreed to continue funding future utilisations and waived its right to require repayment in connection with the change of control. | Probability:Low to moderate*Impact:HighMovement:No change |
11. Interest rate exposure The Group is exposed to interest rate risk on its debt (£31million loan and £10million RCF) with HSBC which is on a floating rate basis. Changes in market interest rates will affect the Group’s finance costs and future cash flows. A sustained increase in interest rates would result in higher borrowing costs with a resultant negative impact on profitability, cash generation and, potentially, level of dividend. | The Group monitors interest rate movements and market conditions on an ongoing basis, and management assesses the potential impact of changes in interest rates on forecast cash flows, financing costs and covenant compliance. Where considered appropriate and cost effective, the Group may seek to mitigate exposure through the use of hedging, At present, the Group does not utilise derivative financial instruments to manage these exposures. The Group regularly assesses the sensitivity of its financial results to interest rate changes to support decision making and financial planning. | Probability:Low to moderateImpact:Moderate to HighMovement:N/A (new risk) |
12. Inability to refinance the current loan facilityThe inability of the Group to obtain new borrowings - of the amount required and at acceptable terms on 20 October 2030 will have an impact on the ability of the Group at this time to generate rental income and thus returns to shareholders.The Group’s debt consists of a term loan of £31 million and a £10 million RCF. Both the term loan and RCF are on floating rates for a fixed term of five years from 20 October 2025. | Both the term loan and RCF have an option to extend by two years if terms are mutually acceptable. Advice in respect of this re-finance will be taken at least 18 months in advance of the end of the fixed five-year term. Early discussions with the current lender together with market conditions at that time will drive re-financing direction. | Probability:LowImpact:LowMovement:Probability has moved downward from Low to Moderate to Low |
Corporate risks |
|
|
13. Balance between Company and Shareholder views** There is the risk that even though the Company’s objective and strategy continue to be attractive to investors, a significant shareholder, whose interests are not aligned with the interests of other shareholders, could threaten the Company’s long-term objectives and viability. This risk was heightened during the year when the Company received two separate approaches in relation to a possible offer for the entire issued and to be issued share capital of the Company. One approach came from a significant shareholder in the Company, which made a cash offer for the Company. The other came from a potential buyer, which made an indicative all-share proposal that the Board did not progress. | The Company reviews all proposals received from its shareholders or other potential buyers together with its financial and legal advisers to form a view on its merits or otherwise. In doing so, the Directors consider their duties to act in the best interests of all shareholders as a whole and not for the benefit of any one shareholder. As at 27 October 2026, Glenstone held or had received acceptances for approximately 87.08% of the Company’s issued share capital. Shareholders who have not accepted the offer may face reduced liquidity and changes to the Company’s management, strategy and dividend policy. Glenstone has stated its intention that, unless it acquires the entire share capital, the Board will include at least one director independent of Glenstone. Each current director is also a director of Glenstone. | Probability:HighImpact:HighMovement: N/A (new risk) |
14. Failure of service providers The Group has no employees and is reliant upon the performance of third-party service providers. Failure by any service provider to carry out its obligations to the Group in accordance with the terms of its appointment could have a materially detrimental impact on the operation of the Group. Should the Group pursue litigation against service providers, there is a risk that the Company may incur costs that are irrecoverable if litigation is unsuccessful. | The Board meets regularly with, and monitors, all of its key service providers, including the Investment Adviser. The Management Engagement Committee (MEC) reviews annually the performance of key service providers in conjunction with their service level agreements and makes use of Key Performance Indicators where relevant. In addition, the Audit Committee’s robust and ongoing review of risk management and internal controls covers key service providers.
| Probability: LowImpact: ModerateMovement: No change |
15. Dependence on the Investment Adviser The future ability of the Group to successfully pursue its investment objective and investment policy may, among other things, depend on the ability of the service providers to retain its existing staff and/or to recruit individuals of similar experience and calibre, and effectively carry out its services.The Group relies on the Investment Adviser to manage the assets and termination of the Investment Adviser agreement could severely affect the Group’s ability to effectively manage its operations. | The MEC performs a formal annual review of the Investment Adviser which covers the performance of the portfolio (both capital and income returns) and the performance of and engagement with the Martley Capital fund manager and other supporting staff. In addition, the Board meets regularly with Martley Capital and directors engage with them not only in Board meetings but also by email, telephone and ad hoc meetings. This helps to maintain a good working relationship. The dependence on Martley Capital is managed through segregating the roles of AIFM and Investment Adviser. | Probability:ModerateImpact: ModerateMovement: No change |
16. Ability to meet objectives The Group may not meet its investment objective to generate a secure and predictable income, that is sustainable in real terms, and at least maintain capital values in real terms, from investing predominantly in a portfolio of smaller commercial properties in the UK.The Group’s exposure to interest rates on its borrowing could negatively impact the Group’s ability to pay a level or increasing dividend. Poor relative total return performance may lead to an adverse reputational impact that affects the Group’s ability to raise new capital and new funds. | The Group has an investment policy to achieve a balanced portfolio with a diversified tenant base. This is reviewed by the Board at each scheduled Board meeting. The Group’s property portfolio has a WAULT to break of 15.0 years and a WAULT to expiry of 16.7 years. Further, over 81.9% of leases have inflation-linked upwards only rent reviews, representing a secure income stream on which to deliver attractive total returns to shareholders. Glenstone has stated that, if it holds less than 100% of the Company, it intends to pursue a managed wind-down, returning cash to shareholders within three years, subject to property market conditions. If implemented, the Company’s investment objective, investment policy and dividend policy would be expected to change, subject to any applicable approval requirements. The Board will consider the implications for the Company’s REIT status with its advisers. | Probability: ModerateImpact: HighMovement: No change |
Taxation risk |
|
|
17. Group REIT status The Group has UK REIT status that provides a tax-efficient corporate structure. If the Group fails to remain a REIT for UK tax purposes, its profits and gains will be subject to UK corporation tax. | The Company monitors REIT compliance through the Investment Adviser and Administrator on acquisitions and disposals and distribution levels; the Registrar and Broker on shareholdings; and third-party tax advisers to monitor REIT compliance requirements. Processes are in place to ensure ongoing compliance with REIT regulations. | Probability:LowImpact:HighMovement:No change |
Political/economic risk |
|
|
18. Political and macroeconomic events Such events present risks to the real estate and financial markets that affect the Group and the business of our tenants.The negative economic effects from the deterioration of the global economy, higher inflation and interest rates, the ongoing long-term effects of the Ukraine-Russia war and secondary effects from the pandemic including supply constraints could impact the portfolio, tenants and the ability of the Group to raise capital. | The Group only invests in UK properties with strong alternative use values and long leases, so the portfolio is well positioned to withstand an economic downturn. Tenant default risk arising from political and macroeconomic events is managed as described above. The Investment Adviser monitors both the macro and micro economy with special attention to those factors potentially impacting the Group, and reports to the Board on a regular basis. | Probability: HighImpact: HighMovement: No change |
Regulatory risk |
|
|
19. Disclosure risk Failure to properly disclose information to investors or regulators in accordance with various disclosure rules and regulations. Examples include AIFMD investor disclosures, annual reporting requirements, marketing/promotion disclaimers, data protection regulations etc. | Service providers including AIFM, Investment Adviser, Company Secretary, auditor, and corporate broker monitor disclosure obligations and liaise with the Board to ensure requirements are met. | Probability:Low to moderateImpact:ModerateMovement: No change |
20. Regulatory change New regulations or changes to existing regulations (particularly in relation to climate change) could result in sub-optimal performance of the Group or, in worst case, inability to continue as a viable business. | The Board receives regular updates on relevant regulatory changes (and prospective changes) from its professional advisers.The Investment Adviser monitors the impact of emerging legislation across all aspects of property investment and ESG has a particularly high profile at this time. The Investment Adviser uses an ESG pre-acquisition checklist to review purchases and also to ensure that the current portfolio is monitored, and that works are carried out as appropriate, with tenant’s agreement, to prevent asset depreciation. | Probability:LowImpact:HighMovement:No change |
* This risk rating applies at 30 June 2026, prior to the change of control on 9 September 2026.
** Shareholders who have not accepted the offer face one of two outcomes:
Squeeze-out: If Glenstone acquires +90% of the shares to which the offer relates, it may compulsorily acquire the remaining shares on the terms of the offer (70.0p per share) under section 979 of the Companies Act 2006.
Delisting: Otherwise, Glenstone has stated its intention to cancel the Company’s listing and seek admission to The International Stock Exchange (TISE). Remaining shareholders would then no longer benefit from the UK Listing Rules, the Disclosure Guidance and Transparency Rules or the UK Corporate Governance Code or AIFMD. They would instead be subject to TISE’s listing rules, whose continuing obligations are generally regarded as less onerous than those of the Listing Rules.
Emerging risks
The Board takes account of and considers emerging risks as part of its risk management assessment.
Going Concern and Viability Statement
Going Concern
The Group has considered its cash flows, financial position, liquidity position and borrowing facilities.
In particular, the Group’s unrestricted cash balance at the year-end was £2.3 million (2025: £3.1 million). The Group has no capital commitments or contingent liabilities. The Group refinanced its borrowings of £41 million on 20 October 2025 with HSBC (‘the HSBC Bank Facilities’). The HSBC Bank Facilities consist of both a fixed term loan of £31 million and a £10 million revolving credit facility, both on floating rates and on a fixed term of five years with an option to extend by two years if mutually acceptable. Details of the new debt facilities are contained in Note 13 to the financial statements which includes covenant details, all of which are reported in accordance with the Group’s risk management procedures and policies.
The Group has net current assets of £3.4 million at 30 June 2026 (2025: net current liabilities of £36.5 million) and has the ability to meet its financial obligations as they fall due.
In respect of the Loan, the Group is permitted to utilise up to 40% of GAV measured at drawdown with a Loan to GAV of 34.4% at 30 June 2026. Therefore, the Group had headroom against its borrowing covenant. The lender’s loan to value covenant of 60% is significantly higher than the Group’s Loan to GAV. In addition, if agreed by the current lender, two properties not secured against the Loan and valued at £8.5 million are available as additional security for the Loan.
The Loan also has a lender’s cash trap interest cover covenant of 160% and default interest cover of 150%. At 30 June 2026 the Group’s interest cover ratio was 422.2%, giving significant headroom. A ‘severe but plausible downside’ scenario has been projected. While rent collections have been strong, this scenario projects rent deferrals and write-offs for tenants with difficulty paying rents from operational cash flows. In this scenario the Group still has adequate headroom against the interest cover covenant and positive cash balances. Further detail of the assumptions made in assessing the adoption of Group’s going concern basis can be found in Note 2.4.
The Group benefits from a secure, diversified income stream from leases which are not overly reliant on any one tenant or sector, with the Group generating net cash flows from operating activities for the year being reported of £6.7 million. As a result, the directors believe that the Group is well placed to manage its financing and other business risks.
The going concern statement is based on the reporting requirement that the Group and the Company has adequate resources to continue in operational existence for the foreseeable future, being a period of at least 12 months from the date of these financial statements. For the reasons explained above, the Board is satisfied that the Group and the Company have adequate resources to continue in operational existence for the foreseeable future and is of the opinion that the going concern basis adopted in the preparation of the financial statements is appropriate.
Following its acquisition of a controlling interest in AIRE, Glenstone now intends to acquire the remaining shares through the ongoing takeover offer and, subject to reaching the relevant threshold, exercise its statutory squeeze-out rights, resulting in AIRE becoming a wholly owned subsidiary of the Glenstone Group. There is no intention to liquidate AIRE or cease its operations. The intention is for AIRE to continue operating as an income-producing property investment business, with the existing portfolio retained during the acquisition process.
The Board therefore considers that Glenstone’s intended strategy represents a change in ownership and operational management rather than a cessation of the underlying business and, accordingly, does not have a material adverse impact on the appropriateness of preparing the financial statements on a going concern basis.
Viability Statement
In accordance with provision 30 of the UK Corporate Governance Code, the Board has assessed the prospects of the Group for at least the 12-month period from the date the financial statements are approved as required by the ‘Going Concern’ provisions.
The Board has considered the nature of the Group’s assets and liabilities and associated cash flows and has determined that three years, from the balance sheet date up to 30 June 2029, is an appropriate and realistic timescale over which the performance of the Group can be forecast with a degree of accuracy. Even though the Group’s contractual income extends beyond three years, the Board considers this period (the ‘Period’) to be appropriate, given:
A major proportion of the leases contain an annual, three or five-year rent review pattern and therefore three years allow for the forecasts to include the reversion arising from most rent reviews;It is the period over which the Group’s medium-term business plan and cash flows are based; andIt is often factors beyond the Board’s control, such as market uncertainty and unknown tenant issues, that reduce the reliability of forecasting over a longer period.In performing its viability review, the Board considers the Group’s cash flows (noting that the Group’s property portfolio had a WAULT to break of 15.0 years and a WAULT to expiry of 16.7 years at 30 June 2026, representing a secure income stream for the Period), REIT compliance and relevant key financial ratios over the Period. The Board carried out a thorough review of the Group’s business model, following the change of control following the Glenstone offer being unconditional. The Group will operate as a subsidiary of Glenstone with its own management and will retain the HSBC Bank Facilities which are secured against the Group’s portfolio. The cash flow included an estimation of future performance, liquidity and banking covenant tests for the Period. The Board has assessed the extent of any operational disruption; potential curtailment of rental receipts; potential liquidity and working capital shortfalls; and diminished demand for the Group’s assets going forward, in adopting a going concern preparation basis and in assessing the Group’s longer-term viability.
These assessments are subject to sensitivity analysis, which involves flexing a number of key assumptions and judgements included in the financial projections:
Tenant default;Financing costs;Financing and refinancing; andProperty portfolio valuation movements.The Group’s debt:
The Group has borrowings of £41 million under a loan facility repayable on 20 October 2030 with HSBC. The HSBC Bank Facilities consist of both a fixed term loan of £31 million and a £10 million revolving credit facility, both on floating rates and on a fixed term of five years with an option to extend by two years if mutually acceptable. Details of the HSBC Bank Facilities are contained in Note 13 to the financial statements. Specifically with respect to viability and the Group’s debt:
the Loan covenants – at 30 June 2026, the asset valuations and rental income of the properties secured to HSBC would need to fall by 35.6%, 62.1% and 56.8%, respectively, before breaching the Loan to Value, and Historical and Projected Income Cover Cash Trap covenants; andthe cash flow modelling has taken account of the HSBC Bank Facilities and its covenants, and future interest rate predictions (assuming interest rate hedging is not put in place). The Group is in compliance with the HSBC Bank Facilities covenants throughout the cash flow period to 30 June 2029.Based on the prudent assumptions within the Group’s forecasts including the rent deferrals, tenant default, void rates, property valuation movements and the successful refinancing of the debt, the Board has a reasonable expectation that for the Period:
all current and future loan covenants will be complied with throughout the Period;REIT tests will similarly be complied with; andthe Group and the Company will be able to continue in operation and meet its liabilities as they fall due over the Period.Board Approval of the Strategic Report
The Strategic Report has been approved and signed on behalf of the Board by:
Adam Smith Chairman 28 October 2026
Statement of Directors’ Responsibilitiesin respect of the Annual Report and the Financial Statements
The directors are responsible for preparing the Annual Report and the Group and parent Company Financial Statements in accordance with applicable law and regulations.
Company law requires the directors to prepare Group and parent Company financial statements for each financial year. Under that law they are required to prepare the Group financial statements in accordance with international accounting standards in conformity with the requirements of the Companies Act 2006 and in accordance with the UK adopted international accounting standards. The directors have elected to prepare the parent Company financial statements in accordance with UK accounting standards, including FRS 101 Reduced Disclosure Framework and applicable law.
Under company law the directors must not approve the financial statements unless they are satisfied that they give a true and fair view of the state of affairs of the Group and parent Company and of their profit or loss for that period. In preparing each of the Group and parent Company financial statements, the directors are required to:
select suitable accounting policies and then apply them consistently;make judgements and estimates that are reasonable, relevant, reliable and prudent;for the Group financial statements, state whether they have been prepared in accordance with Companies Act 2006 and in accordance with UK adopted international accounting standards;for the parent Company financial statements, state whether applicable UK accounting standards have been followed, subject to any material departures disclosed and explained in the parent Company financial statements;assess the Group and parent Company’s ability to continue as a going concern, disclosing, as applicable, matters related to going concern; anduse the going concern basis of accounting unless they either intend to liquidate the Group or the parent Company, or to cease operations, or have no realistic alternative but to do so.The directors are responsible for keeping adequate accounting records that are sufficient to show and explain the Group’s and the parent Company’s transactions and disclose with reasonable accuracy at any time the financial position of the Group and the parent Company and enable them to ensure that its financial statements comply with the Companies Act 2006. They are responsible for such internal control as they determine is necessary to enable the preparation of financial statements that are free from material misstatement, whether due to fraud or error, and have general responsibility for taking such steps as are reasonably open to them to safeguard the assets of the Group and the parent Company and to prevent and detect fraud and other irregularities.
Under applicable law and regulations, the directors are also responsible for preparing a Strategic Report, Directors’ Report, Directors’ Remuneration Report and Corporate Governance Statement that complies with that law and those regulations.
The directors are responsible for the maintenance and integrity of the corporate and financial information included on the Company’s website. Legislation in the UK governing the preparation and dissemination of financial statements may differ from legislation in other jurisdictions.
We confirm that to the best of our knowledge:
the Consolidated Financial Statements, prepared in accordance with the applicable set of accounting standards, give a true and fair view of the assets, liabilities, financial position and profit or loss of the Company and the undertakings included in the consolidation taken as a whole;the Strategic Report and Directors’ Report include a fair review of the development and performance of the business and the position of the issuer and the undertakings included in the consolidation taken as a whole, together with a description of the principal risks and uncertainties that they face; andthat the Annual Report and the Consolidated Financial Statements, taken as a whole, are fair, balanced and understandable and provide the information necessary for shareholders to assess the Group’s position and performance, business model and strategy.On behalf of the Board
Adam Smith Chairman 28 October 2026
Financial Statements
Consolidated Statement of Comprehensive Income
For the year ended 30 June 2026
| 2026 |
| 2025 | |
| Notes | £’000 |
| £’000 |
Income |
|
|
|
|
Rental and other income | 3 | 8,891 |
| 8,570 |
Property operating expense | 4 | (709) |
| (781) |
Net rental and other income |
| 8,182 |
| 7,789 |
Other operating expenses | 4 | (1,784) |
| (1,066) |
Operating profit before fair value changes and gain on disposal |
| 6,398 |
| 6,723 |
Change in fair value of investment properties | 10 | (350) |
| 1,970 |
Gain on disposal of investment property | 10 | 313 |
| – |
Operating profit |
| 6,361 |
| 8,693 |
Finance expenses | 6 | (2,024) |
| (1,435) |
Profit before tax | 4,337 |
| 7,258 | |
Taxation | 7 | – |
| – |
Profit and total comprehensive income attributable to shareholders | 4,337 |
| 7,258 | |
Earnings per share (basic and diluted) | 8 | 5.39p |
| 9.02p |
EPRA EPS (basic and diluted) | 8 | 6.34p |
| 6.57p |
Adjusted EPS (basic and diluted) | 8 | 5.59p |
| 6.72p |
All items in the above statement are derived from continuing and total operations. No operations were acquired or disposed of during the year.
The accompanying Notes 1 to 20 form part of these consolidated financial statements.
Consolidated Statement of Financial Position
At 30 June 2026
| 2026 |
| 2025 | |
| Notes | £’000 |
| £’000 |
Non-current Assets |
|
|
|
|
Investment properties | 10 | 99,427 |
| 103,777 |
Current Assets |
|
|
|
|
Trade and other receivables | 11 | 4,522 |
| 4,236 |
Cash and cash equivalents |
| 2,307 |
| 3,148 |
Total current assets |
| 6,829 |
| 7,384 |
Total Assets |
| 106,256 |
| 111,161 |
Current Liabilities |
|
|
|
|
Trade and other payables | 12 | (3,441) |
| (2,878) |
Interest bearing loans and borrowings | 13 | – |
| (40,956) |
Total current liabilities |
| (3,441) |
| (43,834) |
Non-current Liabilities |
|
|
|
|
Interest bearing loans and borrowings | 13 | (35,780) |
| – |
Total non-current liabilities |
| (35,780) |
| – |
Total Liabilities | (39,221) |
| (43,834) | |
Net Assets |
| 67,035 |
| 67,327 |
Equity |
|
|
|
|
Share capital | 16 | 805 |
| 805 |
Capital reserve | 2 | 60,750 |
| 65,379 |
Retained earnings |
| 5,480 |
| 1,143 |
Total capital and reserves attributable to equity holders of the Company |
| 67,035 |
| 67,327 |
Net Asset Value per share (basic and diluted) | 8 | 83.27p |
| 83.64p |
EPRA Net Tangible Asset per share (basic and diluted) | 8 | 83.27p |
| 83.64p |
The accompanying Notes 1 to 20 form part of these Consolidated Financial Statements.
The Consolidated Financial Statements were approved by the Board of Directors on 28 October 2026 and were signed on its behalf by:
Adam SmithChairmanCompany number: 10727886
Consolidated Statement of Changes in Equity
For the year ended 30 June 2026
| Notes | Sharecapital£’000 | Capitalreserve£’000 | Retained earnings£’000 | Totalequity£’000 |
For the year ended 30 June 2026 |
|
|
|
|
|
Balance at 30 June 2025 |
| 805 | 65,379 | 1,143 | 67,327 |
Total comprehensive income attributable to shareholders |
| – | – | 4,337 | 4,337 |
Dividends paid | 9 | – | (4,629) | – | (4,629) |
Balance at 30 June 2026 |
| 805 | 60,750 | 5,480 | 67,035 |
For the year ended 30 June 2025 |
|
|
|
|
|
Balance at 30 June 2024 |
| 805 | 70,431 | (6,115) | 65,121 |
Total comprehensive income attributable to shareholders |
| – | – | 7,258 | 7,258 |
Dividends paid | 9 | – | (5,052) | – | (5,052) |
Balance at 30 June 2025 |
| 805 | 65,379 | 1,143 | 67,327 |
Consolidated Statement of Cash Flows
For the year ended 30 June 2026
| 2026 | 2025 | |
| Notes | £’000 | £’000 |
Cash flows from operating activities |
|
|
|
Profit before tax |
| 4,337 | 7,258 |
Adjustment for: |
|
|
|
Finance expenses | 6 | 2,024 | 1,435 |
Gain on disposal of investment property | 10 | (313) | – |
Change in fair value of investment properties | 10 | 350 | (1,970) |
Operating results before working capital changes |
| 6,398 | 6,723 |
Change in working capital |
|
|
|
(Increase)/decrease in receivables and prepayments |
| (391) | 2,228 |
Increase/(decrease) in other payables and accrued expenses |
| 562 | (12) |
Net cash flow generated from operating activities |
| 6,569 | 8,939 |
Cash flows from investing activities |
|
|
|
Purchase of investment property | 10 | – | (2,724) |
Net proceeds from disposal of investment property | 10 | 4,464 | – |
Net cash generated/(used in) from investing activities |
| 4,464 | (2,724) |
Cash flows from financing activities |
|
| |
Debt repayment | (41,000) | – | |
HSBC term loan drawdown | 31,000 | – | |
HSBC RCF drawdown | 10,000 | – | |
Repayment of RCF | (4,416) | – | |
Finance costs paid | (1,895) | (1,307) | |
Refinance costs paid | (934) | – | |
Dividends paid | 9 | (4,629) | (5,052) |
Net cash used in financing activities |
| (11,874) | (6,359) |
Net decrease in cash and cash equivalents |
| (841) | (144) |
Cash and cash equivalents at beginning of year |
| 3,148 | 3,292 |
Cash and cash equivalents at end of year |
| 2,307 | 3,148 |
The accompanying Notes 1 to 20 form part of these consolidated financial statements.
Notes to the Consolidated Financial Statements
for the year ended 30 June 2026
1. Corporate Information
Alternative Income REIT PLC (the ‘Company’) is a public limited company and a closed ended Real Estate Investment Trust (‘REIT’) incorporated on 18 April 2017 and domiciled in the UK and registered in England and Wales. The registered office of the Company is The Scalpel, 18th Floor, 52 Lime Street, London, United Kingdom, EC3M 7AF.
The Company’s Ordinary Shares are listed on the closed-ended investment funds category of the Official List of the Financial Conduct Authority (‘FCA’) and have been traded on the Main Market of the London Stock Exchange since the Company’s IPO on 6 June 2017.
The nature of the Group’s operations and its principal activities are set out in the Strategic Report.
2. Accounting policies
2.1 Basis of preparation
These consolidated financial statements (the ‘financial statements’) are prepared and approved by the directors in accordance with UK adopted International Accounting Standards (‘IFRS’) and in accordance with the Companies Act 2006 as applicable to companies reporting under those standards and the UK adopted International Accounting Standards (‘IAS’) Regulations.
These financial statements have been prepared under the historical cost convention, except for investment properties that have been measured at fair value.
The financial statements are presented in Pound Sterling (£) and all values are rounded to the nearest thousand pounds (£’000), except where otherwise indicated.
Basis of consolidation
The financial statements incorporate the financial statements of the Company and its subsidiaries (the ‘Group’).
Subsidiaries are the entities controlled by the Company, being Alternative Income Limited and Alternative Income REIT Holdco Limited.
New standards, amendments and interpretations, and forthcoming requirements
Standards effective from 1 July 2025
Certain new accounting standards and interpretations have been published that are not mandatory for annual periods beginning after 1 July 2025 and early application is permitted; however, the Group has not early adopted the new or amended standards in preparing these consolidated financial statements:
Classification and Measurement of Financial Instruments – Amendments to IFRS 9 Financial Instruments and IFRS 7 Financial Instruments: Disclosures (effective 1 January 2026)Annual Improvements to IFRS Accounting Standards (effective 1 January 2026), comprising amendments to:- IFRS 1 First-time Adoption of International Financial Reporting Standards;
- IFRS 7 Financial Instruments: Disclosures and its accompanying Guidance on implementing IFRS 7;
- IFRS 9 Financial Instruments;
- IFRS 10 Consolidated Financial Statements; and
- IAS 7 Statement of Cash flows
Presentation and Disclosure in Financial Statements – IFRS 18 (effective 1 January 2027)Subsidiaries without Public Accountability: Disclosures – IFRS 19 (effective 1 January 2027)Sale or Contribution of Assets between an Investor and its Associate or Joint Venture (Amendments to IFRS 10 and IAS 28) (effective date to defer indefinitely)IFRS 18 will replace IAS 1 Presentation of financial statements for annual periods beginning on or after 1 January 2027. While IFRS 18 will not impact the recognition or measurement of items in the financial statements, including net asset value (‘NAV’), it will introduce significant changes to the presentation and disclosure requirements. The Group is currently assessing the impact of adopting IFRS 18 on its consolidated financial statements.
The Group is also evaluating the impact of the amendments to IFRS 9 and IFRS 7, particularly in relation to the classification of financial assets and enhanced disclosure requirements.
The other new standards and amendments listed above which are not yet effective are not expected to have a material impact on the Group in the current or future periods.
2.2 Significant accounting judgements and estimates
In the application of the Group’s accounting policies the directors are required to make judgements, estimates and assumptions that affect the reported amounts recognised in the financial statements. However, uncertainty about these assumptions and estimates could result in outcomes that require a material adjustment to the carrying amount of the asset or liability in the future. The estimates and associated assumptions that have a significant risk of causing a material adjustment to the carrying amounts of assets and liabilities within the next financial year are outlined below:
Valuation of investment properties
The fair value of investment properties is determined by external property valuation experts to be the estimated amount for which a property should exchange on the date of the valuation in an arm’s length transaction. The Group’s properties have been valued on an individual basis. The valuation experts use recognised valuation techniques, applying the principles of both IAS 40 and IFRS 13.
The valuations have been prepared in accordance with the Royal Institution of Chartered Surveyors (‘RICS’) Valuation. Factors include current market conditions, annual rentals, the contractual terms of the leases and their lengths and location. The significant methods and assumptions used by valuers in estimating the fair value of investment properties are set out in Note 10.
The information provided to the valuers, and the assumptions and valuation models used by the valuers, are reviewed by the Board and the Audit Committee.
Principal versus agent considerations – services to tenants
The Group arranges for certain services to be provided to tenants. These arrangements are included in the contract the Group enters into as a lessor. The Group has determined that it controls the services before they are transferred to tenants, because it has the ability to direct the use of these services and obtain the benefits from them. The Group has determined that it is primarily responsible for fulfilling these services as it directly deals with tenants’ complaints and is primarily responsible for the quality or sustainability of the services. In addition, the Group has discretion in establishing the price that it charges to the tenants for the specified services.
Therefore, the Group has concluded that it is the principal in these contracts. In addition, the Group has concluded that it transfers control of these services over time, as services are rendered by the third-party service providers, because this is when tenants receive and, at the same time, consume the benefits from these services.
REIT status
The Group is a REIT and does not pay tax on its property income or gains on property sales, provided that at least 90% of the Group’s property income is distributed as a dividend to shareholders, which becomes taxable in their hands. In addition, the Group has to meet certain conditions such as ensuring the property rental business represents more than 75% of total profits and assets. Any potential or proposed changes to the REIT legislation are monitored and discussed with HMRC. It is the Board’s intention that the Group will continue as a REIT for the foreseeable future.
2.3 Segmental information
Each property held by the Group is reported to the chief operating decision maker. In the case of the Group, the chief operating decision maker is considered to be the Board of Directors. The review process for segmental information includes the monitoring of key performance indicators applicable across all properties. These key performance indicators include Net Asset Value, Earnings per Share and valuation of properties. All asset cost and rental allocations are also reported by property. The internal financial reports received by the directors cover the Group and all its properties and do not differ from amounts reported in the financial statements. The directors have considered that each property has similar economic characteristics and have therefore aggregated the portfolio into one reportable segment under the provisions of IFRS 8.
2.4 Going concern
The financial statements have been prepared on a going concern basis.
The Group’s business activities, together with the factors likely to affect its future development, performance and position are set out in the Strategic Report. The robust financial position of the Group, its net asset and current asset positions, its cash flows, liquidity position and borrowing facilities are described in the financial statements and the accompanying notes. The financial statements also include the Group’s objectives, policies and processes for managing its capital, its financial risk management objective and its exposures to market price risk, real estate risk, credit risk and liquidity risk.
The Investment Adviser on behalf of the Board has projected the Group’s cash flows for the period up to 30 September 2029, challenging and sensitising inputs and assumptions to ensure that the cash forecast reflects a realistic outcome given the uncertainties associated with the current economic environment. A longer-term projection had also been carried out up to 30 June 2030. The scenarios applied were designed to be severe but plausible, and to take account of the availability of mitigating actions that could be taken to avoid or reduce the impact or probability of the underlying risks.
The Group refinanced its debt of £41 million on 20 October 2025 and the Group has reported full compliance with its loan covenants to date. Based on cash flow projections, the directors expect the Group to continue to remain compliant. The headroom of the loan to value covenant is significant and any reduction in property values that would cause a breach would be significantly more than any reduction currently envisaged.
The Group has borrowings of £41 million under a loan facility repayable on 20 October 2030 with HSBC. The HSBC Bank Facilities consist of both a fixed term loan of £31 million and a £10 million revolving credit facility, both on floating rates and on a fixed term of five years with an option to extend by two years if mutually acceptable. Details of the HSBC Bank Facilities are contained in Note 13 which include covenant details, all of which will be reported in accordance with the Group’s risk management procedures and policies.
Based on the above, the Board believes that the Group has the ability and resources to continue in operational existence for the foreseeable future, being at least 12 months from the date of approval of the financial statements.
2.5 Significant accounting policies
The principal accounting policies applied in the preparation of these financial statements are set out below.
a) Functional and presentational currency
These financial statements are presented in Pound Sterling (£), which is the functional and presentational currency of the Group and its subsidiary undertakings. The functional currency of the Group and its subsidiaries is principally determined by the primary economic environment in which it operates. The Group did not enter into any transactions in foreign currencies during the period.
b) Revenue recognition
i) Rental income
Rental income under operating leases is recognised on a straight-line basis over the term of the lease, except for contingent rental income, which is recognised when it arises. For leases, which contain fixed or minimum uplifts, the rental income arising from such uplifts is recognised on a straight-line basis over the lease term.
Incentives for lessees to enter into lease agreements are spread evenly over the lease term, even if the payments are not made on such a basis. The lease term is the non-cancellable period of the lease together with any further term for which the tenant has the option to continue the lease, where, at the inception of the lease, the directors are reasonably certain that the tenant will exercise that option.
Lease modifications, such as lease extensions and rent reductions, are accounted for either as a separate lease or not as a separate lease.
A modification will only be treated as a separate lease if it involves the addition of one or more underlying assets at a price that is commensurate with the standalone price of the increase in scope. All other modifications are not treated as a separate lease.
If a modification is a separate lease, a lessee applies the requirements of IFRS 16 to the newly added asset, due as a result of the modification, independently of the original lease. The accounting for the original lease continues unchanged.
If a modification is not a separate lease, the accounting reflects that there is a linkage between the original lease and the modified lease. The existing lease liability is remeasured with a corresponding adjustment to the right-of-use asset on the effective date of the modification.
ii) Service charges and direct recharges
Revenue from service charges is recognised in the accounting period in which the service is rendered. For certain service contracts, revenue is recognised based on the actual service provided to the end of the reporting period as a proportion of the total services to be provided because the customer receives and uses the benefits simultaneously.
iii) Deferred income
Deferred income is rental income received in respect of future accounting periods.
iv) Dilapidation and lease surrender premium
Amounts received from tenants to terminate leases or to compensate for dilapidations are recognised in the Consolidated Statement of Comprehensive Income when the right to receive them arises.
c) Financing income and expenses
Financing income comprises interest receivable on funds invested. Financing expenses comprise interest and other costs incurred in connection with the borrowing of funds. Interest income and interest payable are recognised in profit or loss as they accrue, using the effective interest method which is significantly the same as the contracted interest.
d) Investment property
Property is classified as investment property when it is held to earn rentals or for capital appreciation or both. Investment property is measured initially at cost including transaction costs. Transaction costs include transfer taxes and professional fees to bring the property to the condition necessary for it to be capable of operating. The carrying amount also includes the cost of replacing part of an existing investment property at the time that cost is incurred if the replacement of that part will prolong or improve the life of the asset.
Subsequent to initial recognition, investment property is stated at fair value. Gains or losses arising from changes in the fair values are included in profit or loss, included as part of operating profit under change in fair value of investment properties.
Additions to properties include costs of a capital nature only. Expenditure is classified as capital when it results in identifiable future economic benefits, which are expected to accrue to the Group. All other property expenditure is expensed in the Group profit or loss as incurred.
Investment properties are valued by the external valuer. Any valuation of investment properties by the external valuer must be undertaken in accordance with the current issue of RICS Valuation – Professional Standards (the ‘Red Book’).
The determination of the fair value of investment property requires the use of estimates such as future cash flows from assets (such as lettings, tenants’ profiles, future revenue streams, capital values of fixtures and fittings, plant and machinery, any environmental matters and the overall repair and condition of the property) and yield applicable to those cash flows.
For the purposes of the financial statements, the assessed fair value is:
- reduced by the carrying amount of any accrued income resulting from the spreading of lease incentives; and
- increased by the carrying amount of leasehold obligations.
Investment property is derecognised when it has been disposed of or permanently withdrawn from use and no future economic benefit is expected after its disposal or withdrawal.
The profit on disposal is determined as the difference between the net sales proceeds and the carrying amount of the asset at the commencement of the accounting period plus capital expenditure in the period. Any gains or losses on the retirement or disposal of investment property are recognised in profit or loss in the year of retirement or disposal.
e) Cash and cash equivalents
Cash and short-term deposits in the Consolidated Statement of Financial Position comprise cash at bank and short-term deposits with an original maturity of three months or less.
f) Receivables and prepayments
Rent and other receivables are initially recognised at fair value and subsequently at amortised cost. Impairment provisions are recognised based on the process as described in Note 2.2. Any adjustment is recognised in profit or loss as an impairment gain or loss.
g) Other payables and accrued expenses
Other payables and accrued expenses are initially recognised at fair value and subsequently held at amortised cost.
h) Interest bearing loans and borrowings
All loans and borrowings are initially recognised at fair value less directly attributable transaction costs. After initial recognition, interest bearing loans and borrowings are subsequently measured at amortised cost using the effective interest method. Borrowing costs are included in the effective interest rate calculation.
i) Provisions
A provision is recognised in the Consolidated Statement of Financial Position when the Group has a present legal or constructive obligation as a result of a past event that can be reliably measured and is probable that an outflow of economic benefits will be required to settle the obligation. Provisions are determined by discounting the expected future cash flows at a pre-tax rate that reflects risks specific to the liability.
j) Dividend payable to shareholders
Dividends due to the Company’s Shareholders are recognised when they become legally payable, as a reduction in the Consolidated Statement of Changes in Equity. Interim equity dividends are recognised when paid. Final equity dividends will be recognised when approved by Shareholders at an AGM. The Directors consider the aggregate of distributable reserves in considering the recommendation and payment of a dividend.
k) Share issue costs
The costs of issuing or reacquiring equity instruments (other than in a business combination) are accounted for as a deduction from equity.
l) Lease obligations
Lease obligations relate to the head rent of investment property and are capitalised at the lease commencement, at the lower of fair value of the property and present value of the minimum lease payments and held as a liability within the Consolidated Statement of Financial Position. The lease payments are discounted using the interest rate implicit in the lease. Where the Group is exposed to potential future increases in variable lease payments based on an index or rate, these are not included in the lease liability until they take effect. Lease payments are allocated between principal and finance cost. The finance cost is charged to profit or loss over the lease period so as to produce a constant periodic rate of interest on the remaining balance of the liability for each period.
m) Taxes
Corporation tax is recognised in profit or loss except to the extent that it relates to items recognised directly in equity, in which case it is recognised in equity.
As a REIT, the Group is exempt from corporation tax on the profits and gains from its investments, provided it continues to meet certain conditions as per REIT regulations.
Taxation on the profit or loss for the period which is not exempted under UK REIT regulations comprises current and deferred tax. Current tax is expected tax payable on any non-REIT taxable income for the year, using tax rates applicable in the year.
Deferred tax is provided on temporary differences between the carrying amounts of assets and liabilities for financial reporting purposes and the amounts used for taxation purposes. The amount of deferred tax that is provided is based on the expected manner of realisation or settlement of the carrying amount of assets and liabilities, using tax rates enacted or substantially enacted at the period end date.
n) Non-current assets held for sale
Non-current assets are classified as assets held for sale when their carrying amount is to be recovered principally through a sale transaction and a sale is considered highly probable. Investment properties classified as such are measured at fair value.
o) European Public Real Estate Association (‘EPRA’)
The Group has adopted the EPRA best practice recommendations. For the year ended 30 June 2026, audited EPS and NAV calculations under EPRA’s methodology are included in Note 8 and further unaudited measures are included following the financial statements.
p) Capital and reserves
Share capital
Share capital is the nominal amount of the Company’s ordinary shares in issue and is non-distributable.
Capital reserve
The capital reserve represents the cancelled share premium less dividends paid from this reserve. It is a distributable reserve. The share premium account was cancelled in 2017 by Court Order and distributions can be made from this reserve in accordance with the Companies Act 2006, including by way of dividends or share buy backs.
Retained earnings
Retained earnings represent the cumulative net gains and losses recognised in the Consolidated Statement of Comprehensive Income less dividends paid from this reserve. This reserve is distributable, except for any unrealised gains on investment properties.
2.6 Fair value measurement
The Group measures financial and non-financial assets such as investment properties at fair value at each reporting date.
A number of the Group’s accounting policies and disclosures require the determination of fair value, for both financial and non-financial assets and liabilities. Fair value is defined in IFRS 13 Fair Value Measurement as the price that would be received to sell an asset or paid to transfer a liability in an orderly transaction between market participants at the measurement date. Fair values have been determined for measurement and/or disclosure purposes based on methods described below. Where applicable, further information about the assumptions made in determining fair values is disclosed in the notes specific to that asset or liability.
The Group uses valuation techniques that are appropriate in the circumstances and for which sufficient data are available to measure fair value, maximising the use of relevant observable inputs and minimising the use of unobservable inputs significant to fair value measurement as a whole:
Fair value hierarchy:
Level 1: Quoted prices (unadjusted) in active markets for identical assets or liabilities.
Level 2: Inputs other than quoted prices included within Level 1 that are observable for the asset or liability, either directly (i.e. as prices) or indirectly (i.e. derived from prices).
Level 3: Inputs for the asset or liability that are not based on observable market data (unobservable inputs).
For assets and liabilities that are recognised in the financial statements at fair value on a recurring basis, the Group determines whether transfers have occurred between levels in the hierarchy by re-assessing categorisation (based on the lowest level input that is significant to the fair value measurement as a whole) at the end of each reporting period.
There were no transfers between any of the levels during the year.
Investment property
The valuation of investment property by valuers engaged by the Group who are independently appointed and have the relevant professional qualifications and with recent experience in the location and category of the investment property being valued. Further information in relation to the valuers is provided in Note 10.
Property valuations are inherently subjective as they are made on the basis of assumptions made by the valuer which may not prove to be accurate. For these reasons, and consistent with EPRA’s guidance, the valuations of the property portfolio have been classified as Level 3 as defined by IFRS 13. The inputs to the valuations are defined as ‘unobservable’ by IFRS 13 and these are analysed in Note 10.
3. Rental and other income
| 2026 | 2025 |
| £’000 | £’000 |
Gross rental income* | 8,272 | 7,916 |
Spreading of minimum contracted future rent - indexation | 183 | 220 |
Spreading of tenant incentives - rent free periods | (138) | (214) |
Gross rental income (adjusted) | 8,317 | 7,922 |
Service charges and direct recharges (see Note 4) | 574 | 648 |
Total rental and other income | 8,891 | 8,570 |
All rental, service charges, direct recharges and other income are derived from the United Kingdom.
* Included in Gross rental income is a lease surrender premium of £335,000 (2025: £nil) which is non-recurring in nature.
4. Expenses
| 2026 | 2025 |
| £’000 | £’000 |
Property operating expenses | 136 | 133 |
Service charges and direct recharges (see Note 3) | 574 | 648 |
Provision for impairment of trade receivables | (1) | – |
Property operating expenses | 709 | 781 |
Investment Adviser fee | 380 | 360 |
Operating costs | 546 | 588 |
Exceptional corporate activity costs* | 732 | – |
Directors' remuneration (Note 5) | 126 | 118 |
Other operating expenses | 1,784 | 1,066 |
Total operating expenses | 2,493 | 1,847 |
Total operating expenses (excluding service charges and direct recharges) | 1,919 | 1,199 |
* During the year, the Company incurred £0.73 million (2025: £nil) of professional advisory, legal, corporate finance and other costs in connection with evaluating and responding to a number of unsolicited takeover and corporate proposals. These costs are non-recurring in nature.
| 2026 | 2025 |
| £’000 | £’000 |
Audit |
|
|
Statutory audit of Annual Report and Accounts | 79 | 84 |
Statutory audit of Subsidiary Accounts | 13 | 13 |
Statutory audit of Annual Report and Accounts (additional fee on data migration) | – | 7 |
Total fees due to auditor | 92 | 104 |
5. Directors’ remuneration
| 2026 | 2025 |
| £’000 | £’000 |
Directors' fees | 111 | 105 |
Tax | 14 | 12 |
Directors' expenses | 1 | 1 |
Total fees | 126 | 118 |
A summary of the director’s remuneration is set out in the Directors’ Remuneration Report in the Annual Report.
The Group had no employees during the year.
6. Finance expenses
| 2026 | 2025 |
| £’000 | £’000 |
Interest payable on loan (Note 13) | 1,850 | 1,307 |
Amortisation of finance costs (Note 13) | 174 | 128 |
Total | 2,024 | 1,435 |
Interest payable on loan consists of £1,452,000 to HSBC UK Bank Plc and £398,000 to Canada Life. Amortisation of finance costs consists of £129,000 with HSBC plc and £45,000 with Canada Life (2025: £128,000 with Canada Life).
7. Taxation
| 2026 | 2025 |
| £’000 | £’000 |
Analysis of tax charge in the year |
|
|
Profit before tax | 4,337 | 7,258 |
Theoretical tax charge at UK corporation tax standard rate of 25.00% (2025: 25.00%) | 1,084 | 1,815 |
Effects of tax-exempt items under the REIT regime | (1,084) | (1,815) |
Taxation for the year | – | – |
The Group maintained its REIT status and as such, no deferred tax asset or liability has been recognised in the current year.
Factors that may affect future tax charges
Due to the Group’s status as a REIT and the intention to continue meeting the conditions required to retain approval as a REIT in the foreseeable future, the Group has not provided deferred tax on any capital gains or losses arising on the revaluation or disposal of investments.
8. Earnings per share (‘EPS’)and Net Asset Value (‘NAV’) per share
| 2026 | 2025 |
EPS: |
|
|
Total comprehensive income (£’000) | 4,337 | 7,258 |
Weighted average number of shares (number) | 80,500,000 | 80,500,000 |
EPS (basic and diluted) | 5.39p | 9.02p |
EPRA EPS: |
|
|
Total comprehensive income (£’000) | 4,337 | 7,258 |
Adjustment to total comprehensive income (£’000): |
|
|
Change in fair value of investment properties | 350 | (1,970) |
Gain on disposal of investment property | (313) | – |
Adjustments for exceptional corporate activity costs | 732 | – |
EPRA earnings (basic and diluted) (£’000) | 5,106 | 5,288 |
EPRA EPS (basic and diluted) | 6.34p | 6.57p |
Adjusted EPS: |
|
|
EPRA earnings (basic and diluted) (£’000) – as above | 5,106 | 5,288 |
Adjustments (£'000): |
|
|
Rental income recognised in respect of guaranteed fixed rental uplifts (Note 3) | (183) | (220) |
Rental income recognised in respect of rent free periods (Note 3) | 138 | 214 |
Amortisation of loan finance costs (Note 6) | 174 | 128 |
Adjustments for exceptional corporate activity costs | (732) | – |
Provision/(reversal of provision) for impairment of trade receivables | (1) | – |
Adjusted earnings (basic and diluted) (£’000) | 4,502 | 5,410 |
Adjusted EPS (basic and diluted)* | 5.59p | 6.72p |
* Adjusted EPS is a measure used by the Board to assess the level of the Group’s dividend payments. This metric adjusts EPRA earnings for non-cash items in arriving at an adjusted EPS as supported by cash flows.
Earnings per share are calculated by dividing profit/(loss) for the year attributable to ordinary equity holders of the Company by the weighted average number of Ordinary Shares in issue during the year. As at 30 June 2026 and 2025, there are no dilutive or potentially dilutive equity instruments in existence.
| 2026 | 2025 |
NAV per share: |
|
|
Net assets (£'000) | 67,035 | 67,327 |
Ordinary Shares (Number) | 80,500,000 | 80,500,000 |
NAV per share | 83.27p | 83.64p |
EPRA Net Reinstatement Value (‘NRV’), EPRA Net Tangible Assets (‘NTA’) and EPRA Net Disposal Value (‘NDV’)
| EPRA NRV | EPRA NTA and EPRA NDV |
At 30 June 2026 |
|
|
Net assets value (£'000) | 67,035 | 67,035 |
Estimated purchasers' cost (£'000) | 6,702 | – |
| 73,737 | 67,035 |
Ordinary Shares (Number) | 80,500,000 | 80,500,000 |
Per share measure | 91.60p | 83.27p |
At 30 June 2025 |
|
|
Net assets value (£'000) | 67,327 | 67,327 |
Estimated purchasers' cost (£'000) | 6,978 | – |
| 74,305 | 67,327 |
Ordinary Shares (Number) | 80,500,000 | 80,500,000 |
Per share measure | 92.30p | 83.64p |
9. Dividends
All dividends were paid as PIDs | QuarterEnded | Rate | 2026£’000 | 2025£’000 |
Dividends in respect of year ended 30 June 2024 |
|
|
|
|
4th dividend | 30-Jun-24 | 1.625p | – | 1,308 |
Dividends in respect of year ended 30 June 2025 |
|
|
|
|
1st dividend | 30-Sep-24 | 1.550p | – | 1,248 |
2nd dividend | 31-Dec-24 | 1.550p | – | 1,248 |
3rd dividend | 31-Mar-25 | 1.550p | – | 1,248 |
4th dividend | 30-Jun-25 | 1.550p | 1,248 | – |
Dividends in respect of year ended 30 June 2026 |
|
|
|
|
1st dividend | 30-Sep-25 | 1.400p | 1,127 | – |
2nd dividend | 31-Dec-25 | 1.400p | 1,127 | – |
3rd dividend | 31-Mar-26 | 1.400p | 1,127 | – |
Total dividends paid |
|
| 4,629 | 5,052 |
4th dividend* | 30-Jun-24 | 1.625p | – | (1,308) |
4th dividend* | 30-Jun-25 | 1.550p | (1,248) | 1,248 |
4th dividend* | 30-Jun-26 | 1.400p | 1,127 | – |
Total dividends payable in respect of the year |
|
| 4,508 | 4,992 |
Total dividends payable per share in respect of the year |
|
| 5.60p | 6.20p |
* Dividends declared after the year end are not included in the financial statements as a liability.
10. Investment properties
| 2026 | 2025 | ||
| FreeholdInvestmentproperties£’000 | LeaseholdInvestmentproperties£’000 | Total£’000 | Total£’000 |
At the beginning of the year | 75,250 | 32,100 | 107,350 | 102,650 |
(Disposal)/acquisition during the year | (4,000) | – | (4,000) | 2,724 |
Change in value of investment properties | (65) | (175) | (240) | 1,976 |
Valuation provided by Knight Frank LLP | 71,185 | 31,925 | 103,110 | 107,350 |
Adjustment to fair value for minimum rent indexation of lease income (Note 11) | (3,683) | (3,573) | ||
Total investment properties | 99,427 | 103,777 | ||
Change in fair value of investment properties |
|
| ||
Change in fair value before adjustments for lease incentives and lease obligations | (240) | 1,976 | ||
Adjustment to spreading of contracted future rent indexation and tenant incentives | (110) | (6) | ||
| (350) | 1,970 | ||
Disposal and acquisition of investment property
The property known as Crawley was sold in October 2025 for £4.5 million as shown in the reconciliation below of the gain recognised on disposal through the Condensed Consolidated Statement of Comprehensive Income; the gain on disposal includes changes in fair value of the investment property and minimum rent indexation spreading recognised in previous periods.
| 2026 | 2025 |
| £’000 | £’000 |
Gross proceeds on disposal | 4,500 | – |
Selling costs | (36) | – |
Net proceeds on disposal | 4,464 | – |
Carrying value | (4,000) | – |
Minimum rent indexation spreading recognised in previous periods | (151) | – |
Gain on disposal of investment property | 313 | – |
There were no property acquisitions in the year.
Valuation of investment properties
Valuation of investment properties is performed by Knight Frank LLP, an accredited external valuer with recognised and relevant professional qualifications and recent experience of the location and category of the investment property being valued. The valuation of the Group’s investment properties at fair value is determined by the external valuer on the basis of market value in accordance with the internationally accepted RICS Valuation – Professional Standards (incorporating the International Valuation Standards).
The determination of the fair value of investment properties requires the use of estimates such as future cash flows from assets (such as lettings, tenants’ profiles, future revenue streams, capital values of fixtures and fittings, plant and machinery, any environmental matters and the overall repair and condition of the property) and yield applicable to those cash flows.
Sensitivity analysis to significant changes in unobservable inputs within Level 3 of the fair value hierarchy
The significant unobservable inputs used in the fair value measurement categorised within Level 3 of the fair value hierarchy of the entity’s portfolios of investment properties are:
Estimated Rental Value (‘ERV’)Net Initial YieldIncreases/(decreases) in the ERV (per sq. ft. per annum) in isolation would result in a higher/(lower) fair value measurement. Increases/(decreases) in the yield in isolation would result in a lower/(higher) fair value measurement.
The significant unobservable inputs used in the fair value measurement, categorised within Level 3 of the fair value hierarchy of the portfolio of investment property and investments are:
Class | Fairvalue£’000 | Valuationtechnique | Significant unobservable inputs | Range |
30 June 2026 |
|
|
|
|
Investment Properties* | 103,110 | Incomecapitalisation | ERVNet Initial yield | £5.25 - £21.966.01% - 9.27%** |
30 June 2025 |
|
|
|
|
Investment Properties* | 107,350 | Incomecapitalisation | ERVNet Initial yield | £4.00 - £21.964.87% - 8.70%** |
* Valuation per Knight Frank LLP.
** Hotels, petrol stations, residential and healthcare are excluded from this range.
Sensitivity analysis below:
| 2026 | |||
| Change in ERV | Change in net initial yield | ||
| £’000 | £’000 | £’000 | £’000 |
Sensitivity Analysis | +10% | -10% | +10% | -10% |
Resulting fair value of investment properties | 105,586 | 100,144 | 96,090 | 110,708 |
| 2025 | |||
| Change in ERV | Change in net initial yield | ||
| £’000 | £’000 | £’000 | £’000 |
Sensitivity Analysis | +10% | -10% | +10% | -10% |
Resulting fair value of investment properties | 109,634 | 104,628 | 100,661 | 115,042 |
11. Trade and other receivables
| 2026 | 2025 |
| £’000 | £’000 |
Receivables |
|
|
Trade receivables | 478 | 290 |
Less: Provision for impairment of trade debtors | (1) | (2) |
Other debtors | 257 | 192 |
| 734 | 480 |
Spreading of minimum contracted future rent indexation | 3,509 | 3,426 |
Spreading of tenant incentives – rent free periods and capital contributions | 174 | 147 |
| 3,683 | 3,573 |
Tenant deposit asset (Note 12) | – | 118 |
Other prepayments | 105 | 65 |
| 105 | 183 |
Trade and other receivables | 4,522 | 4,236 |
The aged debtor analysis of receivables which are past due but not impaired is as follows:
| 2026 | 2025 |
| £’000 | £’000 |
Less than three months due | 705 | 476 |
Between three and six months due | 29 | 4 |
| 734 | 480 |
12. Trade and other payables
| 2026 | 2025 |
| £’000 | £’000 |
Deferred income | 1,683 | 1,654 |
Trade creditors | 328 | 55 |
Accruals | 700 | 439 |
Tenant deposit liability (Note 11) | – | 118 |
Loan interest payable (Note 13) | 393 | 256 |
Other creditors | 337 | 356 |
Total trade and other payables | 3,441 | 2,878 |
13. Interest bearing loans and borrowings
| 2026 | 2025 |
| £’000 | £’000 |
Facility drawn | 41,000 | 41,000 |
Repayment of Canada Life loan facility | (41,000) | – |
HSBC term loan | 31,000 | – |
HSBC RCF drawdown | 10,000 | – |
Total loan drawn | 41,000 | 41,000 |
Repayment of HSBC RCF | (4,416) | – |
Total loan outstanding | 36,584 | 41,000 |
Unamortised finance costs brought forward | (44) | (172) |
Refinancing costs | (934) | – |
Amortisation of finance costs (Note 6) | 174 | 128 |
At end of year | 35,780 | 40,956 |
Repayable less than one year | – | 41,000 |
Repayable between one and two years | – | – |
Repayable between two and five years | 36,584 | – |
Total at end of the year | 36,584 | 41,000 |
At the year end, the Group had utilised £36.58 million of its loan facilities with HSBC UK Bank Plc (30 June 2025: £41.0 million). The loans outstanding comprise a term loan of £31.0 million plus £5.6 million of RCF. The total RCF which is available is £10.0 million of which £4.4 million was repaid following the sale of Crawley. The debt is repayable on 20 October 2030.
The loan facilities are geared at a loan to Gross Asset Value (‘GAV’) of 34.4% (30 June 2025: 36.9%). The interest rate for the year was on average 4.76%. The interest payable on the HSBC facilities was on average 5.45% (margin of 1.7% plus SONIA in the period 20 October to 30 June 2026) and the interest payable on the Canada Life loan to 20 October 2025 was at a fixed rate of 3.19%. Interest expense incurred during the period amounted to £1.85 million (30 June 2025: £1.31 million), £0.39 million of which is outstanding (30 June 2025: £0.26 million). The interest payable on the HSBC facilities are paid quarterly on the 20th of January, April, July and October.
Amortisation of finance costs are recognised through the effective interest method over the expected life of the loan facilities to 20 October 2030.
Under the terms of the HSBC debt facilities the Loan to Value (‘LTV’) covenant is not to exceed 60% (30 June 2025: should not exceed 50%) and the Interest Cover Ratio (‘ICR’) to be greater than 160% for cash trap and 150% for default ICR (30 June 2025: ICR to be greater than 330%).
Whilst there is no present intention, AIRE has the right, through an accordion mechanism, to request an increase in the size of the RCF by up to a further £10 million, over the course of the facility.
| 2026 | 2025 |
| £’000 | £’000 |
Reconciliation to cash flows from financing activities |
|
|
At beginning of the year | 40,956 | 40,828 |
|
|
|
Repayment of Canada Life loan facility | (41,000) | – |
HSBC term loan | 31,000 | – |
HSBC RCF drawdown | 10,000 | – |
Repayment of HSBC RCF | (4,416) | – |
Refinancing costs | (934) | – |
Total cash changes | (5,350) | – |
Non-cash changes |
|
|
Amortisation of loan issue costs | 174 | 128 |
Total at end of the year | 35,780 | 40,956 |
14. Commitments
14.1. Operating lease commitments – as lessor
The Group has 19 commercial properties with 33 units in its investment property portfolio (2025: 20 commercial properties with 34 units). These non-cancellable leases have a remaining term of between 9 months and 108 years (2025: 21 months to 109 years), excluding ground leases.
Future minimum rentals receivable under non-cancellable operating leases as at the year-end are as follows:
| 2026 | 2025 |
| £’000 | £’000 |
Within one year | 10,677 | 8,878 |
After one year, but not more than two years | 5,166 | 6,182 |
After two years, but not more than three years | 6,030 | 5,938 |
After three years, but not more than four years | 6,060 | 6,017 |
After four years, but not more than five years | 6,071 | 6,060 |
After five years, but not more than ten years | 25,358 | 26,703 |
After ten years, but not more than fifteen years | 19,083 | 20,668 |
More than fifteen years | 40,932 | 44,326 |
| 119,377 | 124,772 |
During the year ended 30 June 2026 there were no material contingent rents recognised as income (2025: nil).
14.2. Capital and financial commitments
There were no capital or financial commitments at the year-end (2025: nil).
15. Investments in subsidiaries
The Company has two wholly owned subsidiaries as disclosed below:
Name and company number | Country of registration and incorporation | Dateofincorporation | Principalactivity | OrdinarySharesheld |
Alternative Income REIT Holdco Limited (Company number 11052186) | England andWales | 7 Nov 2017 | Real Estate Company | 73,158,502* |
Alternative Income Limited (Company number 10754641) | England andWales | 4 May 2017 | Real Estate Company | 73,158,501* |
* Ordinary shares of £1.00 each.
Alternative Income REIT PLC owns 100% of Alternative Income REIT Holdco Limited.
Alternative Income REIT Holdco Limited owns 100% of Alternative Income Limited.
Both Alternative Income REIT Holdco Limited and Alternative Income Limited are registered at The Scalpel, 18th Floor, 52 Lime Street, London, United Kingdom, EC3M 7AF.
16. Issued share capital and reserves
|
| 2026 |
| 2025 |
| £’000 | Number ofOrdinary Shares | £’000 | Number ofOrdinaryShares |
Ordinary Shares of £0.01 each issued and fully paid |
|
|
|
|
At the beginning and end of the year | 805 | 80,500,000 | 805 | 80,500,000 |
17. Financial risk management and policies
The Group’s activities expose it to a variety of financial risks: market risk, credit risk, liquidity risk and further risks inherent to investing in investment property. The Group has limited exposure to foreign currency risk as most of its transaction is in Sterling. The Group’s objective in managing risk is the creation and protection of shareholder value. Risk is inherent in the Group’s activities, but it is managed through a process of ongoing identification, measurement and monitoring, subject to risk limits and other controls. The principal risks facing the Group in the management of its portfolio follows:
17.1 Market price risk
Market price risk is the risk that future values of investments in property will fluctuate due to changes in market prices. To manage market price risk, the Group diversifies its portfolio geographically in the UK and across property sectors.
The disciplined approach to the purchase, sale and asset management ensures that the value is maintained to its maximum potential. Prior to any property acquisition or sale, detailed research is undertaken to assess expected future cash flow. The Board and the Investment Adviser meet regularly and are responsible for recommending investment purchases or sales to the AIFM which makes the ultimate decision. In order to monitor property valuation fluctuations, the Investment Adviser meets with the independent external valuer on a regular basis. The valuer provides a property portfolio valuation quarterly, so any movements in the value can be accounted for in a timely manner and reflected in the NAV every quarter.
17.2 Real estate risk
Property investments are illiquid assets and can be difficult to sell, especially if local market conditions are poor. Illiquidity may also result from the absence of an established market for investments, as well as legal or contractual restrictions on resale of such investments.
There can be no certainty regarding the future performance of any of the properties acquired for the Group. The value of any property can go down as well as up.
Real property investments are subject to varying degrees of risk. The yields available from investments in real estate depend on the amount of income generated and expenses incurred from such investments.
There are additional risks in vacant, part vacant, redevelopment and refurbishment situations, although these are not prospective investments for the Group.
These aspects, and their effect on the Group from a going concern perspective are discussed in more detail in the Going Concern policy note.
17.3 Credit risk
Credit risk is the risk that the counterparty (to a financial instrument) or tenant (of a property) will cause a financial loss to the Group by failing to meet a commitment it has entered into with the Group.
It is the Group’s policy to enter into financial instruments with reputable counterparties. All cash deposits are placed with an approved counterparty, Barclays International.
In respect of property investments, in the event of a default by a tenant, the Group will suffer a rental shortfall and additional costs concerning re-letting the property. The Investment Adviser monitors tenant arrears in order to anticipate and minimise the impact of defaults by occupational tenants.
The table below shows the Group’s exposure to credit risk:
| 2026 | 2025 |
| £’000 | £’000 |
Debtors | 735 | 482 |
Cash and cash equivalents | 2,307 | 3,148 |
Total | 3,042 | 3,630 |
17.4 Liquidity risk
Liquidity risk arises from the Group’s management of working capital and the finance charges and principal repayments on its borrowings. It is the risk the Group will encounter difficulty in meeting its financial obligations as they fall due as the majority of the Group’s assets are investment properties and therefore not readily realisable. The Group’s objective is to ensure it has sufficient available funds for its operations and to fund its capital expenditure. This is achieved by quarterly review/monitoring of forecast and actual cash flows by the Investment Adviser and Board.
The below table summarises the maturity profile of the Group’s financial liabilities based on contractual undiscounted payments.
2026 | Ondemand£’000 | < 3months£’000 | 3 - 12months£’000 | 1 - 5years£’000 | Total£’000 |
Interest bearing loans and borrowings | – | – | – | 36,584 | 36,584 |
Interest payable | – | 530 | 1,627 | 7,094 | 9,251 |
Payables and accrued expenses | 328 | 976 | – | – | 1,304 |
Total | 328 | 1,506 | 1,627 | 43,678 | 47,139 |
2025 | Ondemand£’000 | < 3months£’000 | 3 - 12months£’000 | 1 - 5years£’000 | Total£’000 |
Interest bearing loans and borrowings | – | – | 41,000 | – | 41,000 |
Interest payable | – | 327 | 327 | – | 654 |
Payables and accrued expenses | 55 | 727 | – | – | 782 |
Total | 55 | 1,054 | 41,327 | – | 42,436 |
17.5 Fair value of financial instruments
There is no material difference between the carrying amount and fair value of the Group’s financial instruments.
17.6 Interest rate risk
Interest rate risk is the risk that future cash flows of a financial instrument will fluctuate because of changes in market interest rates. The Group is exposed to the risk of changes in market interest rates because the Group’s loan is at a variable rate. Both the HSBC loan and RCF have a margin of 1.7% per annum plus SONIA (sterling overnight index average rate) (Note 13).
The sensitivity analysis illustrates the estimated impact on annual interest expense arising from reasonable possible changes in market interest rates. Movements of 1% and 2% have been presented as they represent both typical and more severe but plausible changes in interest rates. Based on the Group’s variable-rate borrowings of approximately £36.6 million, a 1% increase/(decrease) in interest rates would increase/(decrease) annual loan interest expense by £366k, while a 2% increase/(decrease) would increase/(decrease) annual loan interest expense by £732k.
Sensitivity analysis below:
| 2026 | |||
| Change in interest rate | Change in interest rate | ||
| £’000 | £’000 | £’000 | £’000 |
Interest rate risk | +1% | -1% | +2% | -2% |
Interest expense | 366 | (366) | 732 | (732) |
18. Capital management
The Group’s objectives when managing capital are to safeguard the Group’s ability to continue as a going concern in order to provide returns for shareholders and to maintain an optimal capital structure to reduce the cost of capital.
To enhance returns over the medium term, the Group utilises borrowings on a limited recourse basis for each investment or all or part of the total portfolio. The Group’s policy is to borrow up to a maximum of 40% loan to GAV (measured at drawdown). Alongside the Group’s borrowing policy, the directors intend, at all times, to conduct the affairs of the Group so as to enable the Group to qualify as a REIT for the purposes of Part 12 of the Corporation Tax Act 2010 (and the regulations made thereunder). The REIT status compliance requirements include 90% distribution test, interest cover ratio, 75% assets test and the substantial shareholder rule, all of which the Group remained compliant in both this and the prior year.
The monitoring of the Group’s level of borrowing is performed primarily using a Loan to GAV ratio. The Loan to GAV ratio is an alternative performance measure and its calculation is shown below. The Group Loan to GAV ratio at the year-end was 34.4% (2025: 36.9%).
Breaches in meeting the financial covenants would permit the lender to immediately call loans and borrowings. During the year, the Group did not breach any of its loan covenants, nor did it default on any other of its obligations under its loan agreements.
19. Transactions with related parties and the Investment Adviser
Parties are considered to be related if one party has the ability to control the other party or exercise significant influence over the other party in making financial or operational decisions.
Directors
Directors are considered to be related parties. Their fees and interests in shares are disclosed in the Remuneration Report in the Annual Report.
Investment Adviser
The Group’s Investment Adviser is Martley Capital Real Estate Investment Management Ltd (‘Martley Capital’) and has been since 15 March 2024. For the period to 31 December 2025, the annual management fee is calculated at a rate equivalent of 0.50% per annum of NAV (subject to a minimum fee of £90,000 per quarter), payable quarterly in advance.
For the period from 1 January 2026, the annual management fee is calculated at a rate equivalent of 0.50% per annum of NAV (subject to a minimum of £100,000 per quarter), payable quarterly in advance. This fee is subject to an annual increase from 1 January each year in line with the percentage change in the Retail Prices Index (RPI) published by the UK Office for National Statistics subject to a minimum annual increase of 3% and a maximum annual increase of 5%.
During the year the Group incurred £380,000 in respect of investment advisory fees to Martley Capital (2025: £360,000). No amounts were accrued at the year-end (2025: £ nil).
20. Events after the reporting date
On 12 June 2026, Glenstone announced a cash offer to acquire the entire issued and to be issued ordinary share capital of AIRE that the Glenstone Group does not already hold at 70.0 pence in cash for each AIRE Share, to be implemented by means of a takeover offer. On 9 September 2026 the Glenstone offer became unconditional with 50.42% of AIRE shareholders accepting the Glenstone offer at 70 pence per share. On this date the Board recommended that the Glenstone offer be accepted so shareholders realise 70 pence per share. As at 27 October 2026 this acceptance level had increased to 87.08%.
Following the Glenstone offer becoming unconditional on 9 September 2026, resulting in a change of control of the Group, HSBC issued a Reservation of Rights letter. On 28 October 2026, AIRE and HSBC entered into a waiver and amendment letter to the Facility Agreement, pursuant to which HSBC consented to the change of control and the Company’s subsequent de-listing from the London Stock Exchange, agreed to continue funding future utilisations and waived any right to require repayment of amounts outstanding as a result of, or in connection with, the change of control.
On 1 October 2026 the Group drew down an additional £1.0 million under the RCF to fund additional corporate costs as a result of the corporate activity. The total RCF drawn as at 1 October amounted to £6.6 million leaving £3.4 million to be drawn as required.
Company Statement of Financial Position
As at 30 June 2026
| 2026 | 2025 | |
| Notes | £’000 | £’000 |
Assets |
|
|
|
Non-current Assets |
|
|
|
Investments in subsidiary companies | 2 | 73,158 | 73,158 |
Investment property | 2 | 1,593 | 1,746 |
Total non-current assets |
| 74,751 | 74,904 |
Current Assets |
|
|
|
Receivables and prepayments | 3 | 172 | 121 |
Cash and cash equivalents |
| 53 | 128 |
Total current assets |
| 225 | 249 |
Total Assets |
| 74,976 | 75,153 |
Current Liabilities |
|
|
|
Payables and accrued expenses | 4 | (13,546) | (7,307) |
Net Assets |
| 61,430 | 67,846 |
Equity |
|
|
|
Share capital | 6 | 805 | 805 |
Capital reserve | 2 | 60,750 | 65,379 |
(Accumulated losses)/Retained earnings | (125) | 1,662 | |
Total capital and reserves attributable to equity holders of the Company | 61,430 | 67,846 | |
Net Asset Value per share |
| 76.31p | 84.28p |
As permitted by s408 Companies Act 2006, the Company’s profit and loss account has not been presented in these financial statements.
The Company’s loss for the year was £1,787,000 (2025: profit of £12,051,000).
The financial statements were approved by the Board on 28 October 2026 and were signed on its behalf by:
Adam Smith
Chairman
Company number: 10727886
The accompanying Notes 1 to 7 form an integral part of these financial statements.
Company Statement of Changes in Equity
For the year ended 30 June 2026
| Sharecapital£’000 | Capitalreserve£’000 | Retainedearnings£’000 | Totalequity£’000 |
For the year ended 30 June 2026 |
|
|
|
|
Balance at 30 June 2025 | 805 | 65,379 | 1,662 | 67,846 |
Total comprehensive loss | – | – | (1,787) | (1,787) |
Dividends paid | – | (4,629) | – | (4,629) |
Balance at 30 June 2026 | 805 | 60,750 | (125) | 61,430 |
For the year ended 30 June 2025 |
|
|
|
|
Balance at 30 June 2024 | 805 | 70,431 | (10,389) | 60,847 |
Total comprehensive income | – | – | 12,051 | 12,051 |
Dividends paid | – | (5,052) | – | (5,052) |
Balance at 30 June 2025 | 805 | 65,379 | 1,662 | 67,846 |
The accompanying Notes 1 to 7 form an integral part of these financial statements.
Notes to the Company Financial Statements
For the year ended 30 June 2026
1. Accounting policies
Basis of preparation
These financial statements are prepared and approved by the directors in accordance with Financial Reporting Standard 101 Reduced Disclosure Framework (‘FRS 101’) and in accordance with applicable accounting standards.
As permitted by FRS 101, the Company has taken advantage of the following disclosure exemptions which are permissible under FRS 101 as the equivalent disclosures are contained within the Group’s consolidated financial statements.
- a cash flow statement and related notes;
- disclosures in respect of capital management;
- the effects of new but not yet effective IFRSs;
- the disclosures of the remuneration of key management personnel;
- disclosure of related party transactions with other wholly owned members of the Ultimate Parent;
- the disclosure of financial instruments and other fair value measurements.
The financial statements are presented in Pound Sterling (£) and all values are rounded to the nearest thousand pounds (£’000), except when otherwise indicated. They have been prepared on the historical cost basis, with the exception of investment properties.
The principal accounting policies adopted in the preparation of the Company’s financial statements are consistent with the Group which are described in Note 2.5 of the Consolidated Financial Statements but makes amendments where necessary in order to comply with the Companies Act 2006 and taking advantage of the FRS 101 exemptions mentioned above.
New standards effective for the current accounting period do not have a material impact on the financial statements of the Company.
The accounting policies used are otherwise consistent with those contained in the Company financial statements for the year ended 30 June 2026.
Going concern
The financial statements have been prepared on a going concern basis.
For an assessment of going concern refer to the accounting policy 2.4 of the Consolidated Financial Statements.
Investments in subsidiary companies
Investments in subsidiary companies which are all 100% owned by the Company are included in the statement of financial position at cost less provision for impairment.
Impairment of non-financial assets
The carrying amounts of the Company’s investment in subsidiaries are reviewed at each reporting date to determine whether there is any indication of impairment. If any such indication exists, then the asset’s recoverable amount is estimated. The recoverable amount of an asset is the greater of its value in use and its fair value less costs to sell.
An impairment loss is recognised if the carrying amount of an asset exceeds its estimated recoverable amount. Impairment losses are recognised in profit or loss.
Impairment losses recognised in prior periods are assessed at each reporting date for any indications that the loss has decreased or no longer exists. An impairment loss is reversed if there has been a change in the estimates used to determine the recoverable amount. An impairment loss is reversed only to the extent that the asset’s carrying amount does not exceed the carrying amount that would have been determined, net of depreciation or amortisation, if no impairment loss had been recognised.
Deferred income
Deferred income is rental income received in respect of future accounting periods.
2. Investments
2a. Investments in Subsidiary Companies
| 2026 | 2025 |
| £’000 | £’000 |
At the beginning and end of the year | 73,158 | 73,158 |
A list of subsidiary undertakings at 30 June 2026 is included on Note 15 of the Consolidated Financial Statements.
The directors have considered the recoverability of the investment in subsidiary companies by comparing the carrying value of the investment to the net asset value of the subsidiaries. The directors consider the net asset value of the subsidiary to be a reliable proxy to the recoverable amount as the properties held by the Company are carried at fair value. The net asset value of the subsidiary companies exceed the carrying amount of the investment in subsidiaries and the directors have concluded that no impairment is necessary.
2b. Investment property
| 2026 | 2025 |
| £’000 | £’000 |
At the beginning of the year | 1,746 | 1,803 |
Revaluation of investment property | (150) | (50) |
Adjustment to fair value for minimum rent indexation of lease income | (3) | (7) |
| 1,593 | 1,746 |
3. Receivables and prepayments
| 2026 | 2025 |
| £’000 | £’000 |
Spreading of contracted future – rent indexation | 82 | 82 |
Other prepayments | 48 | 39 |
Trade receivables | 42 | – |
| 172 | 121 |
4. Payables and accrued expenses
| 2026 | 2025 |
| £’000 | £’000 |
Due to subsidiaries | 12,549 | 6,830 |
Deferred income | – | 34 |
Trade creditors | 307 | 4 |
Accruals | 600 | 358 |
Other creditors | 90 | 81 |
| 13,546 | 7,307 |
Amounts due to subsidiaries are unsecured, interest free and repayable on demand.
5. Dividends paid and payable
Details of dividends paid and payable in respect of the year are set out in Note 9 of the consolidated financial statements.
6. Issued share capital
|
| 2026 |
| 2025 |
| £’000 | Number ofOrdinary Shares | £’000 | Number ofOrdinaryShares |
Ordinary Shares of £0.01 each issued and fully paid |
|
|
|
|
At the beginning and end of the year | 805 | 80,500,000 | 805 | 80,500,000 |
7. Contingent liabilities, capital commitments and related party transactions
As at 30 June 2026 the Company had no contingent liabilities or capital commitments (2025: nil).
Related party transactions are the same for the Company as for the Group. For details refer to Note 19 of the Consolidated Financial Statements.
General
EPRA Performance Measures (Unaudited)
| 2026 | 2025 | |
EPRA Yield calculations |
| £’000 | £’000 |
Investment properties wholly owned: |
|
|
|
– by Company |
| 1,675 | 1,825 |
– by Alternative Income Limited |
| 101,435 | 105,525 |
Total – Note 10 |
| 103,110 | 107,350 |
Allowance for estimated purchasers’ costs (Note 8) |
| 6,702 | 6,978 |
Gross up completed property portfolio valuation | B | 109,812 | 114,328 |
|
|
|
|
Annualised cash passing rental income |
| 7,968 | 8,084 |
Annualised property outgoings |
| (5) | (5) |
Annualised net rents | A | 7,963 | 8,079 |
|
|
|
|
Add: notional rent expiration of rent-free periods or other lease incentives |
| – | 212 |
Topped-up net annualised rent | C | 7,963 | 8,291 |
|
|
|
|
EPRA NIY | A/B | 7.25% | 7.07% |
EPRA ‘topped-up’ NIY | C/B | 7.25% | 7.25% |
| 2026 | 2025 | |
EPRA Cost Ratios |
| £’000 | £’000 |
Include: |
|
|
|
EPRA Costs (including direct vacancy costs) (Note 4) | A | 1,199 | 1,204 |
Direct vacancy costs |
| – | – |
EPRA Costs (excluding direct vacancy costs) | B | 1,919 | 1,199 |
Gross rental income (adjusted) (Note 3) | C | 8,317 | 7,922
|
EPRA Cost Ratio (including direct vacancy costs) | A/C | 23.07% | 15.14% |
EPRA Cost Ratio (excluding direct vacancy costs) | B/C | 23.07% | 15.14% |
There were no overheads nor operating expenses capitalised in the year in line with IFRS (2025: nil).
| 2026 | 2025 | |
EPRA Vacancy rate |
| £’000 | £’000 |
Annualised potential rental value of vacant premises | A | – | – |
Annualised potential rental value for the completed property portfolio | B | 7,330 | 7,337
|
EPRA Vacancy rate | A/B | 0.00% | 0.00% |
The Group has not incurred any direct vacancy costs in both the current or prior years.
| 2026 | 2025 | |
EPRA LTV |
| £’000 | £’000 |
Gross debt drawn |
| 36,584 | 41,000 |
Less: cash and cash equivalents |
| (2,307) | (3,148) |
Net debt | A | 34,277 | 37,852 |
|
|
|
|
Investment property at fair value (Note 10) |
| 103,110 | 107,350 |
Trade and other receivables (Note 11) |
| 4,470 | 4,236 |
Less: Trade and other payables (Note 12) |
| (3,389) | (2,878) |
Total Property Value | B | 104,191 | 108,708 |
|
|
|
|
EPRA LTV | A/B | 32.90% | 34.82% |
| 2026 | 2025 | |
EPRA Property-related Capital Expenditure |
| £’000 | £’000 |
Acquisitions including incidental costs of purchase and tenant incentives (Note 10) | – | 2,724 | |
Total capital expenditure |
| – | 2,724 |
Conversion from accruals to cash basis |
| – | – |
Total capital expenditure on a cash basis |
| – | 2,724 |
Group has no Joint Ventures so there is no joint venture property to disclose in the above.
Alternative Performance Measures (APMs) (Unaudited)
APMs are numerical measures of the Group’s current, historical or future performance, financial position or cash flows, other than financial measures defined or specified in the applicable financial framework. The Group’s applicable financial framework is IFRS. The directors assess the Group’s performance against a range of criteria which are reviewed by investors as particularly relevant for a closed-end REIT.
Discount
The discount is the amount by which the share price is lower than the net asset value per share, expressed as a percentage of the net asset value per share.
| 2026 | 2025 | |
NAV per Ordinary Share | A | 83.27p | 83.64p |
Share price | B | 69.20p | 74.00p |
Discount | (A-B)/A | 16.90% | 11.52% |
Dividend Cover
The ratio of Group’s Adjusted EPS divided by the Group’s dividends payable for the relevant year.
| 2026 | 2025 | |
Adjusted EPS | A | 5.59p | 6.72p |
Dividend per share | B | 5.60p | 6.20p |
Dividend cover | A/B | 99.82% | 108.37% |
Dividend Yield
The ratio of Group’s annual dividends per share divided by the Group’s share price for the relevant year.
| 2026 | 2025 | |
Annual dividends paid | A | 5.60p | 6.20p |
Share price | B | 69.20p | 74.00p |
Dividend yield | A/B | 8.09% | 8.38% |
Loan to GAV
Loan to GAV measures the value of loans and borrowings utilised (excluding amounts held as restricted cash and before adjustments for issue costs) expressed as a percentage of the combined valuation of the property portfolio (as provided by the valuer) and the fair value of other assets.
| 2026 | 2025 | |
Borrowings (£’000) | A | 36,584 | 41,000 |
Total assets (£’000) | B | 106,256 | 111,161 |
Loan to GAV | A/B | 34.43% | 36.88% |
Ongoing Charges
The ongoing charges ratio is the total for all operating costs expected to be regularly incurred expressed as a percentage of the average quarterly NAVs of the Group for the financial year.
| 2026 | 2025 | |
Other operating expenses for the year (£’000) | A | 1,784 | 1,066 |
Adjustments for exceptional corporate activity costs (£’000) | B | (732) | – |
One-off legal fees (£’000) | C | (10) | (26) |
Abortive property acquisition costs (£’000) | D | (12) | (2) |
| E=A+B+C+D | 1,030 | 1,038 |
Average net assets (£’000) | F | 67,592 | 66,139 |
Ongoing charges ratio | E/F | 1.52% | 1.57% |
Share Price and Net Asset Value (NAV) Total Return
Share price and NAV total returns show how the NAV and share price has performed over a period of time in percentage terms, taking into account both capital returns and dividends paid to shareholders. Share price and NAV total returns are monitored against FTSE EPRA Nareit UK and FTSE Small Cap, respectively.
| Share price | NAV | |
Opening at 30 June 2025 | A | 74.00p | 83.64p |
Closing at 30 June 2026 | B | 69.20p | 83.27p |
Return | C=(B/A)-1 | -6.49% | -0.44% |
Dividend reinvestment* | D | 7.77% | 6.88% |
Total return for the year ended 30 June 2026 | C+D | 1.28% | 6.44% |
|
|
|
|
Opening at 30 June 2024 | A | 66.00p | 80.90p |
Closing at 30 June 2025 | B | 74.00p | 83.64p |
Return | C=(B/A)-1 | 12.12% | 3.38% |
Dividend reinvestment* | D | 9.51% | 7.76% |
Total return for the year ended 30 June 2025 | C+D | 21.63% | 11.14% |
* Share price total return involves reinvesting the net dividend in the share price of the Company on the date on which that dividend goes ex-dividend. NAV total return involves investing the net dividend in the NAV of the Company with debt at fair value on the date on which that dividend goes ex-dividend.
Glossary
Adjusted Earnings Per Share (‘Adjusted EPS’) | Adjusted earnings per share excludes change in fair value of investment properties, profit or losses on disposal of investment properties and other non-cash items. It includes non-recurring expenses. |
Alternative Investment Fund Manager or AIFM or Investment Manager | Langham Hall Fund Management LLP. |
Company | Alternative Income REIT PLC. |
Contracted rent | The annualised rent adjusting for the inclusion of rent subject to rent-free periods. |
Earnings Per Share (‘EPS’) | Profit for the period attributable to equity shareholders divided by the weighted average number of Ordinary Shares in issue during the period. |
EPRA | European Public Real Estate Association, the industry body representing listed companies in the real estate sector. |
Estimated Rental Value (‘ERV’) | The external valuer’s opinion as to the open market rent which, on the date of the valuation, could reasonably be expected to be obtained on a new letting or rent review of a property. |
External Valuer | An independent external valuer of a property. The Group’s External Valuer is Knight Frank LLP. |
Fair value | The estimated amount for which a property should exchange on the valuation date between a willing buyer and a willing seller in an arm’s length transaction after proper marketing and where parties had each acted knowledgeably, prudently and without compulsion. |
Fair value movement | An accounting adjustment to change the book value of an asset or liability to its fair value. |
FCA | The Financial Conduct Authority. |
Gross Asset Value (‘GAV’) | The aggregate value of the total assets of the Group as determined in accordance with IFRS. |
Gross Passing Rental Income | The gross passing rent is the rent roll at the reporting date, taking account of any in-place rent free incentives or step rents on a straight-line basis over the following 12-month period. |
IASB | International Accounting Standards Board. |
ICR | Interest cover ratio is the passing rental income for the period less non recoverable costs, divided by the interest costs for the relevant period. |
IFRS | International financial reporting standards. On 31 December 2020 EU-adopted IFRS was brought into UK law and became UK-adopted international accounting standards, with future changes to IFRS being subject to endorsement by the UK Endorsement Board. |
Investment Adviser or Martley Capital | Martley Capital Real Estate Investment Management Limited. |
IPO | The admission to trading on the London Stock Exchange’s Main Market of the share capital of the Company and admission of Ordinary Shares to the premium listing segment (now the Closed-ended investment funds category) of the Official List on 6 June 2017. |
Lease incentives | Incentives offered to occupiers to enter into a lease. Typically, this will be an initial rent-free period, or a cash contribution to fit-out. Under accounting rules, the value of the lease incentive is amortised through the Consolidated Statement of Comprehensive Income on a straight-line basis until the lease expiry. |
Loan to Value (‘LTV’) | The value of loans and borrowings utilised (excluding amounts held as restricted cash and before adjustments for issue costs) expressed as a percentage of the combined valuation of the property portfolio (as provided by the valuer) and the fair value of other investments. |
Net Asset Value (‘NAV’) | Net Asset Value is the equity attributable to shareholders calculated under IFRS. |
Net Asset Value per share | Equity shareholders’ funds divided by the number of Ordinary Shares in issue. |
Net equivalent yield | Calculated by the Group’s External Valuers, net equivalent yield is the internal rate of return from an investment property, based on the gross outlays for the purchase of a property (including purchase costs), reflecting reversions to current market rent and items as voids and non-recoverable expenditure but ignoring future changes in capital value. The calculation assumes rent is received annually in arrears. |
Net Initial Yield (‘NIY’) | The initial net rental income from a property at the date of purchase, expressed as a percentage of the gross purchase price including the costs of purchase. Initial yield does not include cost of purchase. |
Net rental income | Rental income receivable in the period after payment of ground rents and net property outgoings. |
Ordinary Shares | The main type of equity capital issued by conventional Investment Companies. Shareholders are entitled to their share of both income, in the form of dividends paid by the Company, and any capital growth. |
REIT | A Real Estate Investment Trust. A company which complies with Part 12 of the Corporation Tax Act 2010. Subject to the continuing relevant UK REIT criteria being met, the profits from the property business of a REIT, arising from both income and capital gains, are exempt from corporation tax. |
Reversion | Increase in rent estimated by the Company’s External Valuers, where the passing rent is below the ERV. |
Share price | The value of a share at a point in time as quoted on a stock exchange. The Company’s Ordinary Shares are quoted on the Main Market of the London Stock Exchange. |
Weighted Average Unexpired Lease Term (‘WAULT’) | The average lease term remaining for first break, or expiry, across the portfolio weighted by contracted rental income (including rent-frees). |
Company Information
Share Register Enquiries
The register for the Ordinary Shares is maintained by Computershare Investor Services PLC. In the event of queries regarding your holding, please contact the Registrar on 0370 707 1874 or email: [email protected]
Changes of name and/or address must be notified in writing to the Registrar, at the address shown below. You can check your shareholding and find practical help on transferring shares or updating your details at www.investorcentre.co.uk. Shareholders eligible to receive dividend payments gross of tax may also download declaration forms from that website.
Share Information
Ordinary £0.01 shares | 80,500,000 |
SEDOL Number | BDVK708 |
ISIN Number | GB00BDVK7088 |
Ticker/TIDM | AIRE |
Share Prices
The Company’s Ordinary Shares are traded on the Main Market of the London Stock Exchange.
Frequency of NAV publication
The Group’s NAV is released to the London Stock Exchange on a quarterly basis and is published on the Company’s website www.alternativeincomereit.com.
Annual and Interim Reports
Copies of the Annual and Half-Yearly Reports are available from the Group’s website.
Financial Calendar
30 June | Year end |
October | Announcement of annual results |
December | Annual General Meeting |
31 December | Half year end |
March | Announcement of interim results |
Shareholder Information
DirectorsAdam Smith (non-executive Chairman)Ben Green (non-executive director)Rob Maybury (non-executive director) | Property ManagerMason Owen and Partners Limited7th Floor20 Chapel StreetLiverpoolL3 9AG |
Registered OfficeThe Scalpel 18th Floor52 Lime StreetLondonEC3M 7AFhttps://www.alternativeincomereit.com/Registered in England and Wales No. 10727886 | ValuerKnight Frank LLP55 Baker StreetLondonW1U 8AN |
Company SecretaryHanway Advisory LimitedThe Scalpel 18th Floor52 Lime StreetLondonEC3M 7AF | RegistrarComputershare Investor Services PLCThe PavilionsBridgwater RoadBristolBS13 8AE |
AIFMLangham Hall Fund Management LLPBroadwalk House, 3rd Floor5 Appold StreetBroadgateLondonEC2A 2DA | AuditorMoore Kingston Smith LLP9 Appold StreetLondonEC2A 2AP |
DepositaryLangham Hall UK Depositary LLPBroadwalk House, 3rd Floor5 Appold StreetBroadgateLondonEC2A 2DA | Corporate BrokerShore Capital & Corporate LtdCassini House,57 St James’s StreetLondonSW1A 1LD |
Investment Adviser and AdministratorMartley Capital Real Estate InvestmentManagement LtdThe Rookery, 4th Floor2 Dyott StreetLondonWC1A 1DE |
|
Related Shares:
Alternative Inc